When You’re the Boss, but Your Employees Make More Money
Power dynamics get complicated when managers earn less than their employees

 4 min

When NFL quarterback Justin Herbert and NBA star Jaylen Brown signed contracts this summer worth $262.5 million and $304 million, respectively, they struck the richest deals in their leagues’ histories. They’re also out earning their bosses by millions a year.
Professional athletes often command higher salaries than their coaches, since it’s harder to find people to execute plays than diagram them. And individual contributors can earn more than managers in a lot of fields, from finance and tech to sales and media.
The sticking point is how bosses and their charges deal with those imbalances.
There are two keys to a functional working relationship when a subordinate makes more money than their manager, people in both camps tell me: The boss must possess the humility to accept the situation and the confidence to project authority. And the highly paid employee can’t be a diva.
Richard Reice, a labor attorney and chief people officer of a restaurant group, says fat paychecks can lead to entitlement and make a highly paid employee practically unmanageable.
“Some refuse to do basic things, like attend meetings, just because they think they’re silly,” he says.
When leadership doesn’t pay
It’s hard to quantify how frequently rank-and-file workers make more than their bosses, but Reice says he has observed a shift from his dual perches in employment law and human resources. Many companies are scrapping the old notion that bigger titles should automatically mean bigger bucks. Instead of promoting star employees into management, where administrative duties can siphon time from their true talents, more businesses are keeping top performers in individual-contributor roles—and paying them like bosses.
Leadership, in these situations, is considered like any other skill, and not necessarily one that is worth more money.
We’re more likely to notice now when someone out earns the boss. The pandemic-era rise of distributed teams was accompanied by cost-of-living adjustments, which meant a manager based in an inexpensive town might earn less than direct reports living in pricier cities.
Pay-transparency laws have given some bosses the jarring experience of seeing less-senior positions at their companies posted on job boards with advertised salaries that exceed their own. Market demand can explain some discrepancies; in other cases, racial, age or gender biases could be to blame.
Keep your ego in check
Nikki Barua, who runs the women’s leadership program Beyond Barriers, says her clients in managerial positions sometimes feel underpaid relative to subordinates and are unsure whether discrimination is a factor. Bosses need to recognise there are often valid reasons behind pay, she says, and advises managers to pay more attention to what their fellow bosses make.
“The star performer is not the right comparison,” she says.
Barua says that in previous roles at technology and consulting firms, her knack for bringing in business sometimes led to incentives that pushed her pay over her managers’. She kept her ego in check by viewing her skill as a blessing, remembering that others might be equally good at different jobs that the labor market rewards less generously.
Now, as an entrepreneur trying to conserve cash, she’s sometimes paid herself less than her employees. She admits that, at times, it was hard not to resent people making more than she did, feeling that she’d be able to draw a salary if only they’d work harder or do better.
Founders often draw modest salaries, or none at all, in companies’ early days, says Jeff Bussgang, general partner in the Boston office of startup investor Flybridge Capital Partners.
“Naturally, if they own a big chunk of equity, it makes it all more palatable,” he says.
Plus, owners’ status is seldom in doubt, regardless of pay. Berkshire Hathaway CEO Warren Buffett, who acquired a controlling stake in the company in 1965, has for several decades taken an annual salary of $100,000. His total compensation last year was $401,589, while two vice chairmen earned more than $19 million apiece. Buffett, the world’s sixth-richest person with a net worth of $122 billion, according to the Bloomberg Billionaires Index, derives most of his income from investments.
Bosses who earn less
Ellen Taaffe, who sits on the compensation committees of several companies, including AARP Services, says corporate boards often set pay by studying the going rates for similar roles in other organisations. Boards can ease potential tension by giving junior executives lower base salaries and enabling them to surpass more senior leaders only through bonuses for exceeding expectations. Usually the people with the loftiest titles make the most money, but not always, notes Taaffe, who teaches at Northwestern University’s Kellogg School of Management.
For instance, the chief scientific officer of a biotech company—whose research might be the crux of the business’s success or failure—could be paid more than the CEO. George Yancopoulos, the chief scientific officer of Regeneron Pharmaceuticals, has received almost $435 million in total compensation since 2012, according to securities filings, making him the company’s highest-paid employee over that span. (Regeneron may be best known for its monoclonal antibody treatment for Covid.)
At some universities, the highest-paid employee isn’t the president; it’s the football coach or the person who manages the endowment. The $2.2 million pay package awarded to Yale University President Peter Salovey last fiscal year was one-third of what the chief investment officer earned, according to tax filings.
Leaders who successfully handle higher-paid employees find satisfaction in helping others shine, Taaffe says.
Warren Cereghino, a retired TV news director in California, says he kept pride at bay by reminding himself that viewers tuned in to watch his station’s anchors, who earned more than he did as their boss. He says the on-air talent didn’t abuse their sway.
Still, being privy to their contracts, he knew that some had negotiated a measure of editorial control in addition to large salaries. If there was a disagreement, he wouldn’t necessarily win.
“Even though my name was on the door of the news director’s office, there was a limit to my power,” he says.
—Theo Francis contributed to this article.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


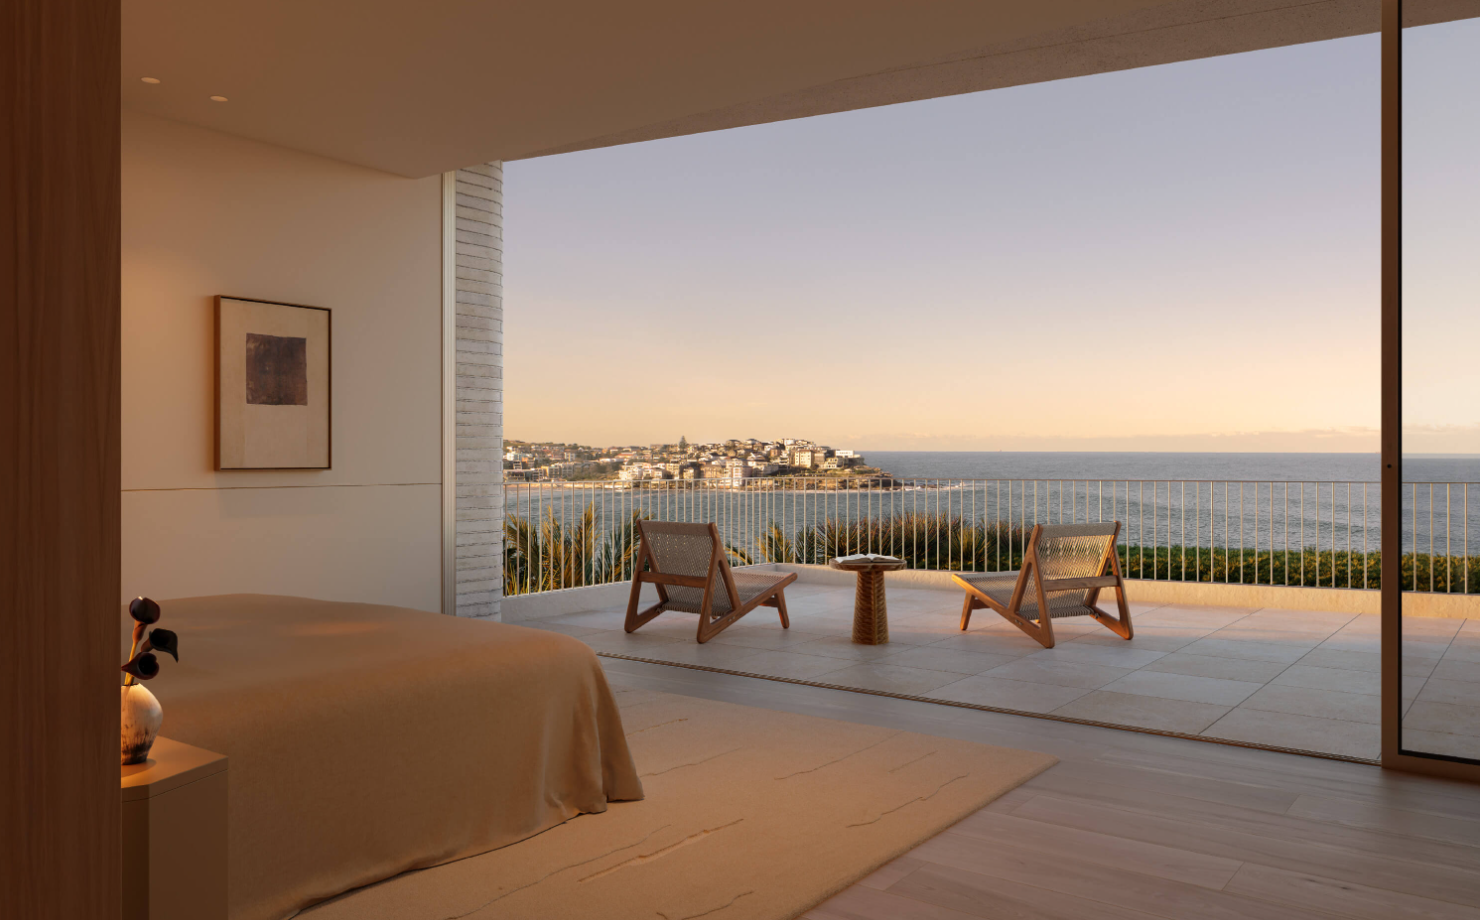
For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
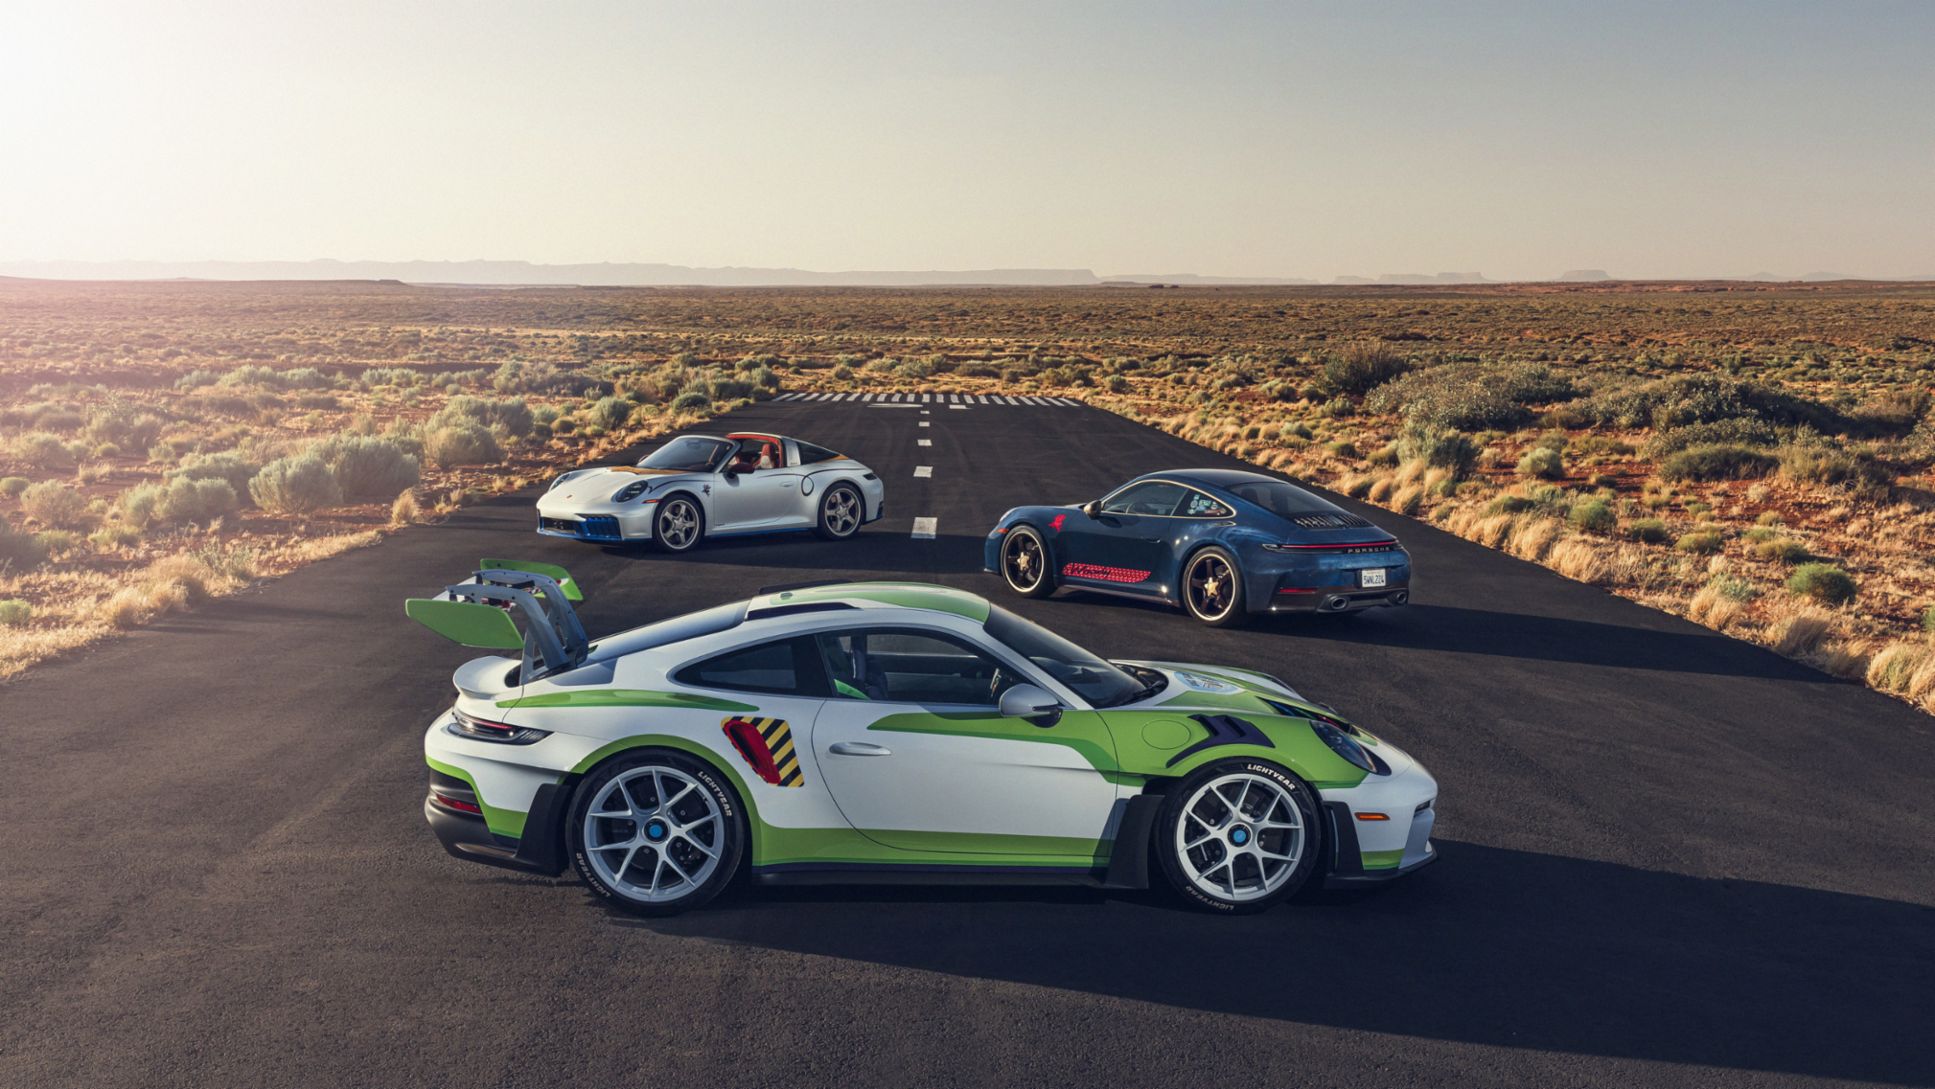
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.
3 min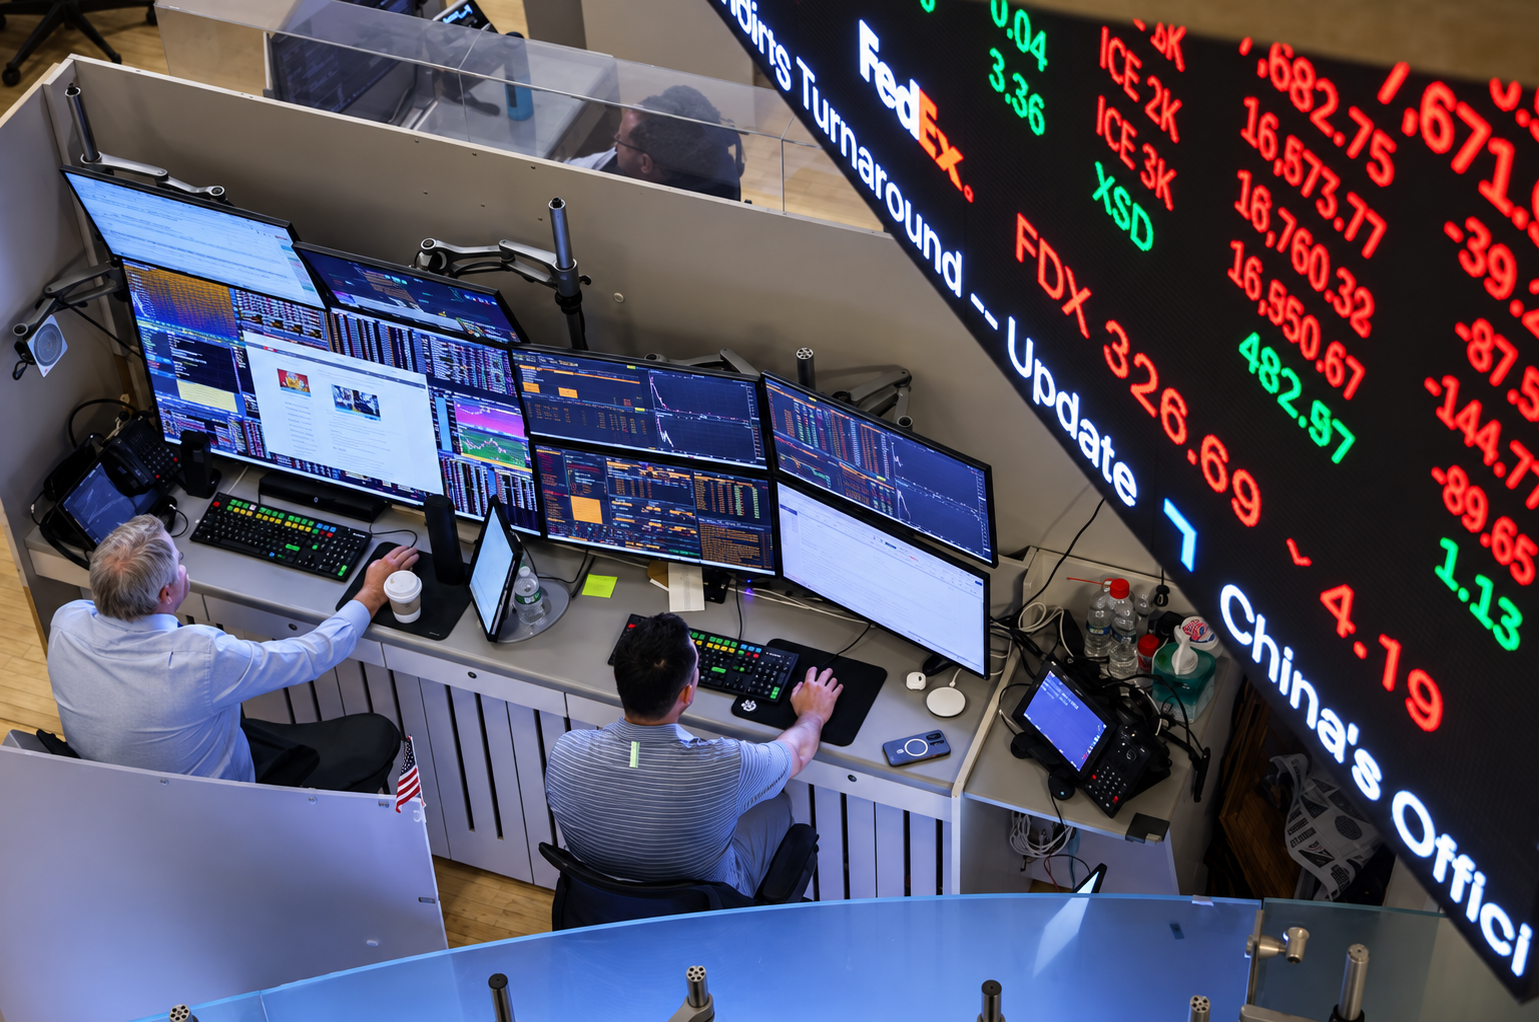
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”

MAISON de SABRÉ’s new Spring Harvest Collection turns everyday produce into collectible leather charms and introduces fresh silhouettes in its cult Bucket bag family.

A divide has opened in the tech job market between those with artificial-intelligence skills and everyone else.