Why 2025 Could Be a Great Year for Big Banks
After a few bumpy years of both successes and setbacks, lenders might finally be firing on all cylinders

 3 min

Top global banks have taken off in recent years, but ascents can be bumpy. In 2025, they might get to relax while on cruise speed.
The Federal Reserve recently signaled that interest rates might only be cut twice in the year ahead as a result of stickier-than-expected inflation, prompting stocks generally to sell off. But rates being “less high for longer” is actually great news for banks, and the latest sign that 2025 might be a good year for almost all of the many business lines that comprise large universal lenders.
This hasn’t been the case in recent times, even when financial firms overall were doing really well. In 2022, the big rebound in global trade that followed production stoppages during the depths of the pandemic resulted in a surge in sales for such transaction-focused intermediaries as Citigroup , HSBC Holdings and BNP Paribas . Desks that trade fixed income, currencies and commodities, or FICC, saw client flows balloon, as Russia’s full-scale invasion of Ukraine and the start of the rate-tightening cycle sparked a sudden demand to hedge rates, foreign exchange and energy prices around the world. The likes of JPMorgan Chase and Deutsche Bank benefited greatly.
But adverse monetary and geoeconomic conditions caused underwriting fees to collapse, as companies all simultaneously held off on issuing equity and debt.
Then came 2023. Large-bank revenue jumped once again, this time mostly driven by an 11% increase in net interest margins, Visible Alpha data shows. After a decade and a half, the industry was finally getting to benefit from a larger spread between what it was able to charge borrowers and pay to depositors. Yet, at the same time, dealmaking tumbled because of high borrowing costs and heightened economic and geopolitical uncertainty.
Some of the lopsidedness has persisted this past year, mostly because central banks have lowered rates again. That resulted in a fall in net interest income that has hit revenue in commercial and wealth-management arms, but also transaction banking, which does a lot of cash management for firms. Traders of government bonds and other rate-related products have had a tepid year. And, overall, revenue growth has slowed.
Nevertheless, 2024 is when the market truly rewarded bank stocks. The banking subcomponents of the S&P 500 and the Stoxx Europe 600 have returned 35% and 32%, respectively, compared with 25% and 6% for the broader indexes.
This underscores the importance that today’s investors attribute to getting predictable, well-diversified returns from their banks, rather than having another year with a quarter of revenue coming from FICC.
Indeed, this past year was still one of normalization. Mergers and initial public offerings bounced back a bit, and many corporate treasurers had to refinance their debt to avoid an incoming wall of bond maturities. And, even if investors eschewed government debt, they gobbled up the kinds of fixed-income products that offered a spread over it, such as corporate bonds, in an attempt to lock in high yields for the long run.
This is a good omen for the year ahead.
For the first time since 2021, all of the divisions of the world’s top banks except FICC trading are forecast to expand revenue, according to a median of analyst estimates compiled by Visible Alpha. Even that dark spot might end up brightening: As of early December, yields on three-month Treasury bills have been trading below those of 10-year paper for the first time since 2022, which might soon trigger renewed enthusiasm for fixed income.
Regardless, steeper yield curves will almost certainly be good for banks, serving to widen net interest margins.
To be sure, officials easing borrowing costs by less than previously expected could hit consumers and cause trouble for some commercial real-estate loans. The European economy in particular is quite weak. Still, the impact is likely to be small. Default rates remain low.
Crucially, 2025 looks likely to be the year in which the advisory business gathers momentum after a tentative comeback. Private-equity firms are being pressured to start exiting their investments after years of waiting it out. While sponsors have been coming up with new delaying tactics, such as rolling over assets into “continuation funds,” the management-consulting firm Bain estimated that 46% of companies owned by private-equity funds were held for four years or longer by the end of 2023, which was the highest level since 2012.
If, on top of this, the Trump administration eases regulatory scrutiny both on the financial sector and on mergers, banks will enjoy yet another tailwind , with Goldman Sachs probably coming out on top.
Banks might finally be firing on all cylinders.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.

A&K Sanctuary unveils Kitirua Plains Lodge, a sustainability-focused luxury property shaped by landscape, local craft and contemporary safari architecture.
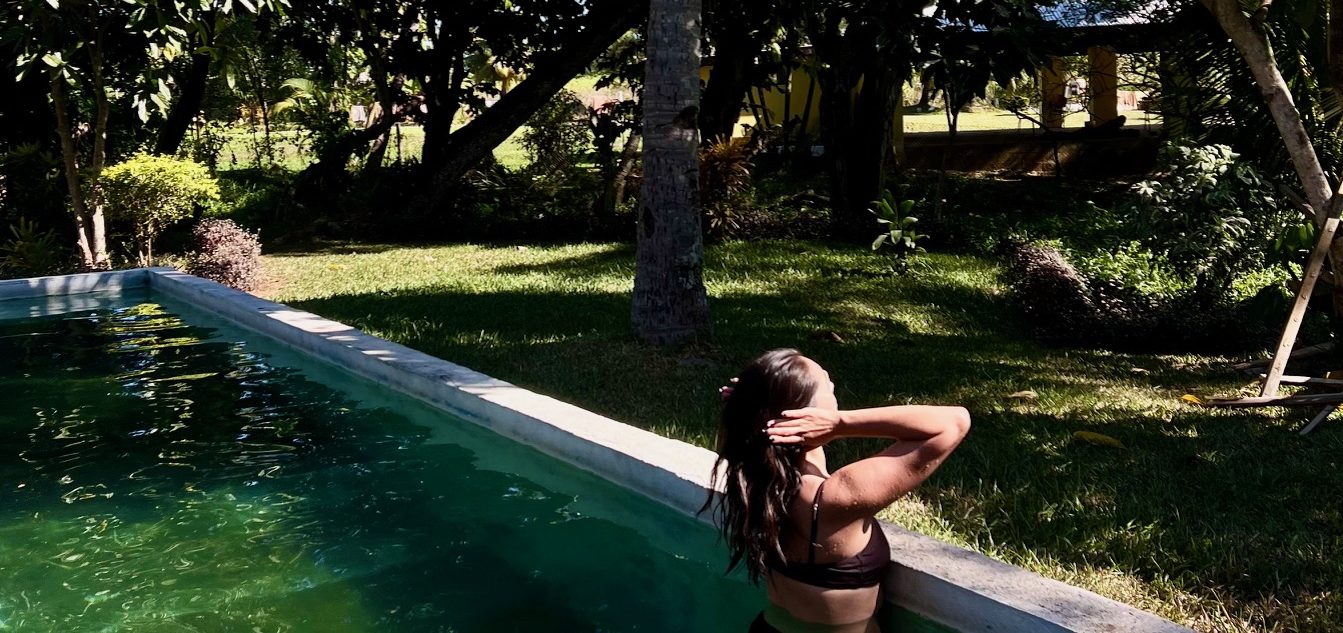
From mud baths to herbal massages, Fiji’s heat rituals turned one winter escape into a soul-deep reset.