Why Americans Are Obsessed With These Ugly Sandals
Margot Fraser’s feet hurt. Then she found Birkenstocks and brought them to the U.S. Now the company is worth billions of dollars.

 6 min
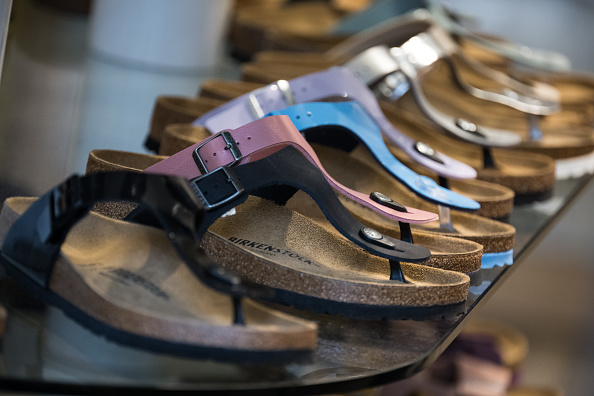
One of the iconic shots of the year’s biggest movie was Margot Robbie’s Barbie character in Birkenstocks.
She was only wearing them because of Margot Fraser.
This woman responsible for bringing the supremely comfy, seductively ugly German footwear to the U.S. was one of the most improbable business figures of her time.
She was an accidental entrepreneur who started distributing Birkenstocks from her California home in the 1960s, when nobody knew what they were or how orthopaedic sandals cured foot pain. The only places that would carry them were health-food stores, where each pair might as well have come with a jar of granola. She was a dressmaker with no clue about shoes, much less crunchy ones, but she grew the company from zero to hundreds of millions of dollars in sales. She would even come to be known as Mrs. Birkenstock.
The sandals that she introduced to Americans have become more popular and the business much bigger than Fraser could have predicted. This week, when Birkenstock went public, the company was valued at $8.6 billion.
It’s fitting that Birkenstock’s initial public offering comes on the heels of a summer ruled by the spending power of women because this is a company whose U.S. business has always been built around their needs.
That’s in large part because of Margot Fraser, the most important woman in the company’s history. She paid attention to women—and it paid off. They were her first customers. They were also her best customers. Birkenstock’s financial documents credit “the breakthrough of modern feminism” as a key driver of its business, and the company’s private-equity backers cite the products’ appeal to women as one of the reasons they invested. In fact, Birkenstock says 72% of its customers are female.
It’s a remarkably high number for a company that explicitly markets its products as unisex. Steve Jobs wore them. Sneaker geeks want them. They were designed by Karl Birkenstock, a son of Carl and grandson of Konrad, descendants of the man who started the family’s tradition of shoemaking 249 years ago. More recently, the private-equity firm and family office of Bernard Arnault, the billionaire chief executive of LVMH’s luxury empire, bought a controlling stake and took the company public.
Anyone can now own stock in BIRK because of its connection to one of the world’s richest men, but Birkenstock never would have been in this position without a pioneering woman.
“It is because of Margot and the foundation she built that the brand is enjoying the success that it is today,” the president of the company’s American division said when she died in 2017.
She was the first to admit that she was an unlikely footwear executive and had to learn how to run the business one step at a time.
“I didn’t know a thing about shoes,” she once said. “What I did know was that my feet were always hurting.”
But that was all she needed to know. She figured that millions of women across the country must have feet that were always hurting, too.
Fraser had a keen sense of the American consumer for someone who grew up in war-torn Germany. The principal of her elementary school in the 1930s taught her that “girls were capable of anything and should follow their dreams,” but not everyone in her life agreed. “My mother thought that was all ridiculous feminist stuff,” Fraser wrote in a book offering business advice. Her father wasn’t exactly Betty Friedan, either. When she told him she wanted to travel the world for business and show people that “not all Germans were bad,” he responded: “My dear, you could never do that as a woman.”
She went to dressmaking school and moved to the countryside to make clothing for farmers, who paid her in eggs and butter. It was the teenager’s first taste of entrepreneurship. When she couldn’t see a future in Germany after World War II, she decided to leave home in pursuit of her childhood dream, and she boarded a trans-Atlantic ship with $25 in her pocket.
But it was only when Fraser returned as a tourist nearly 15 years later that she discovered the shoes that would rescue her feet and transform her life.

She was living in the U.S. when she took a spa trip back to Germany in 1966 and came across “sandals that weren’t pretty to look at.” But after years of trying anything to fix her aching feet—even standing on a phone book and gripping it with her toes—she tried on her first Birkenstocks.
She was pain-free within months.
Fraser realised that her feet were always hurting because of her painful footwear. No amount of standing on phone books would have made a difference for women in constrictive heels with pointed toes. What did make the difference for Fraser were these sandals made with leather, cork and a footbed the Birkenstock men invented. They were following in the footsteps of Johannes Birkenstock, which date back to 1774, when the cobbler was mentioned in the church records of a village near Frankfurt. The company’s first sandals were released in 1963, not long before Fraser slipped them on.
They were so comfortable that she didn’t care if they were ugly. Birkenstocks provided value because they solved a problem. They were basically Hokas for hippies.
Fraser took the sandals back to the U.S. and wrote to the Birkenstock family asking if she could sell them to Americans. They said yes to the dressmaker. At first, it seemed unwise. The owners of local shoe stores wouldn’t talk to her, and doctors treated her like a threat to the podiatry business.
She was desperate when a friend mentioned that a group called the Health Food Association was hosting a national convention nearby, which is how she found herself in a San Francisco hotel pitching sandals to people who sold lentils.
She needed to find people who didn’t mind how their shoes looked. As it turns out, they were the kind of people who owned health-food stores. Because they spent all day on their feet, they chose function over fashion. Fraser knew there would be a market for Birkenstocks when she spotted a woman at the convention shuffling around in nylons while carrying shoes that she couldn’t wear.
“The woman tried on a pair,” she wrote, “and bought them despite her husband’s protests.”
Once she had a foothold, Fraser began working out of her Bay Area home in 1967, calling her distribution company Birkenstock Footprint Sandals. She later renamed it Birkenstock USA.
She couldn’t have picked a better time or place for Birkenstocks to come plodding into the U.S. They would have crossed the ocean eventually, but the sandals became a symbol of rebellion because they landed in the heart of the counterculture, when and where people were allergic to the mainstream and willing to wear their antiestablishment values on their feet. “It was this perfect moment,” said Andrea Schneider-Braunberger, the curator of Birkenstock’s historical archives. “The culture was ready for such modern, convention-breaking shoes.”
Fraser worked closely with the Birkenstock family and shared their complete obsession with Birkenstocks. They made the shoes and decisions for the entire company based on her feedback.
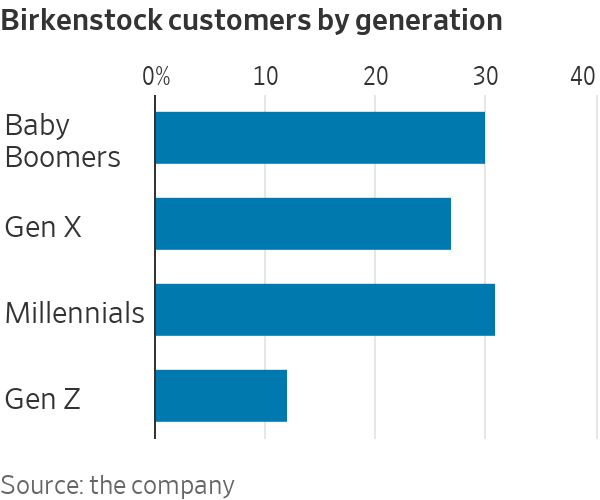
The name of the funny-looking sandal that caught her eye was the “Original Birkenstock-Footbed sandal,” but Fraser told her German partners that American women were never going to buy something called “Original Birkenstock-Footbed sandal.” They took her marketing advice and branded the single-strapped sandal the “Madrid.” It remains one of the company’s top sellers.
It took six years for Fraser to venture beyond health-food stores and move into actual footwear stores. But that timing also turned out to be advantageous. By then, people were ready to buy Birkenstocks, and she was better at selling them.
She knew they intrigued baby boomers who didn’t want to look like their mothers and fathers. As it happens, their children don’t mind looking like them. Now, boomers and millennials make up almost the exact same percentage of Birkenstock’s consumers, and the company’s Arizona sandals and Boston clogs can be found in high schools and retirement homes.
The business is also barely recognisable from when she sold Birkenstock USA to her employees and retired in 2002. It was later folded into the German parent company, which is run by Oliver Reichert, the first person outside the Birkenstock family to be the CEO. Arnault’s L Catterton invested in 2021 with eyes on this week’s IPO.
Birkenstock has expanded into sneakers, boots and sandals in wool, shearling and waterproof material. Its proudly frumpy sandals meant to free women from the norms of fashion have become posh enough for celebrities, models and collaborations with Manolo Blahnik. The people who once turned up their noses at them now put their feet in them. And the company’s dominant market is the U.S.
None of that would have been possible without Margot Fraser.
Neither would the final scene in “Barbie.”
To sell more sandals to more Americans, she was always begging her partners for more colours, so Fraser would have been delighted to see what’s on the feet of another woman named Margot.
She’s wearing a pair of pink Birkenstocks.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
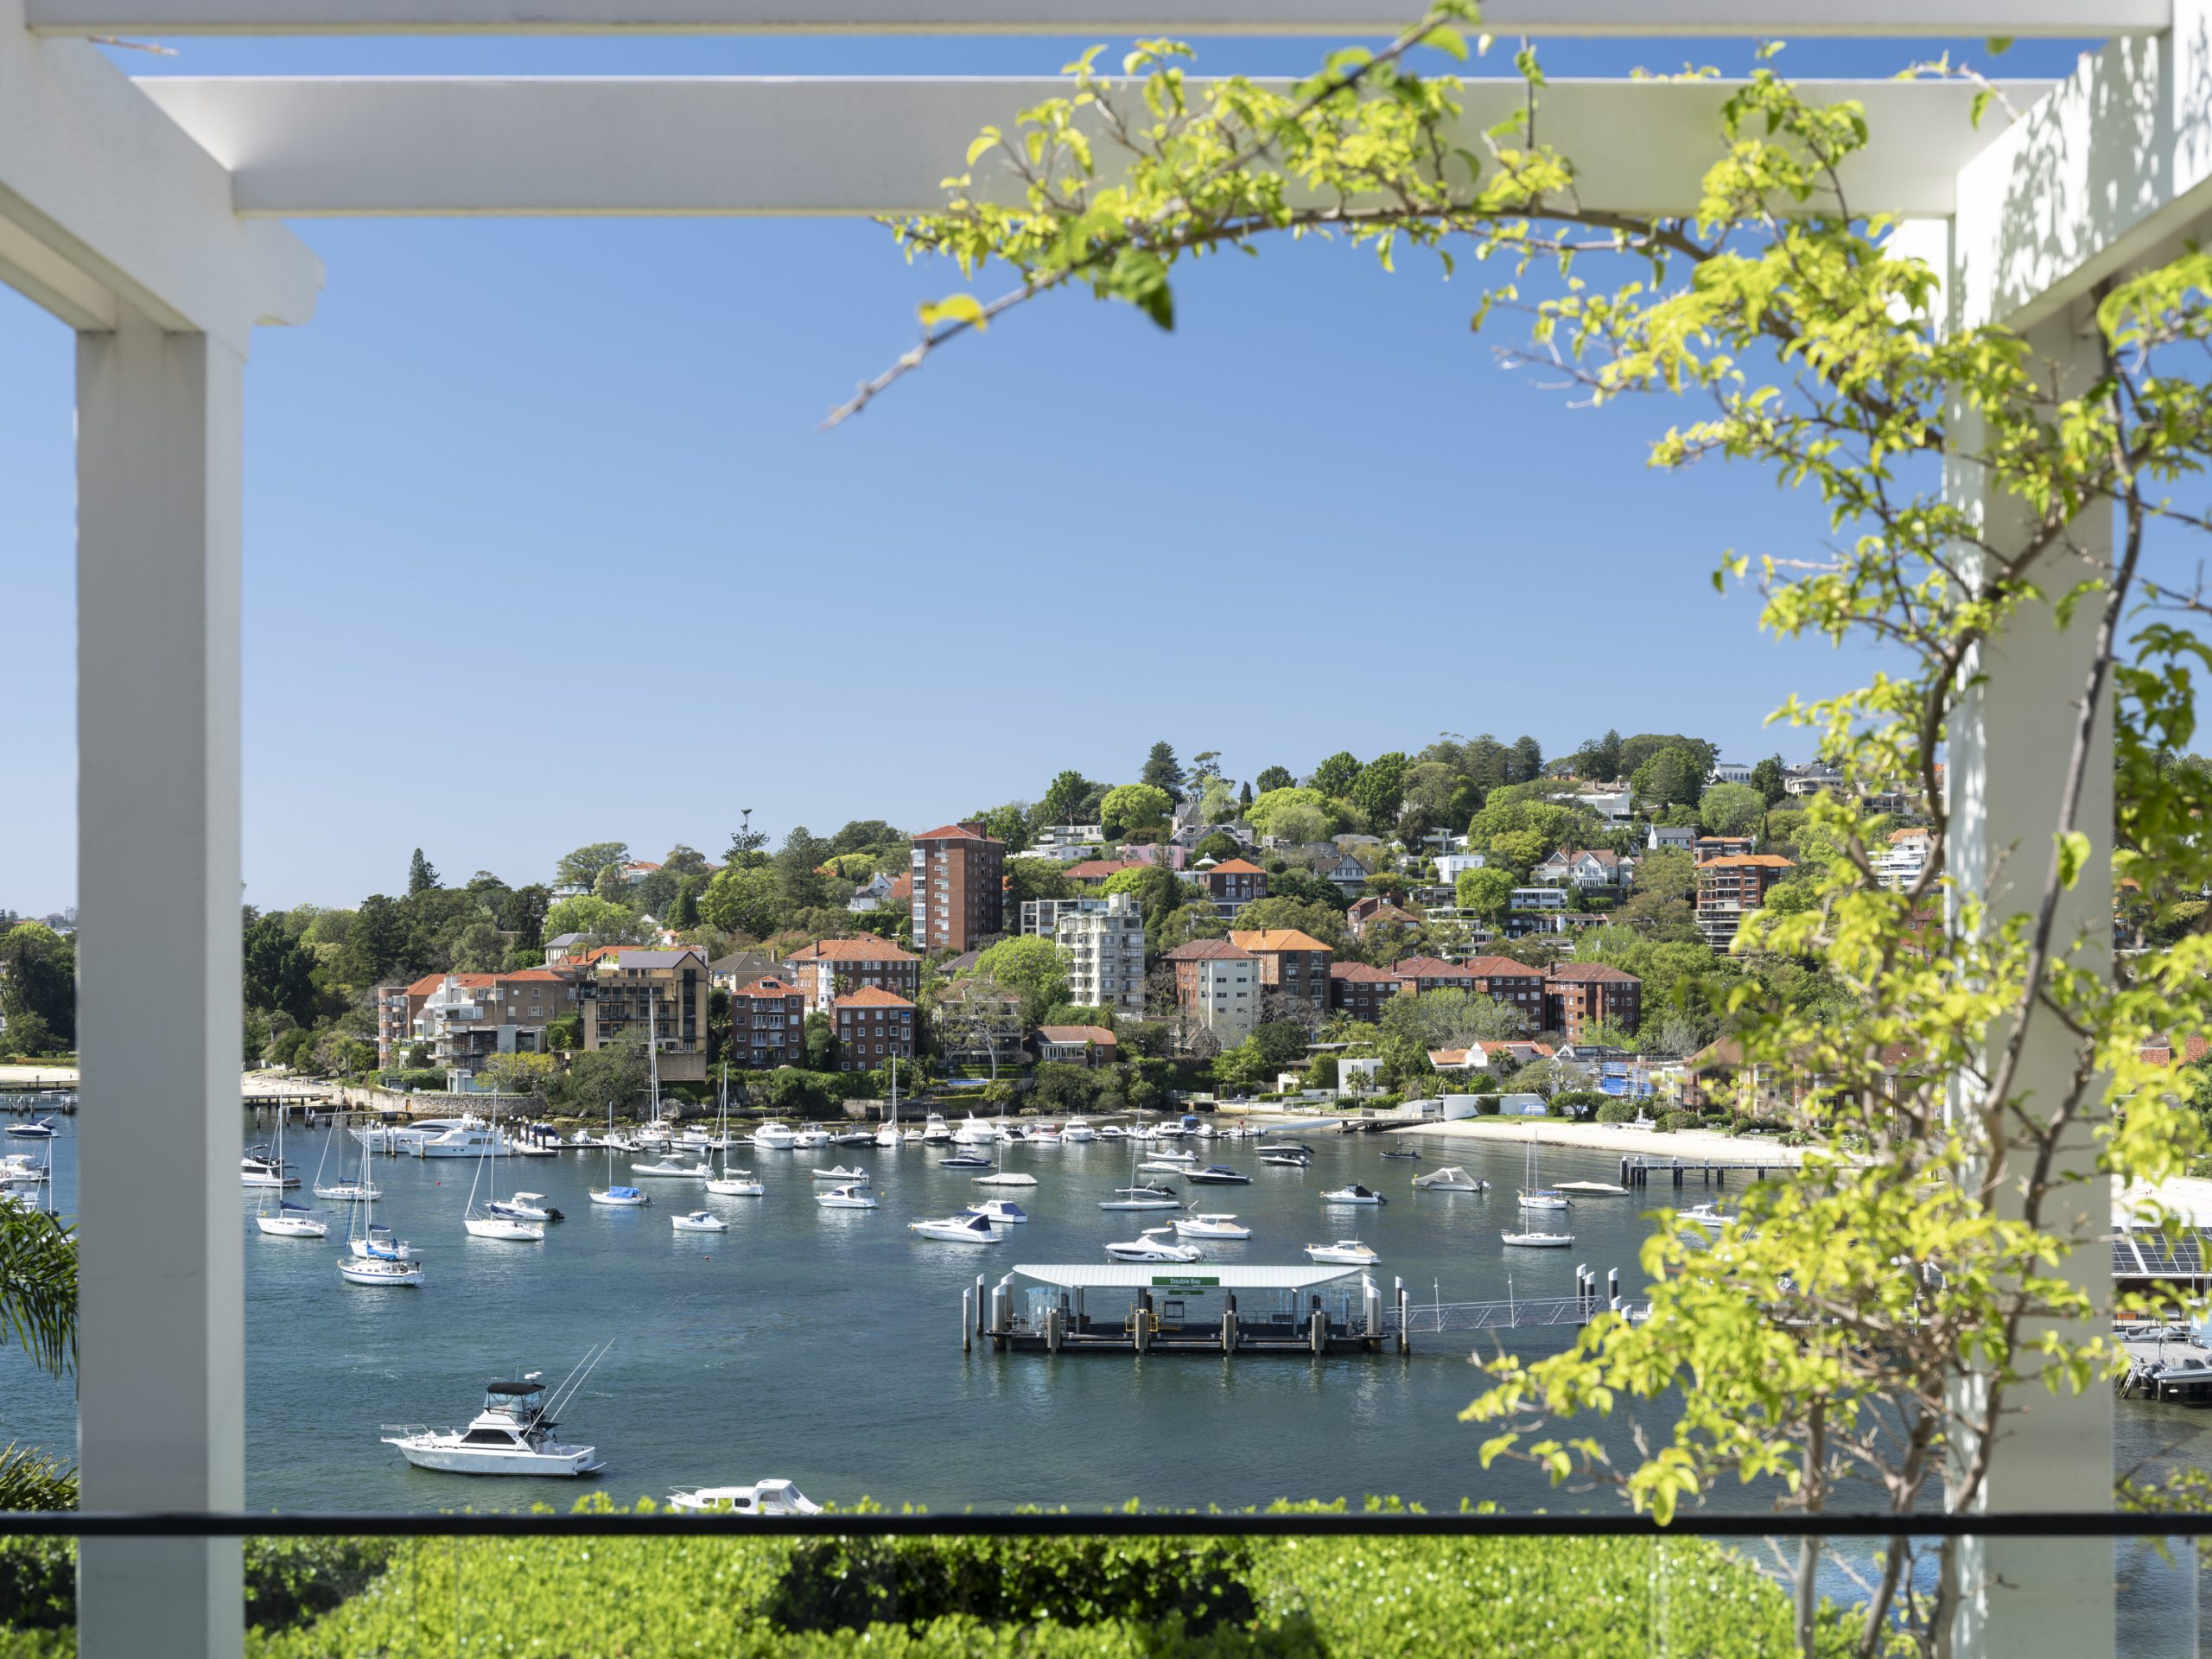
The grand harbourside residence combines sweeping Sydney Heads views, resort-style entertaining and refined designer finishes with a reported $36 million price guide.
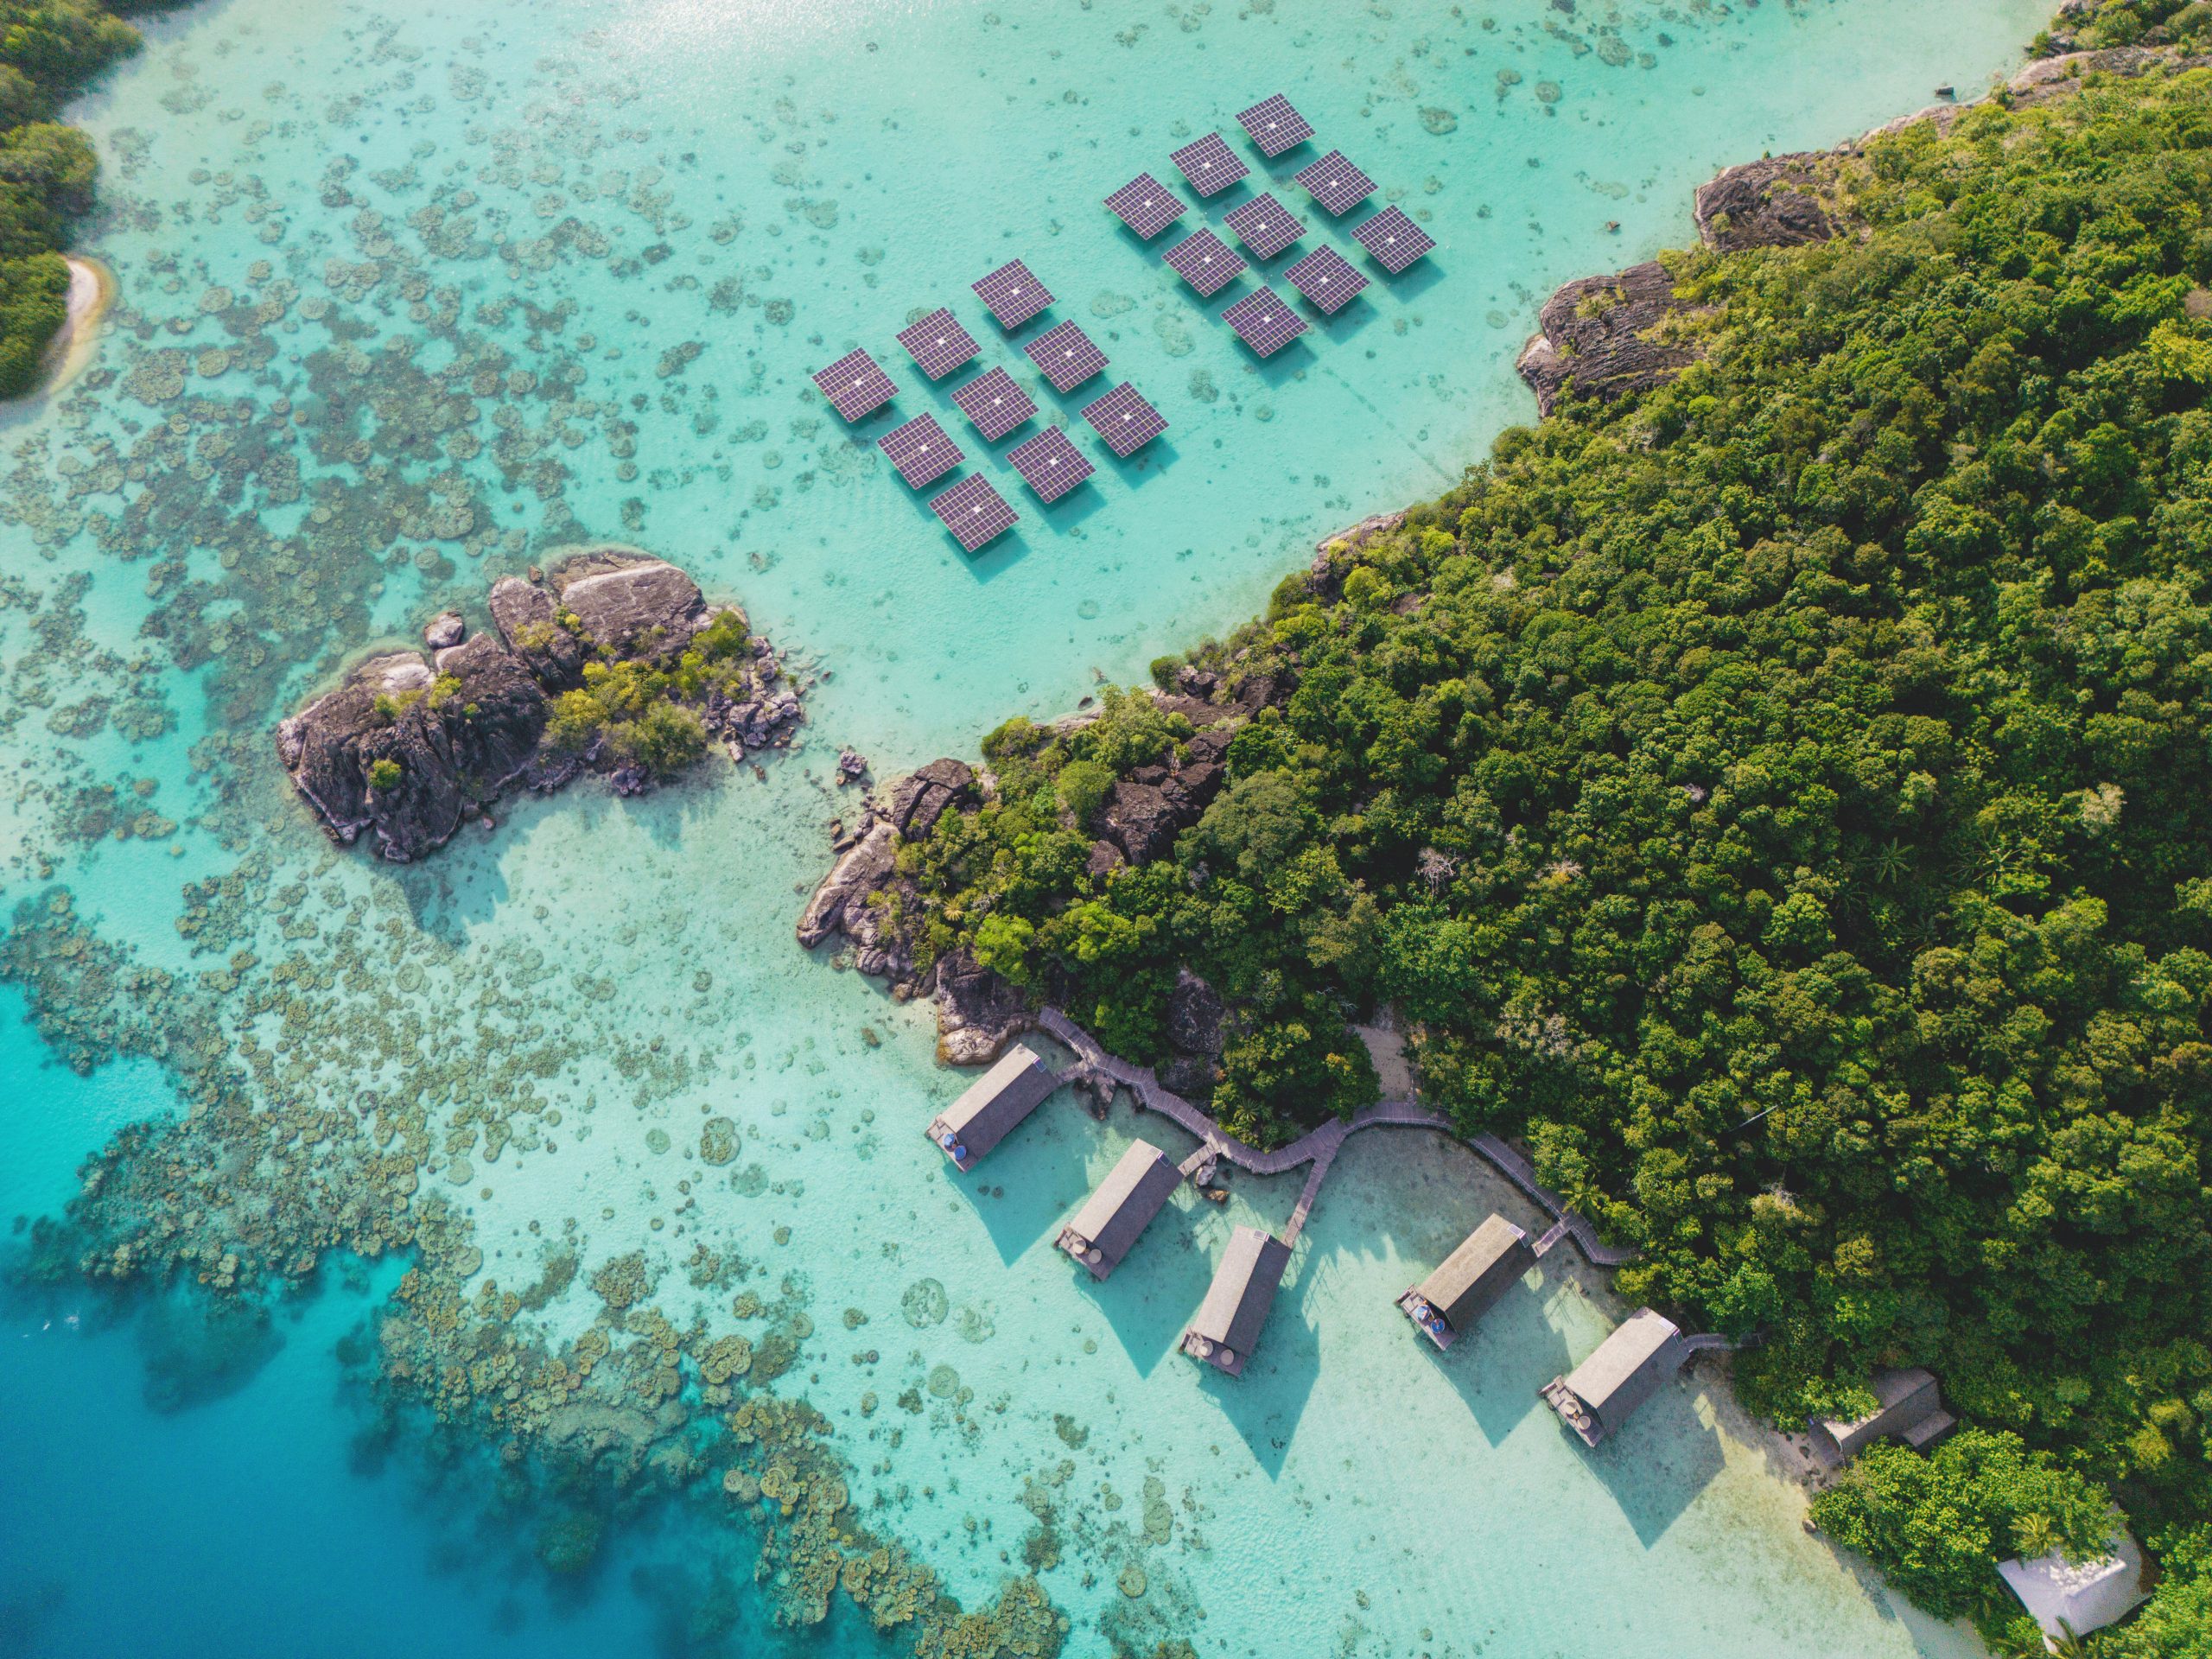
In the remote waters of Indonesia’s Anambas Islands, Bawah Reserve is redefining what it means to blend barefoot luxury with environmental stewardship.