

9 Ways the Latest Rate Cuts Can Save You $10,000 a Year
Interest rate cuts are finally giving homeowners breathing room—but how you use the savings can make a big difference.
 3 min

After years of rising repayments, Australians are finally seeing interest rates ease. February’s 0.25 percentage point cut shaved $76 a month off a $500,000 mortgage repayment, but the total savings could be more than $1,000 a year. With that extra money now flowing through, smart moves can turn small monthly savings into thousands over time.
1. Refinance your loan
Lower rates mean better borrowing power and increased competition by lenders for customers. As such, it’s a great time to consider refinancing.
You could double (or more!) the size of this rate cut – especially if your pay recently increased or your costs decreased, such as no more school fees after a child graduates.
Potential difference: $151.42 monthly savings by doubling the official rate cut to 5.55 per cent on a $500,000 mortgage.
2. Keep repayments the same
Just because rates have come down doesn’t mean you have to pay that new amount.
If you can afford to, keep your repayments the same. The extra amount you’re paying will chip away at the principal loan balance faster, meaning the amount you owe decreases and less interest accrues in future.
Potential difference: $26,588.07 saved over 25 years on a $500,000 mortgage. Over time, the savings would be 2.37 years of interest saved, which is over $60,000.
3. Pay down debts
Falling mortgage repayments mean more money to put towards paying down other debts.
Start with high-interest debts first, such as credit cards or car loans – these balloon quickly if you fall behind and adversely affect your ability to refinance your mortgage or get a new loan.
Potential difference: $151.43 monthly savings by clearing a $1,634 credit card debt with average 20.08 per cent interest rate.
4. Reassess savings accounts
The flip side of falling interest rates is that savings accounts and new term deposits become less attractive.
It may be worthwhile to reinvest your savings somewhere with higher earning potential. This becomes increasingly important the more interest rates fall. You should also consider tax though.
Potential difference: $1.68/month is small, but this also excludes compound earnings investing $76.15 monthly at 7.5 per cent sharemarket returns vs 5.25 per cent in a high-interest savings account.
5. Top up your super
Your superannuation balance will grow faster with more money going in and compound earnings between now and retirement. Plus, there are generous tax breaks for making voluntary super contributions.
Potential difference: $23.00 extra per year (excluding compound earnings and tax savings which is the bigger saving) contributing $76.15 per month at average 8.1 per cent returns.
6. Upskill to boost your income
Extra cash can be used towards study/qualifications to boost future earnings. Or you could start a side hustle that could deliver additional income or even allow you to earn more than your current job pays.
Potential difference: Just a 5% increase on the average $1,396 weekly income delivers an extra $3,629.60 per year. Self-education and self-employment costs are tax deductible too!
7. Invest in yourself
Investing in your health (physical and mental) has longer-term benefits: lower medical bills, fewer sick days, reduced risk of forced early retirement or premature death.
Potential difference: Thousands of dollars and a long, healthy life vs a shorter lifespan and/or poorer quality of life.
8. Boost your emergency fund
It is easier to build an emergency fund – cash set aside for a rainy day – in smaller, regular amounts than big lump sums. Rate cut savings are ideal for this, as you’re already used to living without this money.
Potential difference: Immeasurable if it’s the difference between having money set aside or having nothing, should disaster strike!
9. Donate to charity
If you’re going to spend your rate cut money no matter what, why not donate it to charity.
It will do some good for the world and give you the satisfaction that comes from helping others. Plus, you can claim a tax deduction on donations over $2.
Potential difference: You can receive a refund of up to 45 cents on every dollar donated, depending on your tax bracket.
As the above points show, there are plenty of ways to make rate cuts work even harder for you. The biggest difference will be whether you take action or let the savings flutter away
Helen Baker is a licensed Australian financial adviser and author of the new book, Money For Life: How to build financial security from firm foundations (Major Street Publishing $32.99). Find out more at www.onyourowntwofeet.com.au
For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
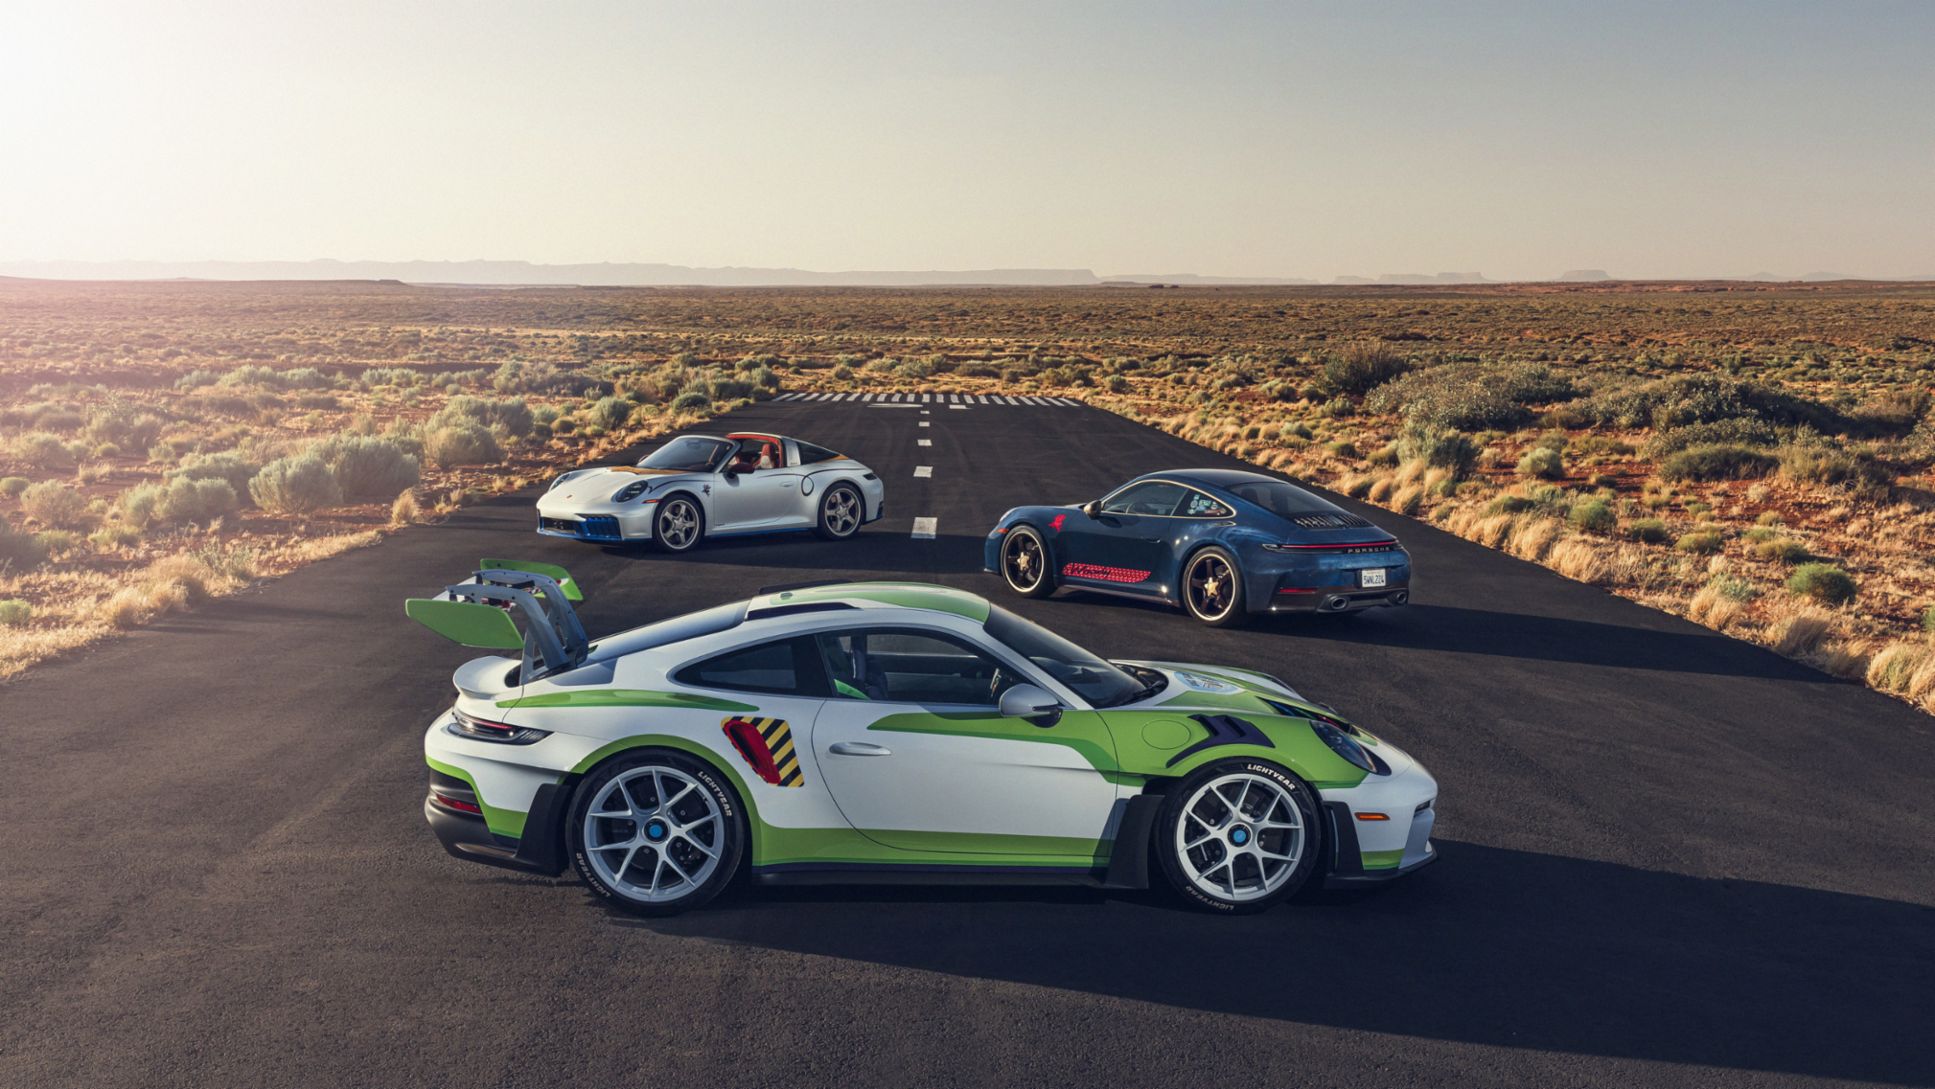
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Investors are bracing for a bumpier fall stock market due to shifting odds of a Federal Reserve interest-rate increase and other macro challenges.
3 min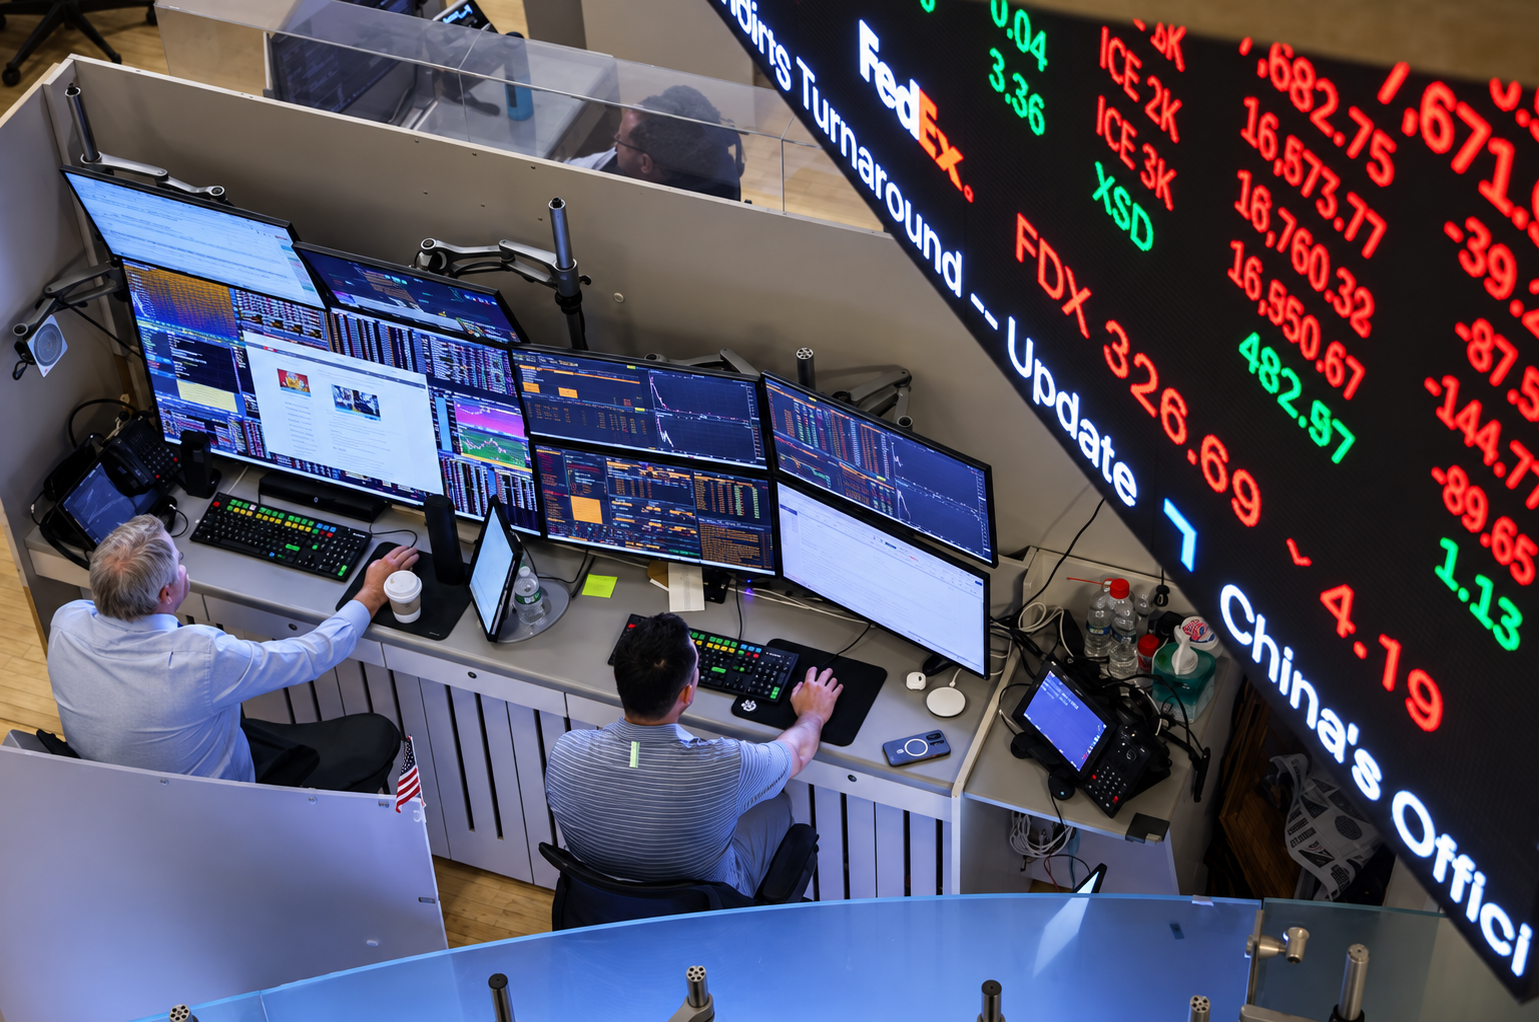
The stock market had a decent summer. Investors are bracing for a bumpier fall.
In the past couple of months, equity investors cheered soaring profits at big companies, shrugged off jitters in the bond market and nudged megacap tech shares back near records.
Now, as the post-Labor Day stretch begins, a number of new challenges lie ahead: ever-shifting odds of an interest-rate increase from the Federal Reserve. Sky-high expectations after a stunning earnings season. The persistent threat of higher consumer prices as fighting in the Middle East drags on.
“You’re moving from this earnings-driven market to this macro-driven market with the Fed, inflation and interest rates in focus,” said Keith Lerner, chief investment adviser for Truist Advisory Services. “It tends to be a choppier period.”
Historically, every major U.S. stock index experiences its worst average return in September. The Dow Jones Industrial Average has slid an average 1.1% in the ninth month of the year, in data that dates back to the 19th century. The S&P 500 has seen the same average decline—and for every September dating back to 1928, the benchmark ends the month lower more than half of the time.
Analysts caution against reading too much into those seasonal patterns. But in recent weeks, new reasons for investor caution have emerged. One of the largest: the looming threat of an interest-rate increase from the Fed, which announces its next policy decision on Sept. 16.
Chairman Kevin Warsh’s decision to ditch forward guidance and take more of his cues from markets has muddied the waters for investors when it comes to monetary policy. That has left traders scouring Fed governor speeches and economic-data reports for clues on the central bank’s next move.
“There’s going to be a lot of eyes on those numbers,” said John Luke Tyner, head of fixed income and portfolio manager at Aptus Capital Advisors.
The past couple of weeks offered just one example of how frequently those expectations can change. After Warsh struck a hawkish tone during remarks on Aug. 28, the odds of a hike at the Fed’s next meeting jumped from 35% before the speech to 58%, according to CME FedWatch data.
On Thursday, Fed governor Christopher Waller made a case for leaving rates where they are. Interest-rate futures showed coin-flip odds between a hike and a hold. Then Friday’s robust jobs report amped up rate-hike bets once more, back to a roughly 60% chance of higher rates after the meeting.
“Rates have really been driving the car for equities the last few weeks,” said Ross Mayfield, an investment strategist at Baird.
That uncertainty comes as an unruly bond market could put pressure on stocks. Treasury yields have marched higher for much of the summer, driven by concerns about rising oil prices, growing U.S. budget deficits and a deluge of tech-company bonds now competing for investors’ cash. Last week, the rout went global, pushing yields to multiyear highs in Japan, Germany and the U.K.
Higher bond yields can drag on stock prices and lift borrowing costs for companies and consumers across the economy.
Rising prices remain the top concern for bond traders, and continued fighting between the U.S. and Iran has done little to ease those worries. The national average price of diesel climbed to a record of $5.850 on Friday, according to AAA. That is up from $3.712 a year ago.
Investors will get more insight on the path of prices this week, with the much-awaited consumer-price index report due Friday and a reading on producer prices Thursday.
With another blockbuster earnings season in the books, some analysts have also warned that any boost from the third-quarter reports due in the coming months could be minimal. Back-to-back quarters of standout profits have raised expectations and made it especially difficult to impress traders. Custom-chip company Broadcom, for example, said Wednesday that it more than tripled its earnings and nearly doubled its revenue. Shares slipped 2.7% the next session.
Many analysts note there are plenty of reasons not to panic. The economy is in impressive shape, thanks to a healthy labor market and the rippling effects of the artificial-intelligence investment boom. Profits are booming at America’s biggest companies. The Cboe Volatility Index has dropped to its lowest levels of 2026. Credit spreads are tight, a sign bond investors aren’t concerned about economic conditions that could hurt companies.
But the mood has shifted from the euphoria that felt tangible when the Nasdaq was notching back-to-back records early this summer. The question, Mayfield said, is whether the fundamentals that have bolstered the bull market so far can stretch the rally into 2027.
“There are more anxieties or uncertainties about the backdrop,” he said. “It does feel like a transitional moment.”
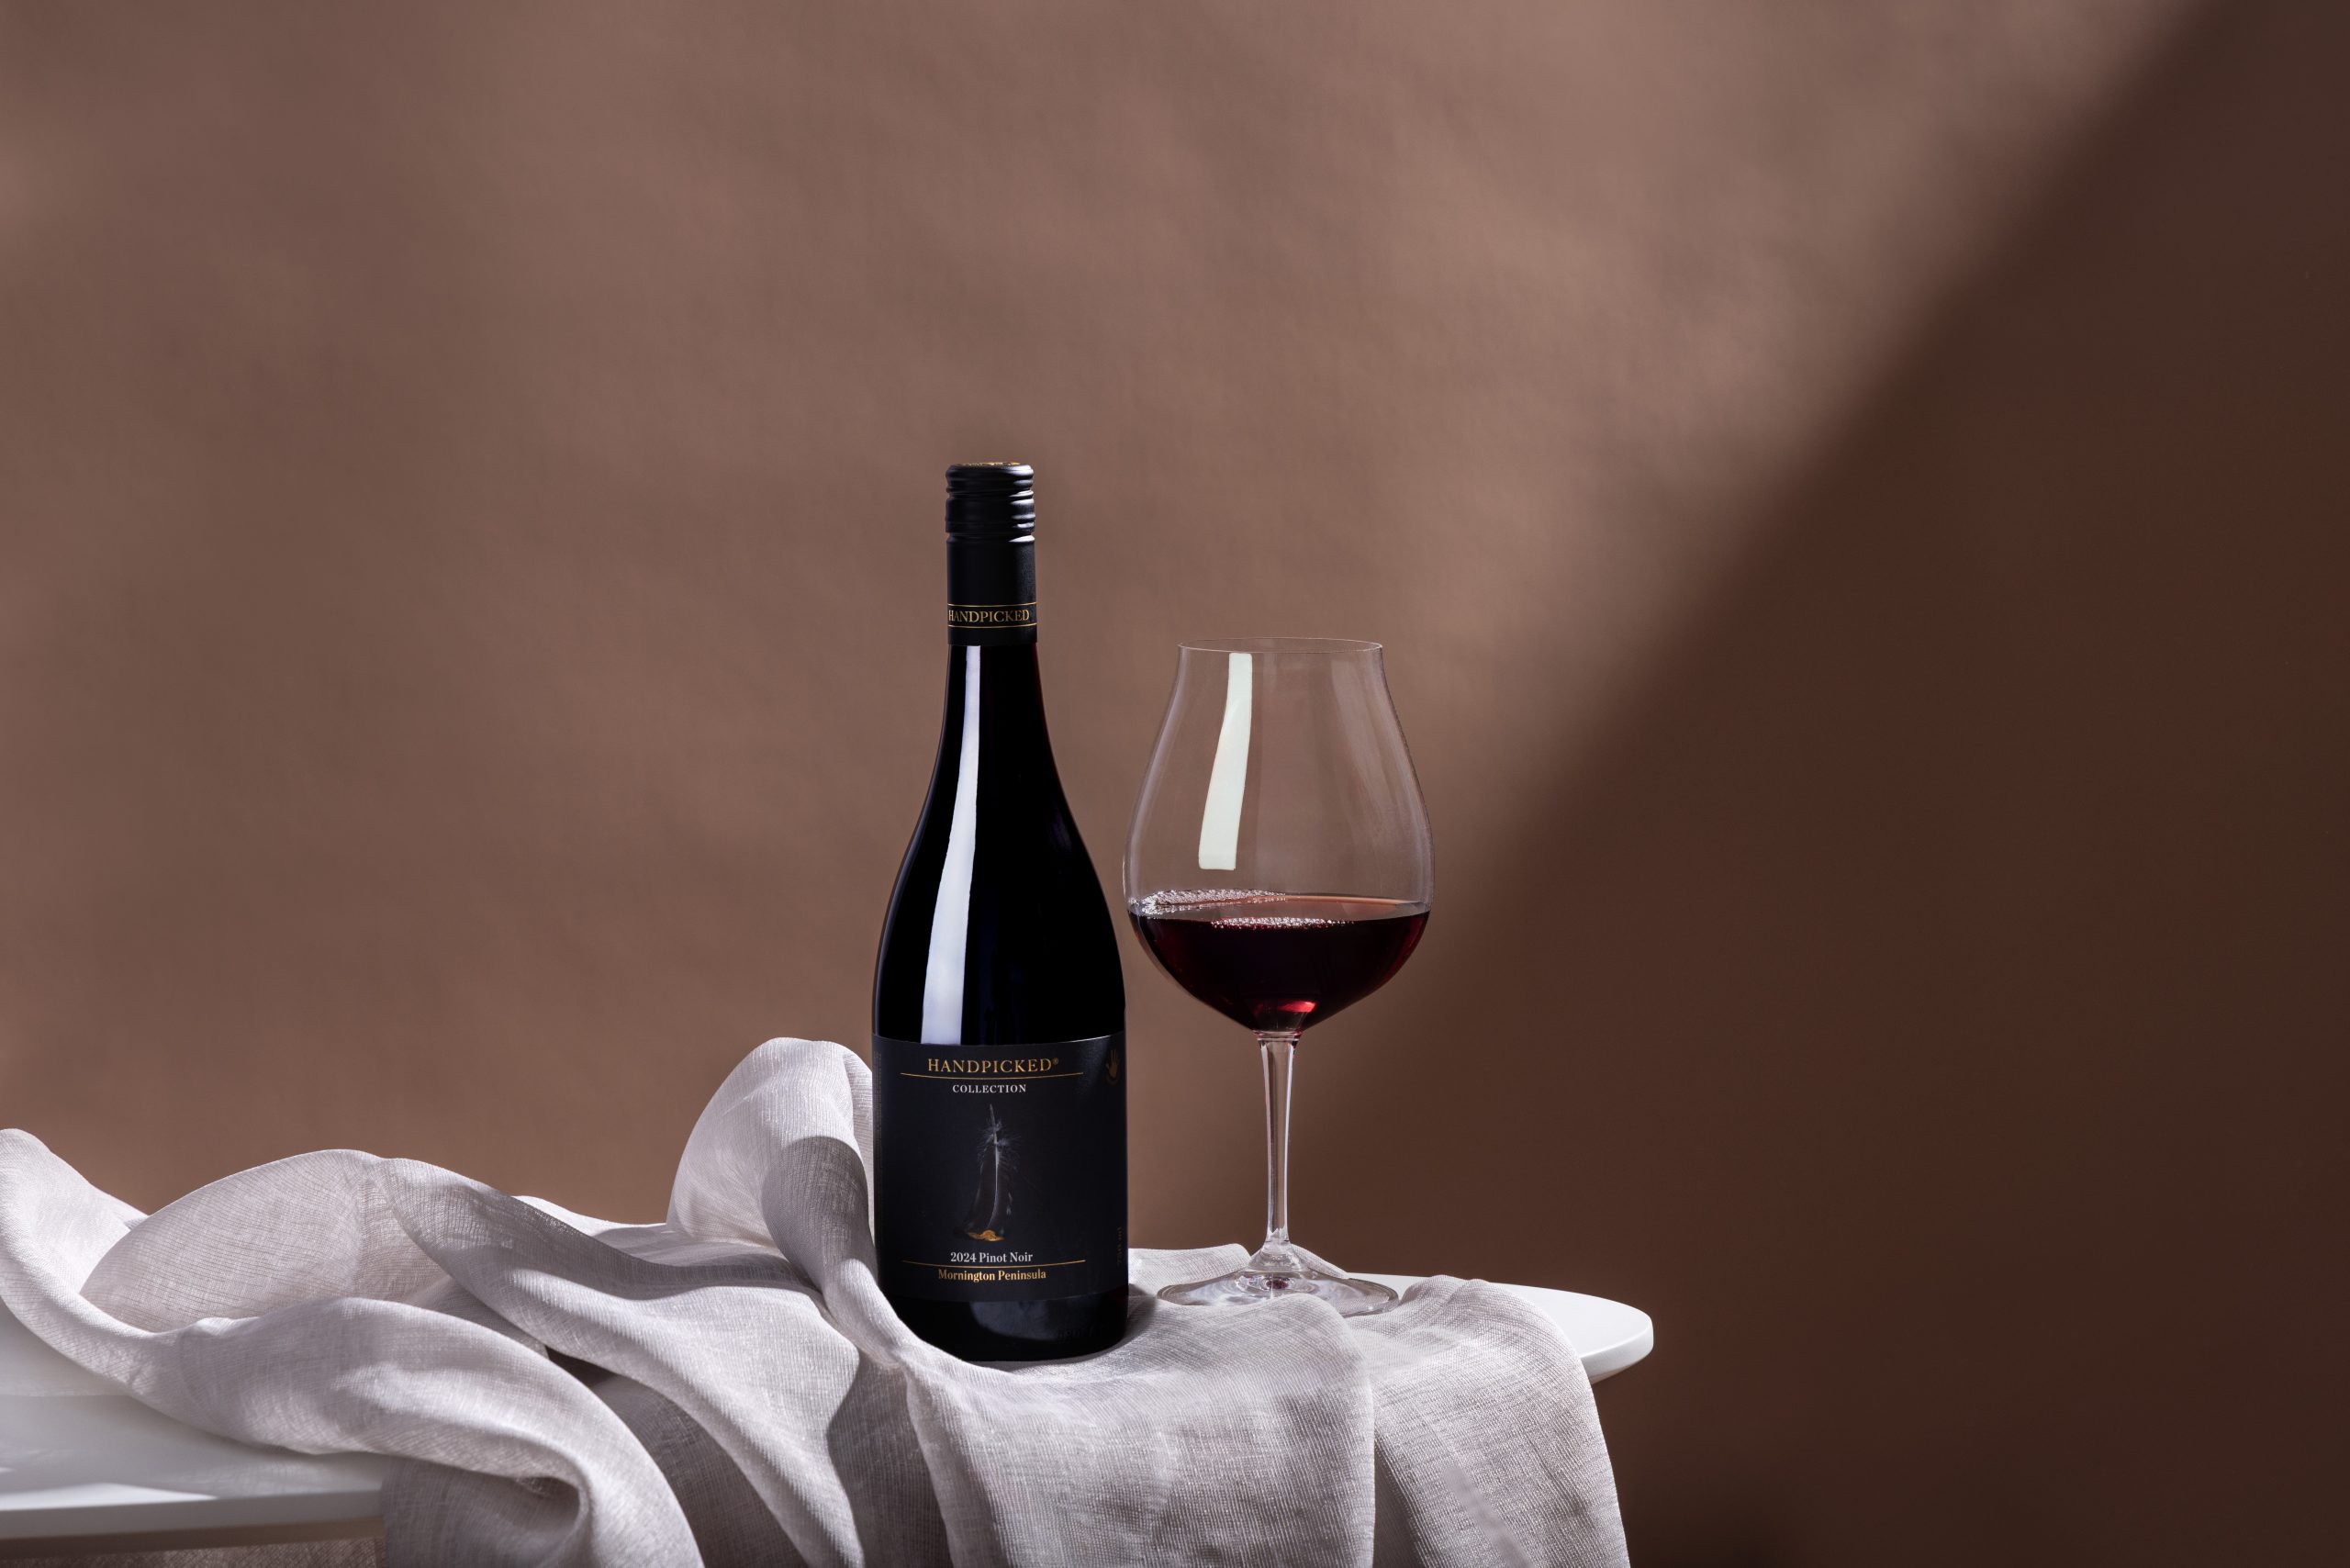
As the season turns, Handpicked Wines’ latest Pinot Noir and Chardonnay releases reveal how subtle shifts in place shape what ends up in the glass.

ABC Bullion has launched a pioneering investment product that allows Australians to draw regular cashflow from their precious metal holdings.