

Former Wells Fargo Advisors Sue the Company Over Cross-Selling

 3 min
Two former Wells Fargo advisors are suing the firm for breach of contract, unfair business practices, and retaliation after they say they resisted pressure from their supervisors to secretly transfer sensitive client information from the advisor and brokerage side of the company to the private bank.
The advisors, Karen Keusayan and Richard Green, are also alleging that Wells Fargo improperly withheld deferred compensation after they resigned in 2021 and joined Morgan Stanley , where they are still registered.
In their complaint, filed in Los Angeles County Superior Court, the advisors describe themselves as high-producing employees who were loyal to the company even through the “nightmarish” years of 2015 to 2017, when Wells Fargo’s banking division was “publicly scorned” for the fake account scandal.
“This is not the ‘sour grapes’ case of a disgruntled employee(s) who sought a promotion and did not get one,” the advisors say in their complaint. “Neither Ms. Keusayan nor Mr. Green ever wanted to leave Wells Fargo. The goal for each had always been to retire at Wells Fargo.”
Wells Fargo declined to comment on the lawsuit.
The two advisors joined forces in 2015 to form a “production partnership,” according to the complaint, which says they grew their book of business to more than $1 billion by 2020.
In 2018, Wells Fargo introduced a new element to its advisor compensation plan, according to the complaint. Advisors were expected to complete forms called client discovery reviews, or CDRs, detailing information about advisory clients. The plaintiffs say they were directed by a compliance officer to keep the forms secret from the clients themselves.
Instead, the CDRs were intended for Wells Fargo’s private bank, “not the broker-dealer/financial services side where plaintiffs worked,” according to the complaint.
They contend that advisors were pressured to work with clients to complete CDRs, which would be secretly shared with Wells Fargo private bankers who could use them as sales leads.
Before submitting the forms to count toward a quota that resulted in additional compensation, the advisors had to check three boxes stating that they had discussed the information with the client, that the information was accurate, and that they had offered the client an opportunity to obtain a copy of the document. On that last item, the plaintiffs allege that Wells Fargo essentially instructed the advisors to lie, explaining that the document didn’t belong to the advisors, but the bank, even though the information came from their own clients.
“[H]igh-ranking compliance personnel at Wells Fargo Advisors repeatedly told plaintiffs to never deliver or present the CDR to the client since, as it was explained by compliance, the CDR was a bank document,” the complaint states. “Worse, plaintiffs were told not to inform the client that a CDR had been prepared.”
The plaintiffs say that these “dishonest instructions” put them in an “impossible position” and that they soon began raising concerns with their superiors. But each time they spoke out, they were told by their supervisors to continue submitting the forms as a requisite part of the company’s compensation plan.
The complaint describes the advisors’ growing unease with being pressured to falsify the CDR submission document, as well as concerns over the personal privacy of their clients, whose information was allegedly being shared internally without their knowledge or permission.
The advisors say that their bosses undertook a retaliatory campaign against them for continuing to raise objections to the CDR program, “including by failing to provide the banking support that plaintiffs and their clients had come to expect as a benefit of being associated with a large, full-service, retail bank,” according to the complaint.
They also say that the advisors felt their jobs were at risk, offering examples of a hostile or coercive work environment. “Mr. Green was berated by a yelling supervisor in front of fellow employees, and Ms. Keusayan was informed that the bank would not issue a routine credit card to her sister (a customer) if a CDR was not on file,” according to the complaint.
The advisors say the deteriorating work environment ultimately led them to resign around July 2021, after which they were informed that they were ineligible for large sums of deferred compensation—$662,000 for Keusayan and nearly $814,000 for Green.
The advisors are seeking to recoup the deferred comp they say they are owed, and are asking the court for additional damages, as well as an injunction barring Wells Fargo from engaging in the conduct alleged in the complaint, among other relief.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”
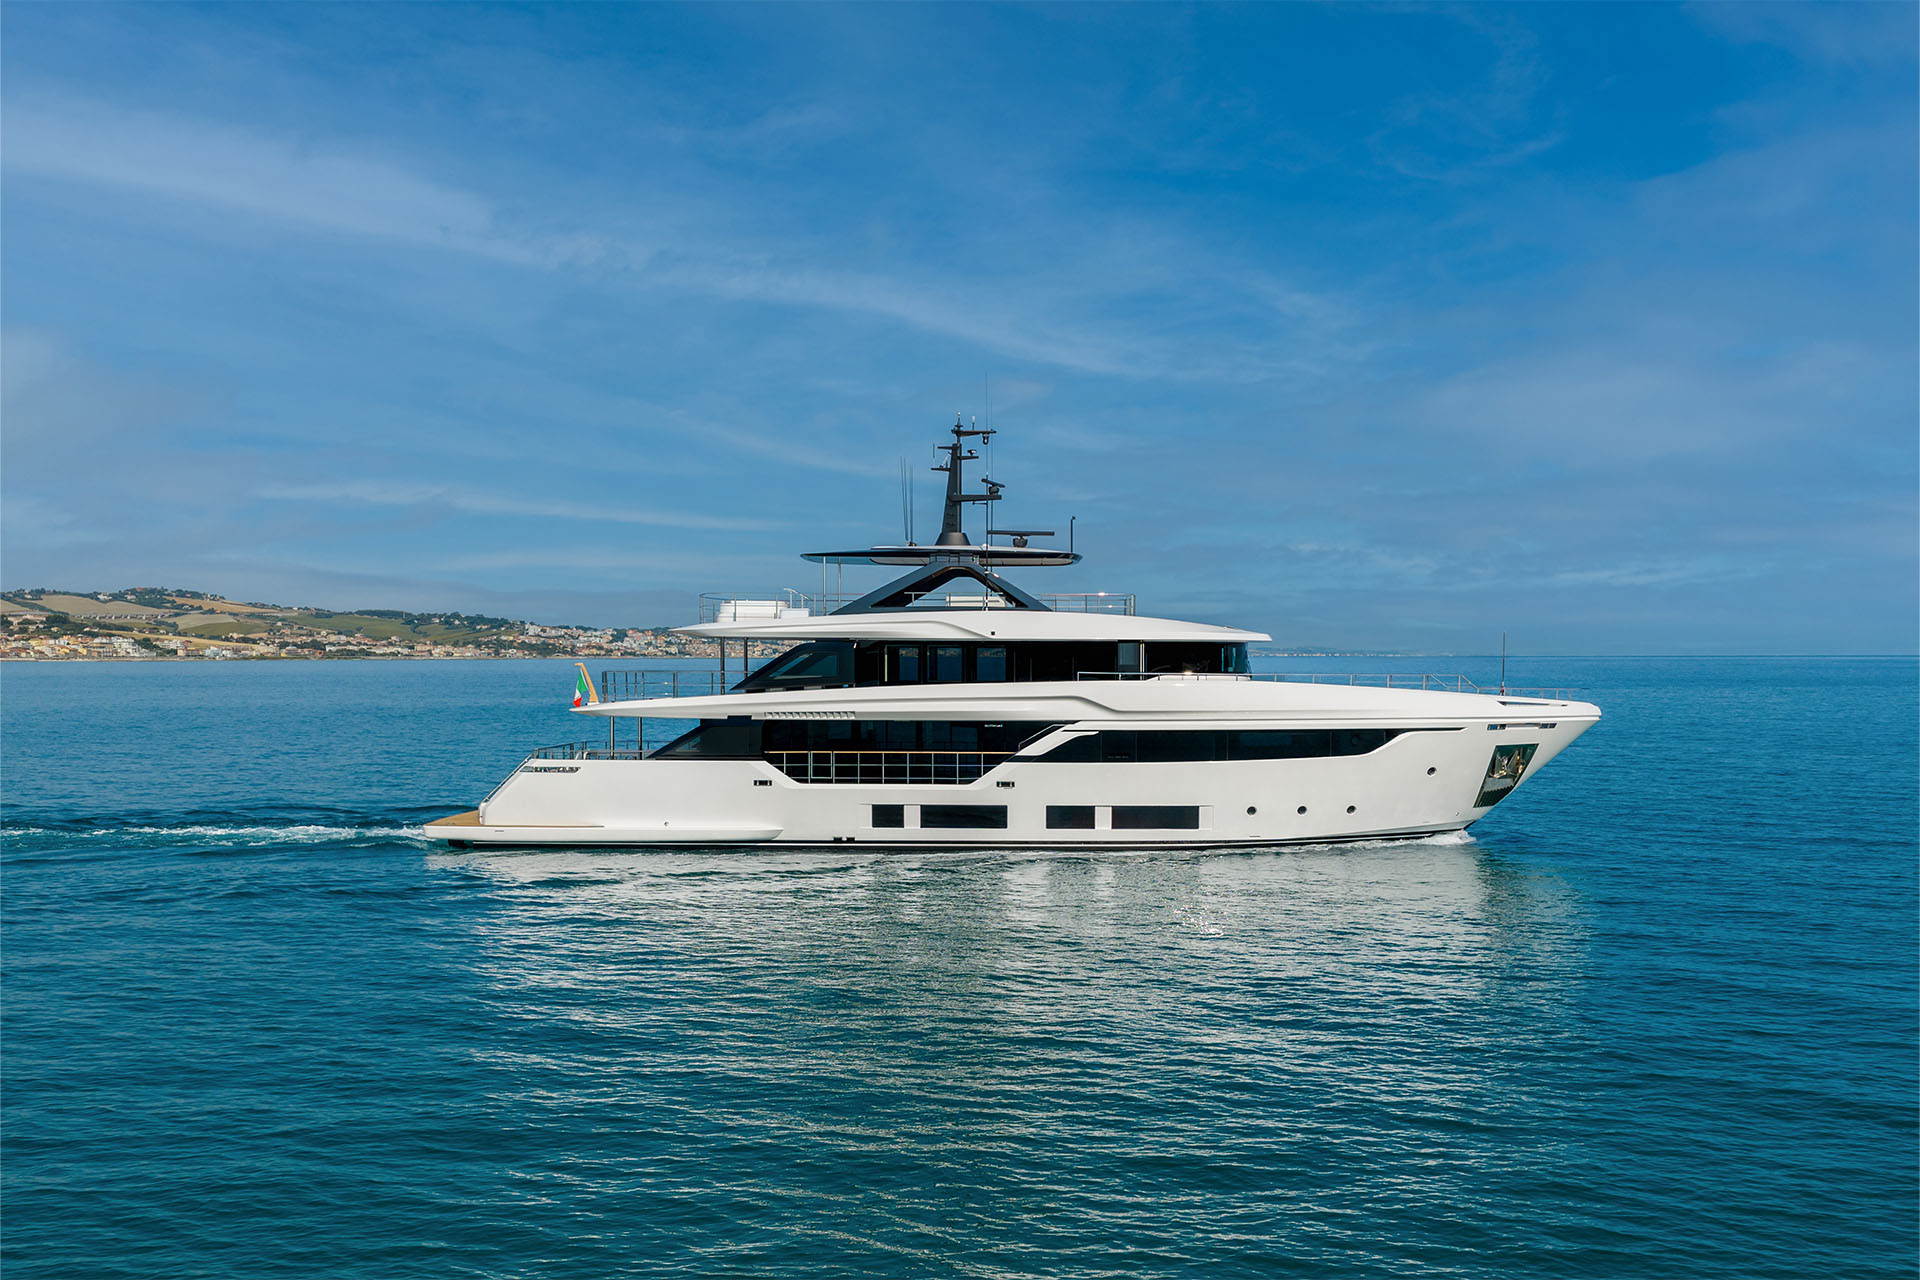
Four decks, 34.5 metres and a made-to-measure interior: step aboard the new Custom Line Navetta 35, unveiled at Cannes.
The ASX 200 rose about 0.27% as energy and materials advanced. Woodside and gold miners gained while financials and technology weakened.
2 min
The Australian sharemarket rebounded from its lowest close in three months on Wednesday, with energy and materials companies leading a cautious recovery.
The S&P/ASX 200 finished approximately 23 points, or 0.27 per cent, higher at 8,695.6 on 16 September. A second data source placed the closing index at 8,696.5, up 24 points or 0.28 per cent. The official close should be confirmed through a licensed feed before publication.
The broader All Ordinaries added 25.2 points, or 0.28 per cent, to 8,874.5.
Energy was the strongest sector, rising 2.19 per cent as Australian producers reflected the previous overnight increase in global oil prices. Woodside gained 2.84 per cent. Brent had settled near US$108.75 a barrel before the local session, although it later traded around US$107.68.
Materials advanced 1.28 per cent and provided the largest positive contribution to the index. Gold producers featured prominently among the strongest stocks, with Pantoro rising 9.3 per cent and St Barbara gaining 8.18 per cent. BCI Minerals added 7.48 per cent.
Financials fell 0.37 per cent, detracting from the benchmark despite earlier strength. Rate expectations remained a significant influence after Westpac joined the other major banks in forecasting a possible Reserve Bank increase in November. Higher rates can expand bank margins in some circumstances but also raise funding costs and increase the risk of loan stress and slower credit growth.
Technology remained weak. Life360 declined 5.46 per cent, while healthcare names that had rallied during Tuesday’s sell-off gave back ground. 4DMedical lost 5.35 per cent and Telix Pharmaceuticals fell 4.96 per cent.
James Hardie dropped 5.23 per cent. Codan moved against the weaker technology tone, gaining 7.51 per cent.
The session produced positive breadth, with more advancers than decliners among the largest 250 stocks, but the broader backdrop remains unsettled. Oil prices have revived inflation concerns, bond yields are elevated and investors are assessing the prospect of further monetary tightening in Australia and the United States.
The rebound therefore recovered only part of Tuesday’s 0.9 per cent decline. For Thursday, investors will be watching overnight central-bank developments, energy markets and whether gains can broaden beyond resources.
Market dashboard — 16 September 2026
S&P/ASX 200* Approximately 8,695.6, up 23.1 points or 0.27 per cent; verify the official closing print
All Ordinaries: 8,874.5, up 25.2 points or 0.28 per cent
Best-performing sector: Energy, up 2.19 per cent
Materials: Up 1.28 per cent
Weak sector: Financials, down 0.37 per cent
Leading mover: Pantoro, up 9.30 per cent
Notable large-cap mover: Woodside, up 2.84 per cent
Notable loser: Sunrise Energy Metals, down 6.22 per cent
Life360: Down 5.46 per cent
Australian dollar: About US71.3 cents in the preceding market snapshot
Gold: Approximately US$4,375 an ounce in the afternoon snapshot
Brent crude: Approximately US$107.68 a barrel in the afternoon snapshot

Travellers are swapping traditional sightseeing for immersive experiences, with Africa emerging as a must-visit destination.

Wealthy Aussies are swapping large family homes for high-end apartments, with sales of prestige units tripling over the past decade.