THE BUSINESS OF BEING OSCAR PIASTRI
Formula 1 may be the world’s most glamorous sport, but for Oscar Piastri, it’s also one of the most lucrative. At just 24, Australia’s highest-paid athlete is earning more than US$40 million a year.
 3 min

In the high-octane world of international sport, homegrown Formula 1 star Oscar Piastri is big business. After a trailblazing 2025 season, Piastri is on track to be one of our most successful athletes ever. Almost certainly, he’ll be the richest.
The 24-year-old Melbourne-born driver inked a lucrative deal with McLaren reportedly worth US$41 million a year, making him Australia’s highest-paid athlete. Not bad for a Brighton boy who left home at 14.
Driving all the way to the bank
When Piastri lines up on the F1 grid at Melbourne’s Albert Park this year, the world’s eyes will be on him as he attempts to achieve what no other Australian driver has by winning the Australian Grand Prix. Football might have the most fans (an estimated 3.5 billion), but F1 still commands around 430 million devoted followers.
According to F1 owner, US giant Liberty Media, the motorsport generated a whopping US$3.65 billion in 2024. While some of that revenue comes from ticket sales, media rights account for roughly a third of the pie. These include broadcasting deals with television networks that know the adrenaline-charged drama of F1 racing translates into ratings-winning viewing.
Adding to the fascination is the Netflix docuseries “Formula 1: Drive to Survive,” which tracks the lives of drivers, managers, and team owners both on and off the circuit. The big screen joined the party in 2025 with F1: The Movie, starring Brad Pitt as an ageing driver attempting a comeback, which proved a hit with cinemagoers, grossing US$624 million (A$946 million) worldwide.
Much like Grand Slam tennis, which counts Rolex and Emirates among its sponsors, F1 attracts prestigious brands such as Louis Vuitton, Moët & Chandon and TAG Heuer. It’s no surprise F1 drivers can command enviable salaries.
At the end of Piastri’s second season with McLaren, in 2024, the Aussie is reported to have pocketed US$34.5 million, including a base pay of US$7.8 million plus US$26.7 million in bonuses. His current deal with McLaren will see him in the team’s famous papaya orange colours until at least 2028.
Piastri also benefits from team sponsors such as Mastercard, as well as personal deals with companies including Quad Lock, software group Dubber, burger chain Grill’d and his father Chris Piastri’s automotive software company HP Tuners.
Piastri is undoubtedly a champion in a cut-throat sport where split-second decision-making at more than 300 km/h can mean the difference between a chequered flag and crashing out. But it’s his future marketability and brand potential where the young driver could outshine his rivals.
It may not, however, be as simple as saying more wins equal more money, according to Hans Westerbeek, Professor of International Sport Business at Victoria University.
“In modern F1, the financial equation is far more complex,” Westerbeek says. “A driver’s value to a team and to sponsors isn’t just measured by podium finishes. It’s about their ability to generate global attention, connect with fans, and represent the brand values of their team and sponsors.”
In the age of “algorithmic fandom”, Westerbeek says digital engagement through social media matters just as much.
“A spectacular overtake that goes viral on TikTok may deliver more commercial value than a quiet second place,” he argues. “Teams and sponsors now monitor real-time sentiment data on how fans react online to every race weekend, and this affects negotiations and commercial deals.
“So, Oscar’s growth in earning potential depends on a combination of performance and digital visibility.”
When Piastri crashed out in the Azerbaijan Grand Prix in September, he was understandably deflated, telling Sky Sports F1 the race was “not my finest moment”. And yet Piastri’s first-lap exit drew most of the headlines, not rival Max Verstappen’s win.
“In many ways, F1 drivers are no longer just athletes; they’re content creators,” Westerbeek says. “An unexpected post-race interview that resonates globally might drive as much sponsor interest as a podium finish.
“The sport’s economics are shifting from pure sporting results to a hybrid model of performance plus digital storytelling.”
Read the full story here.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
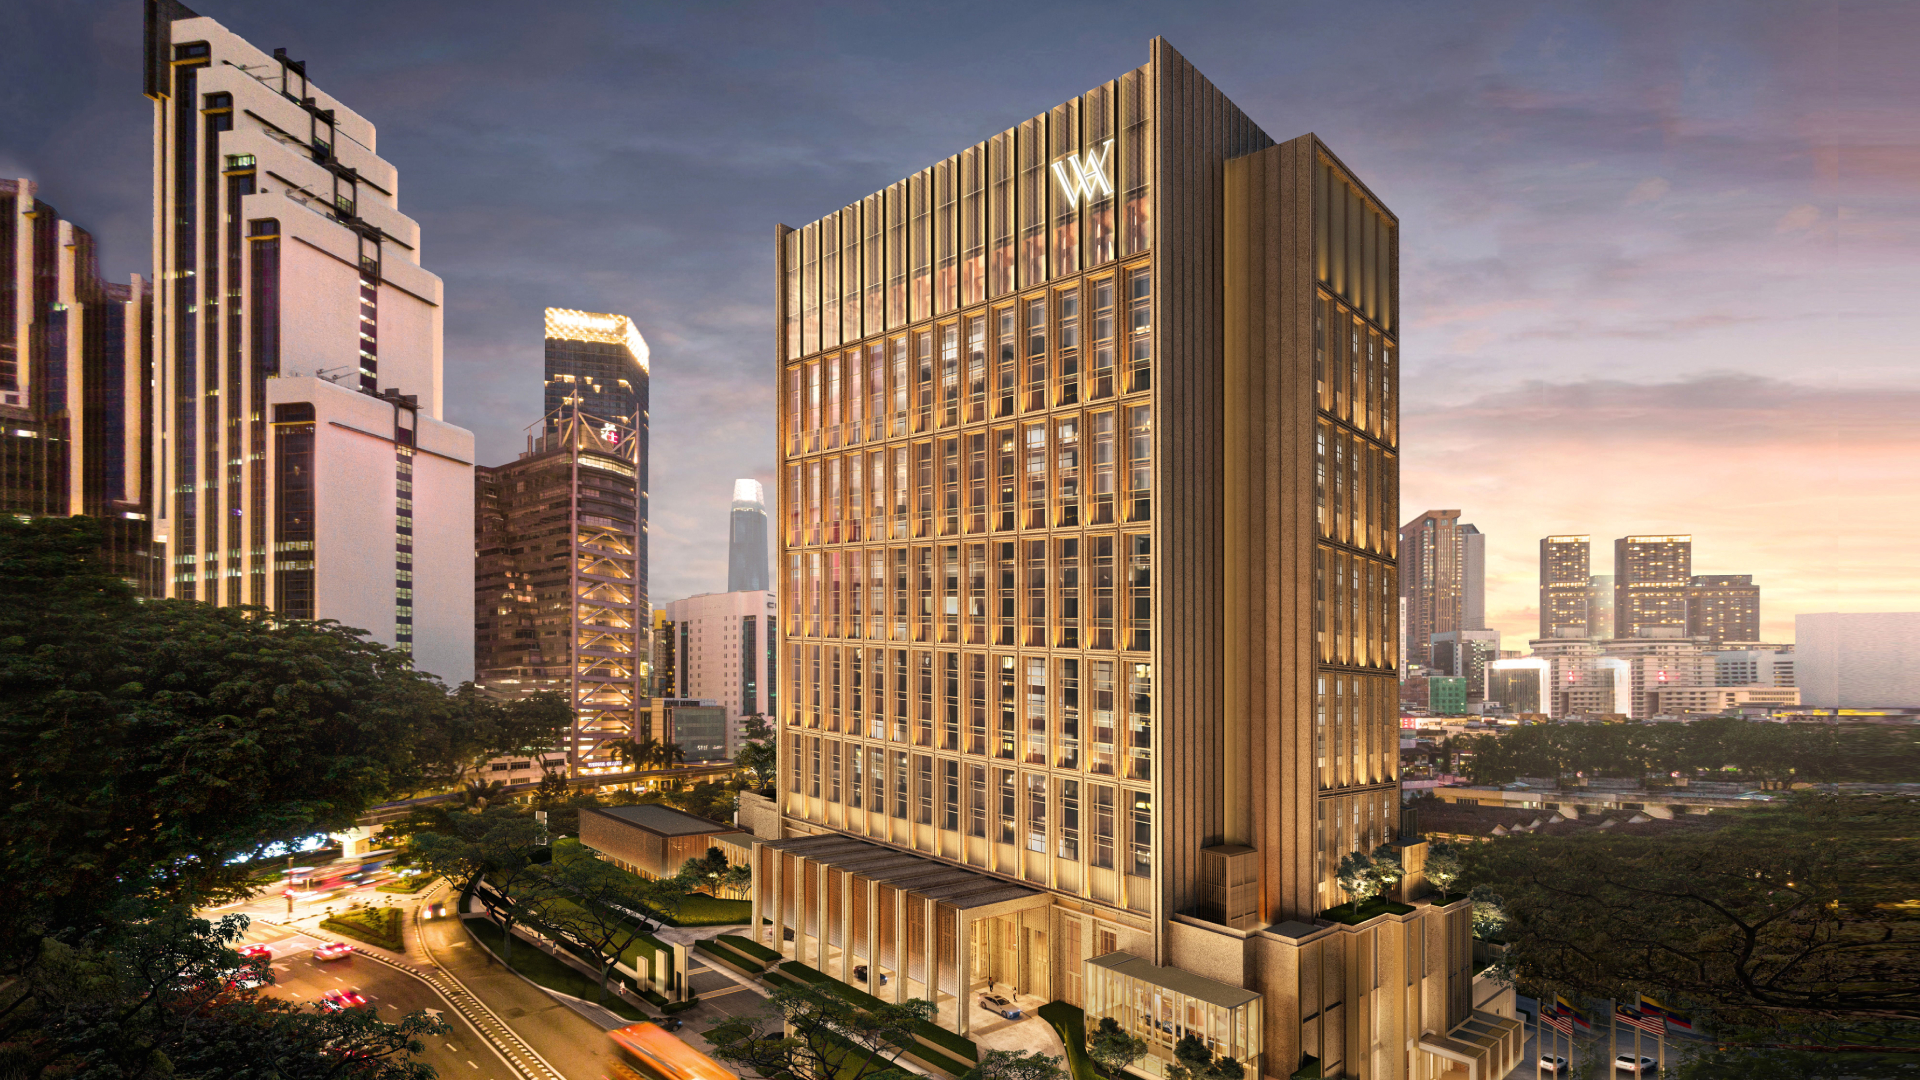
Waldorf Astoria Kuala Lumpur is scheduled to open on 30 October, introducing the Hilton luxury brand to Malaysia with an all-suite hotel in the city’s Golden Triangle.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.
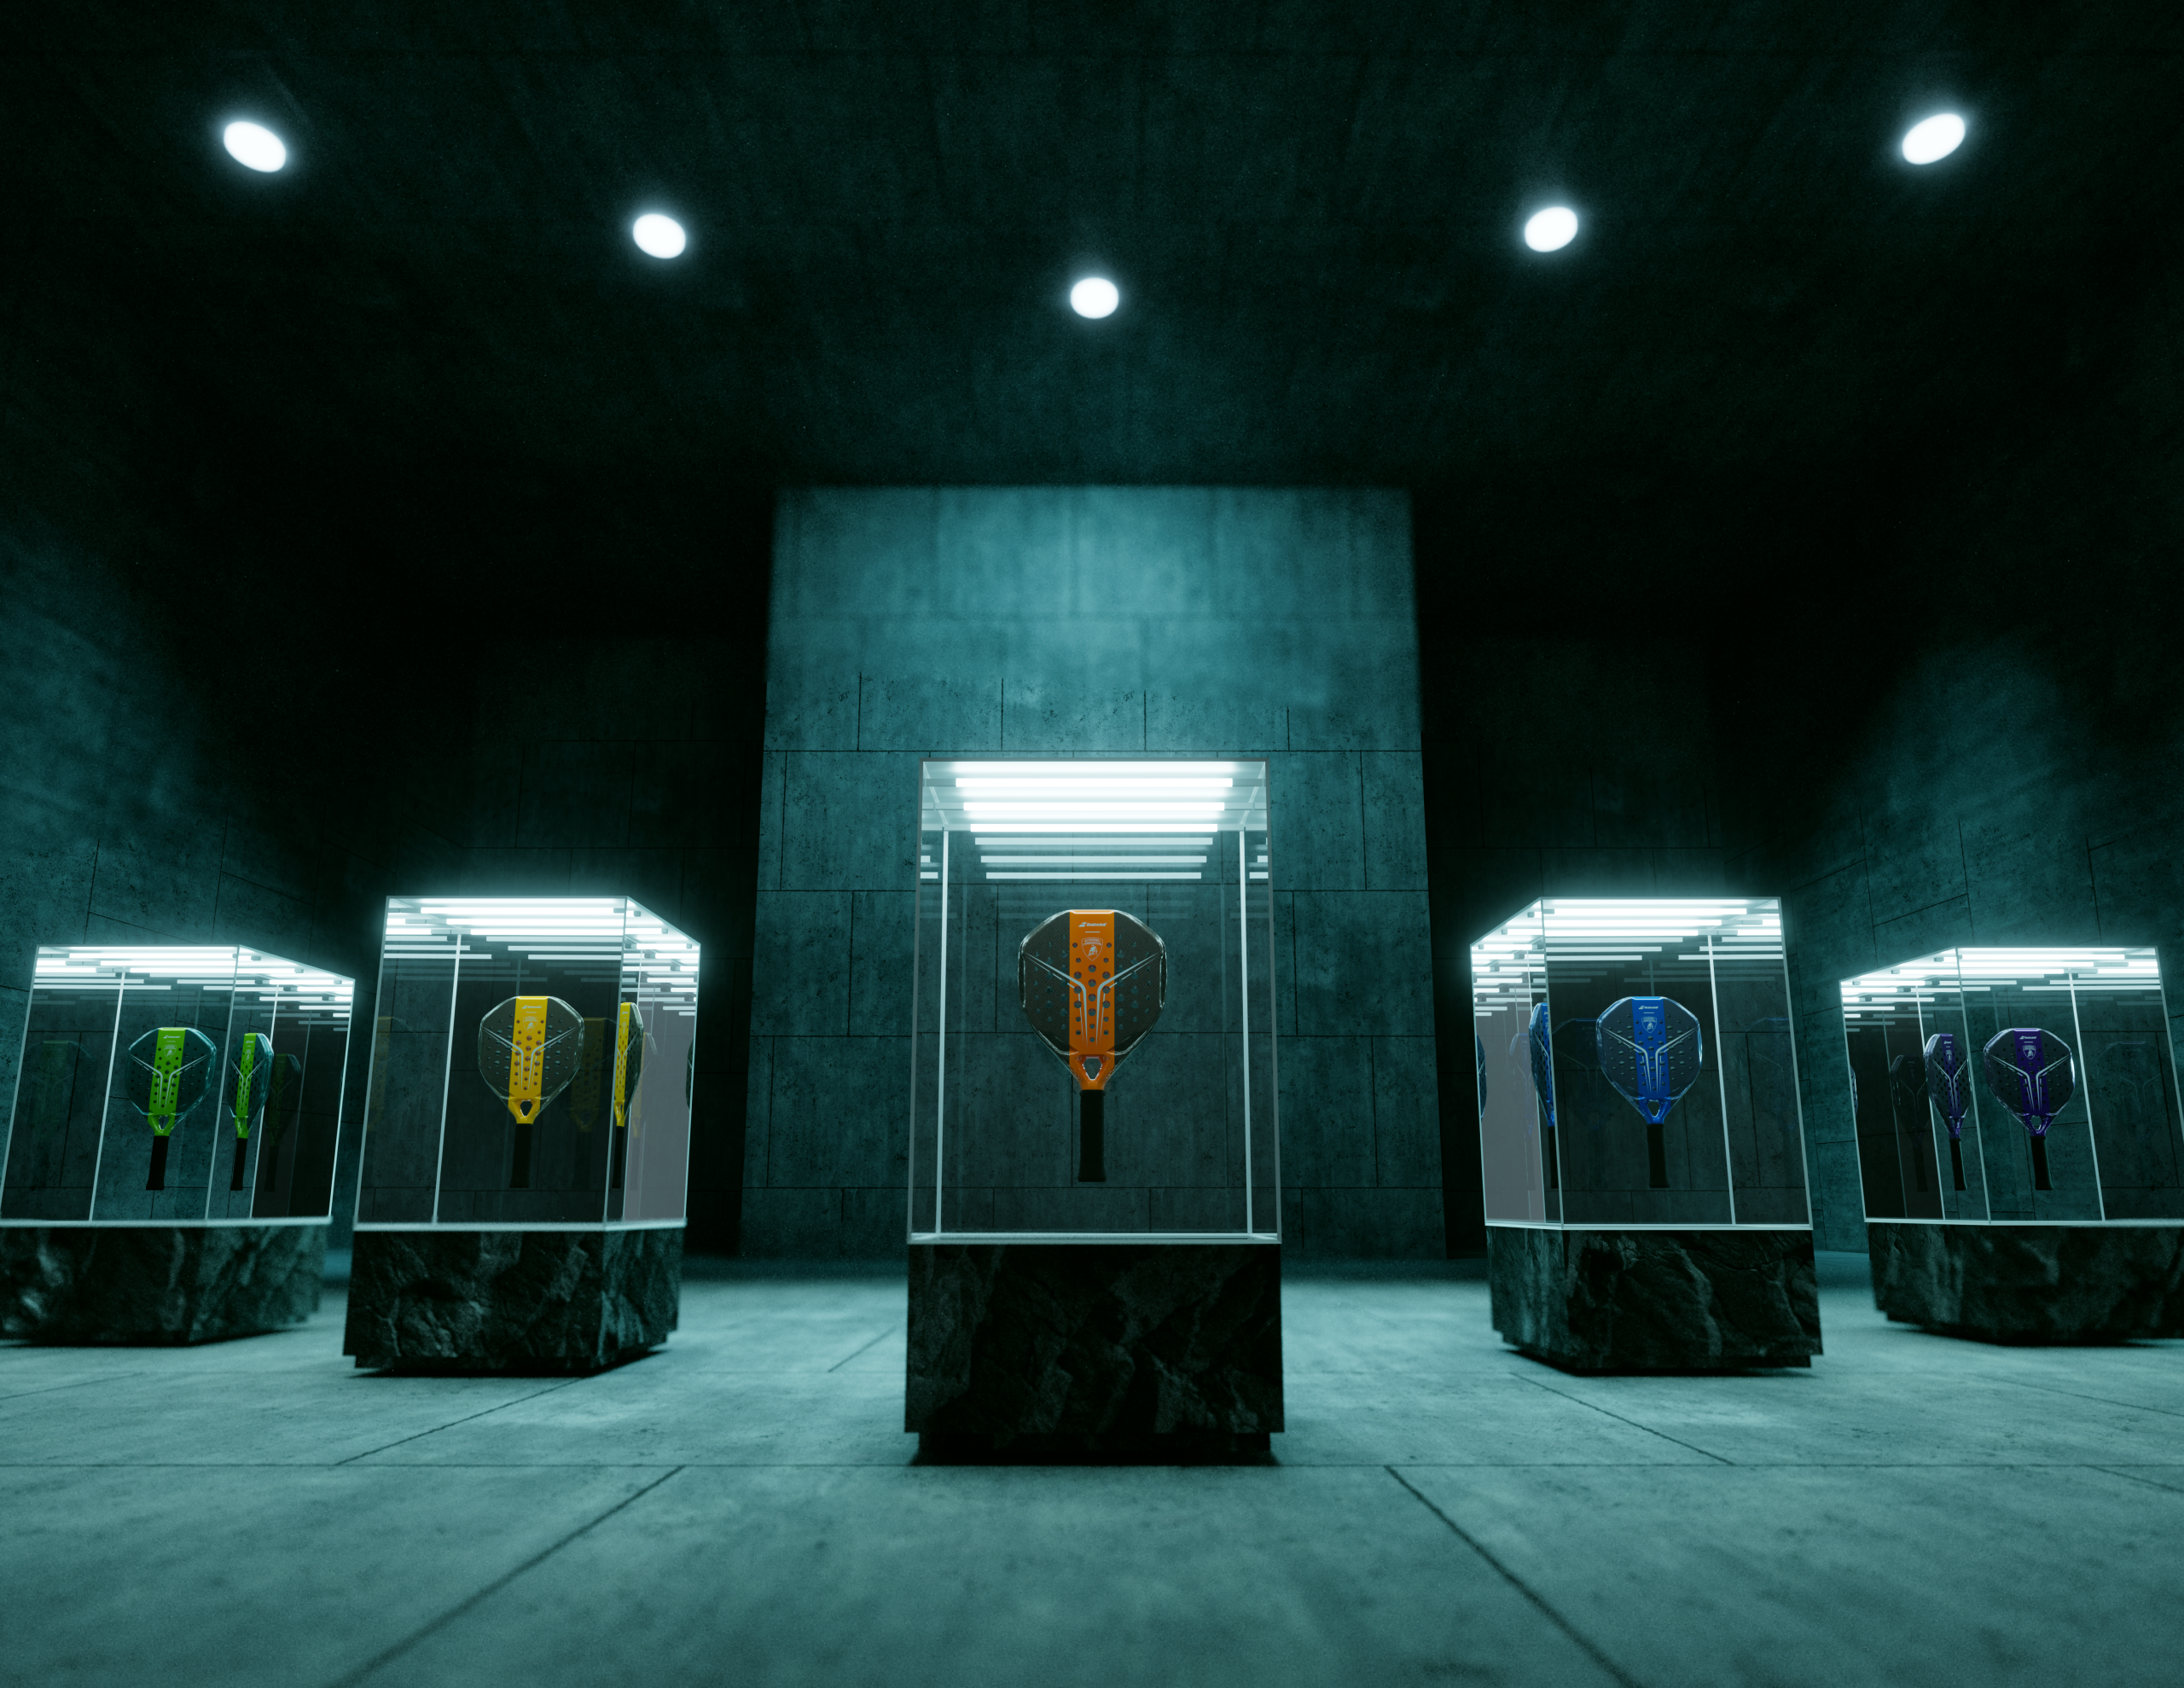
Automobili Lamborghini and Babolat have expanded their collaboration with five new colourways for the ultra-exclusive BL.001 racket, limited to just 50 pieces worldwide.