

The AI Boom Is Coming for Apple’s Profit Margins
Parts for iPhones to cost more owing to surging demand from AI companies.

 4 min

Apple has dominated the electronics supply chain for years. No more.
Artificial-intelligence companies are writing huge checks for chips, memory, specialised glass fibre and more, and they have begun to out-duel Apple in the race to secure components.
Suppliers accustomed to catering to Apple’s every whim are gaining the leverage to demand that the iPhone maker pay more.
Apple’s normally generous profit margins will face pressure this year, analysts say, and consumers could eventually feel the hit.
Chief Executive Tim Cook mentioned the problem in a Thursday earnings call, saying Apple was seeing constraints in its chip supplies and that memory prices were increasing significantly.
Those comments appeared to weigh on Apple shares, which traded flat despite blowout iPhone sales and record company profit.
“Apple is getting squeezed for sure,” said Sravan Kundojjala, who analyses the industry for research firm SemiAnalysis.
AI chip leader Nvidia recently became the largest customer of Taiwan Semiconductor Manufacturing , or TSMC, Nvidia Chief Executive Jensen Huang said on a podcast.
Apple had been TSMC’s biggest customer by a wide margin for years. TSMC is the world’s leading manufacturer of advanced chips for AI servers, smartphones and other computing devices.
Spokesmen for Apple and TSMC declined to comment.
The big computers that handle AI tasks don’t look like the smartphones consumers own, but many companies supply components for both. In particular, memory chips are in short supply as companies such as OpenAI, Alphabet’s Google, Meta , Microsoft and others collectively spend hundreds of billions of dollars to build AI computing capacity.
“The rate of increase in the price of memory is unprecedented,” said Mike Howard , an analyst for research firm TechInsights.
That applies both to the flash memory chips that store photos and videos, called NAND, as well as the memory used to run apps quickly, called DRAM.
By the end of this year, the price of DRAM will quadruple from 2023 levels, and NAND will more than triple, estimates TechInsights.
Howard estimates that Apple could pay $57 more for the two types of memory that go into the base-model iPhone 18 due this fall compared with the base model iPhone 17 currently on sale. For a device that retails for $799, that would be a big hit to profit margins.
Apple’s purchasing power and expertise in designing advanced electronics long made it an unrivaled Goliath among the Asian companies that make most of the iPhone’s parts and assemble the device.
Apple spends billions of dollars a year on NAND, for instance, according to people familiar with the figures, likely making it the single biggest buyer globally. Suppliers flocked to win Apple’s business, hoping to leverage its know-how and prestige to attract other customers.
These days, however, “the companies now pushing the boundaries of human‑scale engineering are the ones like Nvidia,” said Ming-chi Kuo, an analyst with TF International Securities.
Demand for AI hardware is poised to keep growing rapidly. Apple’s spending growth is modest in comparison with what is being spent to fill up AI data centers, even though it is breaking records with huge sales of the iPhone 17.
Samsung Electronics and SK Hynix are raising the price of a type of DRAM chip for Apple, according to people familiar with Apple’s supply chain.
Big AI companies pay generously and are willing to lock in supply and make upfront payments, giving the South Korean chip makers leverage against the iPhone maker.
Apple signs long-term contracts for memory, but it has used its heft to squeeze suppliers.
Its contracts have empowered it to negotiate prices as often as weekly, and to even refuse to buy any memory from a supplier if Apple didn’t view the price as favorable, according to people familiar with its memory purchases.
To boost leverage with suppliers, Apple even began stocking more inventory of memory. That was atypical for Cook, who normally cuts inventory to the bone to maximize Apple’s cash flow.
Apple is fighting not only for current deliveries but also for the attention of engineers at suppliers.
Glass scientists who worked on developing the smoothest and lightest smartphone displays are now also spending time on specialised glass for packaging advanced AI processing chips, according to industry executives.
Makers of sensors and other gizmos inside the iPhone are winning new business from AI companies such as OpenAI that are developing their own hardware.
Still, suppliers said they were far from giving up on business with Apple. Working with Apple is a form of education, they said, because it remains one of the most demanding and disciplined customers in the industry.
TSMC, the Taiwanese chip manufacturer, has built successive generations of its most advanced chips with Apple as its lead customer, relying on the big predictable demand for iPhones.
Now that TSMC is doing more business with Nvidia and other AI companies, people with knowledge of the chip supply chain said Apple was exploring whether some lower-end processors could be made by someone other than TSMC.
One of Apple’s biggest profit-spinners is selling extra memory for far more than the memory chips cost the company.
Last fall Apple discontinued the iPhone Pro model with 128 gigabytes of storage.
Customers who want that model must now start at 256 gigabytes and pay $100 more—the type of move that could be repeated this year to help Apple offset higher costs, wrote Craig Moffett, an analyst at Moffett Nathanson, in an investor note.
However, Apple isn’t expected to raise the price of its next iPhone models over similarly equipped iPhone 17s, said Kuo, the analyst.
News Corp, owner of The Wall Street Journal, has a commercial agreement to supply news through Apple services.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


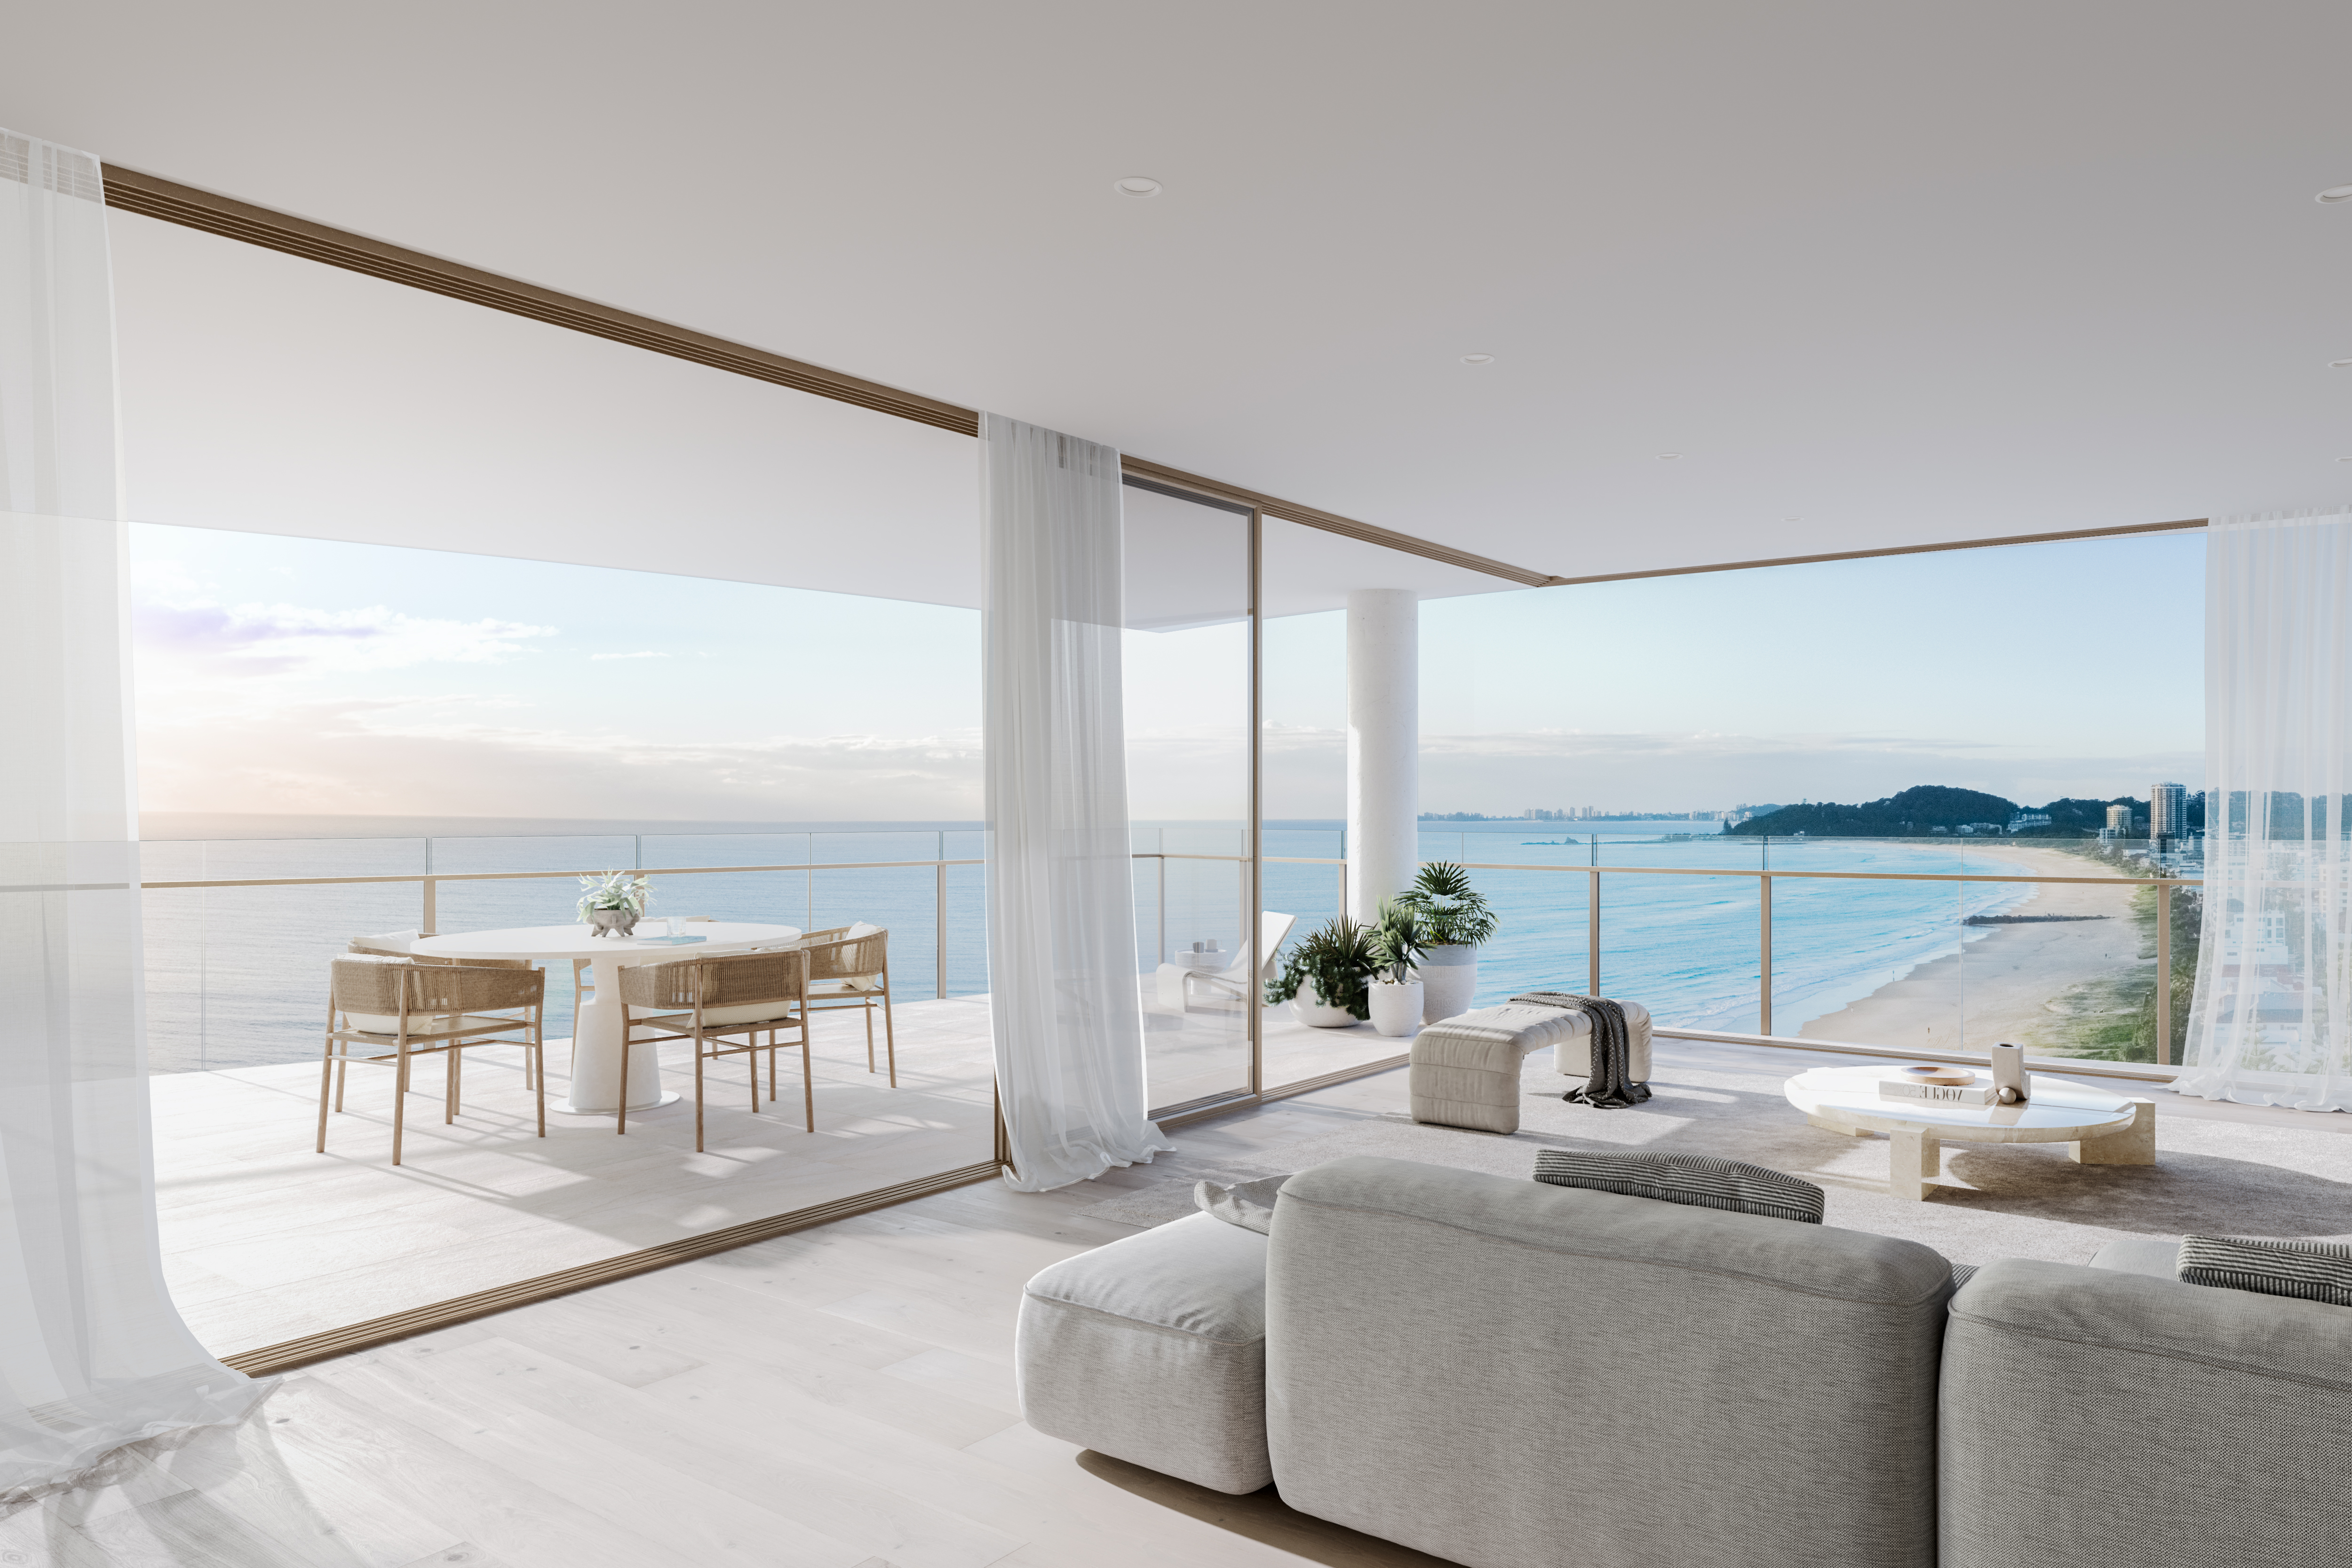
A Sydney couple has paid $15.5 million for the Grand Penthouse at Marquee’s $285 million La Belle Residences beachfront development which is nearing completion at Palm Beach, eclipsing the record for an off-the-plan apartment sale on the southern Gold Coast. The sprawling single level 640 sqm beachfront residence, with sweeping views of the Gold Coast …
Continue reading “$15.5m La Belle Penthouse eclipses southern Gold Coast record”
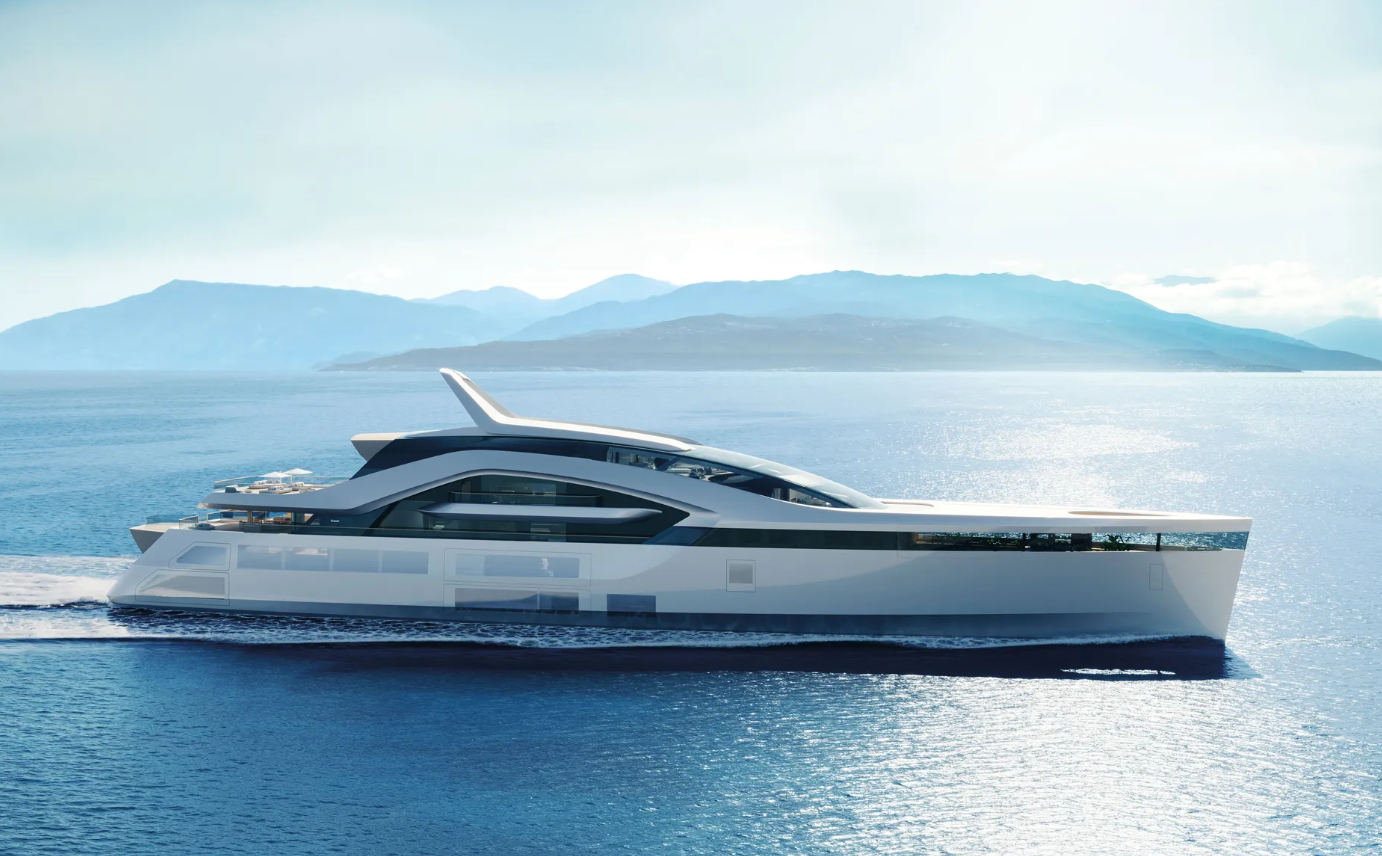
On the owner’s deck, a 20-metre swimming pool incorporates Feadship’s patented ContraWave technology and extends indoors as a suspended, glass-bottomed infinity pool.
The ASX 200 rose 1.28 per cent in the week ending 30 October as miners rallied, consumer stocks fell and rate-rise expectations climbed
6 min
The Australian sharemarket rose during four of five sessions in the week ending 30 October, but the headline gain concealed a sharp divide between recovering miners, rate-sensitive property stocks and retailers hit by inflation and weaker trading updates.
The Australian sharemarket finished October with a positive week, although the route higher was anything but uniform.
The S&P/ASX 200 closed Friday 30 October at 8,908.1, gaining 112.9 points, or 1.28 per cent, from the previous Friday’s close of 8,795.2.
The All Ordinaries advanced 1.34 per cent to 9,025, while the more concentrated S&P/ASX 20 gained 1.11 per cent.
The benchmark rose during four of the week’s five sessions. It added 0.17 per cent on Monday and 0.46 per cent on Tuesday, before slipping 0.03 per cent on Wednesday. It recovered 0.50 per cent on Thursday and gained another 0.18 per cent on Friday.
The index briefly reached 8,933.3 but again failed to establish itself above the psychologically important 9,000-point mark.
The week’s central tension was between a resources recovery and a less forgiving domestic interest-rate outlook.
Materials gained 4.06 per cent, reclaiming part of the previous week’s heavy fall. Australian real estate investment trusts rose 3.77 per cent, financials gained 1.05 per cent and energy advanced 1.39 per cent.
At the other end of the market, consumer staples fell 5.13 per cent and consumer discretionary shares lost 2.35 per cent. Utilities declined 0.73 per cent and communication services eased 0.68 per cent.
Inflation changes the conversation
Australia’s September inflation data was the week’s pivotal domestic release.
Annual inflation of 4.3 per cent pushed market pricing towards another possible Reserve Bank increase and disrupted Wednesday’s early sharemarket rally.
By Thursday’s close, one widely followed market measure placed the probability of an increase in the cash rate to 4.85 per cent at approximately 80 per cent.
That pricing does not make an increase certain. It does, however, change the framework through which investors assess Australian businesses.
Companies dependent on discretionary household spending face renewed pressure on sales and margins. Property trusts, banks, developers and highly leveraged companies must be considered against the prospect of higher funding costs.
Banks present a more complicated equation. Higher rates can support margins, but they may also slow credit growth and increase arrears.
Miners recover
BHP gained 4.56 per cent across the week to close at $57.56, making a substantial contribution to the benchmark’s rise.
The recovery followed an 8.3 per cent fall during the previous week and helped lift the broader materials sector.
Northern Star Resources added 4.59 per cent, while Goodman Group advanced 6.85 per cent to become the strongest performer in the ASX 20.
The commodities picture was mixed. Gold fell approximately 3.12 per cent on the cited weekly measure, while Brent crude added around 0.68 per cent.
The Australian dollar was little changed at approximately US70.35 cents at the reference point.
Supermarkets and consumer shares retreat
The consumer-staples story was markedly weaker.
Coles fell 11.77 per cent after its first-quarter update, making it one of the largest significant-company declines of the week.
Woolworths lost 3.66 per cent and Wesfarmers fell 4.48 per cent to $76.69 as investors processed company trading commentary against the prospect of another squeeze on household demand.
The moves illustrate how quickly expectations can change when an apparently defensive company disappoints.
Supermarkets still benefit from the recurring need for groceries, but customers can trade down, shift between chains and reduce spending on higher-margin discretionary lines.
Wesfarmers carries exposure to several consumer categories through businesses including Bunnings, Kmart and Officeworks. A renewed rate increase would place more pressure on households already confronting higher prices.
The wider market’s biggest movements
Among companies outside the ASX 20, Mesoblast surged 27.32 per cent, SiteMinder gained 22.74 per cent and Zip rose 22.60 per cent.
The sharpest weekly falls included 4DMedical, down 33.51 per cent; Tuas, down 29.95 per cent; Catalyst Metals, down 17.47 per cent; and Champion Iron, down 13.35 per cent.
Those percentages require context.
The movements in BHP, Commonwealth Bank and other very large companies had substantially more influence on the index than similarly dramatic changes among smaller companies.
A 20 per cent move in a relatively small stock may attract more attention than a two per cent rise in a major bank, but the bank can have the greater effect on the market.
How the ASX 20 moved
The following list uses the S&P/ASX 20 constituents and five-session movements reported at the 30 October close.
Where the component feed did not publish a valid five-day comparison, no figure has been estimated.
BHP Group: Up 4.56 per cent
Commonwealth Bank: Up 1.66 per cent
Rio Tinto: Down 2.20 per cent
National Australia Bank: Up 0.48 per cent
Westpac: Up 0.08 per cent
ANZ Group: Up 1.92 per cent
CSL: Up 2.05 per cent
Macquarie Group: Up 2.19 per cent
Wesfarmers: Down 4.48 per cent
Woodside Energy: Up 1.43 per cent
Goodman Group: Up 6.85 per cent
Telstra: Five-day comparison unavailable from the cited component feed
Woolworths: Down 3.66 per cent
Fortescue: Five-day comparison unavailable from the cited component feed
Transurban: Down 2.40 per cent
QBE Insurance: Down 1.21 per cent
Aristocrat Leisure: Up 0.63 per cent
Northern Star Resources: Up 4.59 per cent
Sigma Healthcare: Down 0.36 per cent
Brambles: Down 1.20 per cent
The companies dominating the conversation
Coles was the week’s standout media-facing company for the wrong reason.
Its trading update produced an outsized repricing and drew attention across the grocery and retail sectors. Woolworths and Wesfarmers were also scrutinised as investors considered how stubborn inflation and another possible rate rise could affect sales volumes.
Bank of Queensland offered a more positive corporate signal.
The bank reported that its FY26 net interest margin had risen six basis points to 1.70 per cent, ahead of the 1.68 per cent expected by the market according to contemporaneous reporting.
Bank of Queensland shares rose 5.8 per cent on Thursday, while the major banks also rallied.
Endeavour Group finished Friday at $3.39, up 4.31 per cent on the day, and released the results of its annual general meeting.
The movement was notable during a week in which investors were highly sensitive to consumer-facing companies. The AGM result should not, however, be presented as the sole cause of the share-price increase without further supporting company guidance.
Mesoblast’s 23.4 per cent Thursday rise and 27.32 per cent weekly gain returned the biotechnology company to the centre of market attention.
For editors, it is important to separate the size of that percentage movement from its influence on the index. Mesoblast was an eye-catching performer, but it did not drive the ASX 200 in the way BHP or Commonwealth Bank did.
Qantas remained part of the broader market conversation as investors watched travel demand and company updates.
However, the primary-source review did not locate a fresh Qantas announcement that justified attributing a major weekly market movement to new company information. The airline should therefore remain on the monitoring list rather than being forced into the week’s causal narrative.
Is Australia’s IPO market reopening?
The official ASX new-listings pipeline remains active but selective.
ASX’s upcoming-floats page included formal applications with offer timetables extending through October and at least one anticipated listing on 30 November.
The exchange notes that its page covers companies for which a formal listing application has been received. It does not represent every company privately exploring a float.
The wider debate concerns whether Australia’s public market is sufficiently competitive when high-growth businesses can pursue capital in the United States or remain privately funded for longer.
ASX has previously raised possible reforms designed to improve the attractiveness of the local market. These include debate about reducing minimum free-float requirements and streamlining aspects of the admissions process.
An enhanced fast-track pathway for qualifying applicants can shorten the review process, reducing the execution risk created when market conditions change during a long IPO timetable.
That does not remove the more fundamental challenge.
New floats still require credible earnings or a convincing growth pathway, sensible pricing and enough genuine free float to support trading after listing.
Investors can already obtain diversified exposure through low-cost exchange-traded funds or buy established, liquid businesses. A float must therefore offer more than novelty.
The current pipeline suggests that the IPO window is open, but it is not indiscriminate.
What investors will watch next
The Reserve Bank’s next decision now sits at the centre of the domestic outlook.
Any change in cash-rate expectations will flow rapidly through banks, retailers, property trusts, listed developers and companies carrying substantial debt.
Investors will also watch whether the materials recovery can continue, whether BHP can hold its rebound and whether consumer companies provide further evidence of slowing demand.
Overseas, technology-sector volatility, commodity prices and the United States interest-rate outlook will continue to shape Australian trading.
The week’s 1.28 per cent headline gain was encouraging, but it was not a broad declaration of confidence.
It was a rotation towards miners, selected financials and property securities—and away from consumer businesses facing a more difficult inflation and interest-rate equation.
Market dashboard
S&P/ASX 200: 8,908.1, up 1.28 per cent for the week
All Ordinaries: 9,025, up 1.34 per cent
S&P/ASX 20: 5,214.7, up 1.11 per cent over five sessions
Best sector: Materials, up 4.06 per cent
Next-best sector: A-REITs, up 3.77 per cent
Weakest sector: Consumer staples, down 5.13 per cent
Major large-cap winner: Goodman Group, up 6.85 per cent
Major large-cap loser: Coles, down 11.77 per cent
AUD/USD: Approximately US70.35 cents at the weekly reference point
Gold: Approximately US$3,885 an ounce, down 3.12 per cent on the cited weekly measure
Brent crude: Approximately US$117.70 a barrel, up 0.68 per cent on the cited weekly measure
Parts for iPhones to cost more owing to surging demand from AI companies.

Many of the most-important events have slipped from our collective memories. But their impacts live on.