Why Economies Haven’t Slowed More Since Central Banks Hit the Brakes
Pandemic effects and government aid are blunting impact of higher rates, for now

 5 min
The world’s central banks raced at an extraordinary pace over the past year to cool inflation, but it hasn’t proved enough—yet.
Economic growth remains mostly solid and price pressures strong across affluent countries despite sharply higher interest rates.
Why haven’t growth and inflation slowed more? Much of the explanation lies in the pandemic’s weird effects and the time it takes for central-bank rate increases to curb economic activity. Additionally, historically tight labor markets have fuelled wage gains and consumer spending.

First, the unusual nature of the pandemic-induced 2020 recession and the ensuing recovery blunted the normal impacts of rate hikes. In 2020 and 2021, the U.S. and other governments provided trillions of dollars in financial assistance to households that were also saving money as the pandemic interrupted normal spending patterns. Meanwhile, central banks’ rock-bottom interest rates allowed companies and consumers to lock in low borrowing costs.
Households and businesses continued to spend heavily in recent months. Families tapped their savings, which were replenished by solid income growth. Businesses kept hiring thanks to pandemic-related labour shortages and large profits.
“There are just a lot of embedded pandemic-era forces that are working against this tightening,” Tom Barkin, president of the Federal Reserve Bank of Richmond, told reporters last week.
Two industries traditionally sensitive to interest rates—autos and construction—offer examples.
Pandemic-related shortages of semiconductor chips limited the supply of cars for sale, leading eager buyers to pay higher prices for the vehicles available. Although U.S. construction of single-family homes tumbled last year, construction employment grew over the past 12 months. Fuelling job growth were supply-chain bottlenecks that extended the time needed to finish homes and a record amount of U.S. apartment construction, which takes longer to complete.
U.S. single-family housing construction has rebounded recently thanks to historically low numbers of homes for sale. Many households refinanced during the pandemic and locked in low mortgage rates—a good reason to stay put. “I didn’t fully anticipate how much the move in interest rates would convince people not to put their houses on the market,” Barkin said.


Normally, the Federal Reserve’s rate increases force heavily indebted consumers and businesses to rein in spending because they have to pay more to service their loans. But consumers haven’t overextended themselves with debt over the past two years; household debt service payments accounted for 9.6% of disposable personal income during the first quarter, below the lowest levels recorded between 1980 and the onset of the pandemic in March 2020.
“A lot of the imbalances you might anticipate at this point in the cycle just have not had the time to build up,” said Matthew Luzzetti, chief U.S. economist at Deutsche Bank.
Second, government spending has continued to bolster growth, cushioning economic shocks that proved less catastrophic than expected. While Europe’s energy crisis helped to tip the region into a shallow recession over the winter, the region skirted the deep downturn that some analysts had forecast. European governments pledged up to $850 billion to support spending.
This year falling oil and natural-gas prices have pumped up economic growth by putting money into consumers’ pockets, boosting confidence and easing pressures on government budgets. The price of a barrel of oil has fallen by nearly half in the past year, from around $120 to less than $70—below its level before Russia’s 2022 invasion of Ukraine sent prices soaring.
The reopening of China’s economy supported activity in the country’s many trading partners, while weak domestic growth prompted Beijing this month to provide new stimulus.
In the U.S., fiscal policy has provided more oomph for the economy this year. Federal funding continues to flow from President Biden’s roughly $1 trillion infrastructure package approved in 2021 and two pieces of legislation signed last year that provide hundreds of billions of dollars to boost renewable-energy production and semiconductor manufacturing.
A rock waiting to drop
Third, it takes time for higher interest rates to ripple through the economy and cool growth and inflation. The Bank of England first raised interest rates from near zero in December 2021, while the Fed and the European Central Bank lifted off in March 2022 and July 2022, respectively.
By some estimates, the first two-thirds of the Fed’s rate increases only restored rates to a level that was no longer pushing on the gas pedal, while the last third slowed the economy by pressing the brakes. The upshot is that policy has restricted growth for just eight or nine months, Atlanta Fed President Raphael Bostic wrote in an essay published last week.
Chicago Fed President Austan Goolsbee compared the potential coming impact of the Fed’s 5 percentage points in rate increases to the unseen hazards faced by Wile E. Coyote, the unlucky cartoon character. “If you raise 500 basis points in one year, is there a huge rock that’s just floating overhead…that’s going to drop on us?” he said in a recent interview.
Dario Perkins, managing director at the research firm TS Lombard, said higher rates are slowing growth in ways that aren’t obvious, such as by causing employers to cut unfilled jobs or companies to forgo expansion. “It might appear that monetary policy isn’t working when, in fact, it is,” he wrote in a recent report.
Climbing the last mile
To be sure, some central banks might not have done enough to cool demand. The ECB, for example, increased its key rate to 3.5% this month, but it is still negative when adjusted for inflation—potentially a stimulative level.
Many economists still anticipate a recession over the next six to 18 months, either because of past rate increases or those to come.

Just how much higher to raise rates is hard to judge because of mixed signals about economic activity. In the U.S., hiring has been strong, but average hours worked declined in May and the number of people filing for state unemployment benefits has climbed in recent weeks to its highest levels since late 2021.
Falling energy and grocery prices helped lower U.S. inflation to 4% in May from a four-decade high last summer of around 9%, according to the Labor Department’s consumer-price index. The breadth of price increases has narrowed. In May, less than 50% of all prices in the CPI rose by more than 5%, down from 80% of the index at one point last year.
Central bankers remain anxious, however, because measures of so-called core inflation, which exclude volatile food and energy prices, have declined much less. Those readings tend to better predict future inflation.
Central banks in Norway and the U.K. announced half-point interest-rate increases last week to address persistent inflation. Central banks in Canada and Australia recently resumed rate increases after pausing, pointing to higher service-sector inflation and tight labor markets.
The Switzerland-based Bank for International Settlements, a consortium of central banks, warned in a report released Sunday that reducing inflation to many central banks’ 2% target could be harder than expected.
Easy gains from lower energy- and food-price inflation have been banked. The longer high inflation lasts, the more likely it is that people will adjust their behaviour and reinforce it, the BIS said. In that scenario, central banks might find they need to cause a sharper downturn to force inflation down to their goal.
“The ‘last mile’ may pose the biggest challenge,” the BIS said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
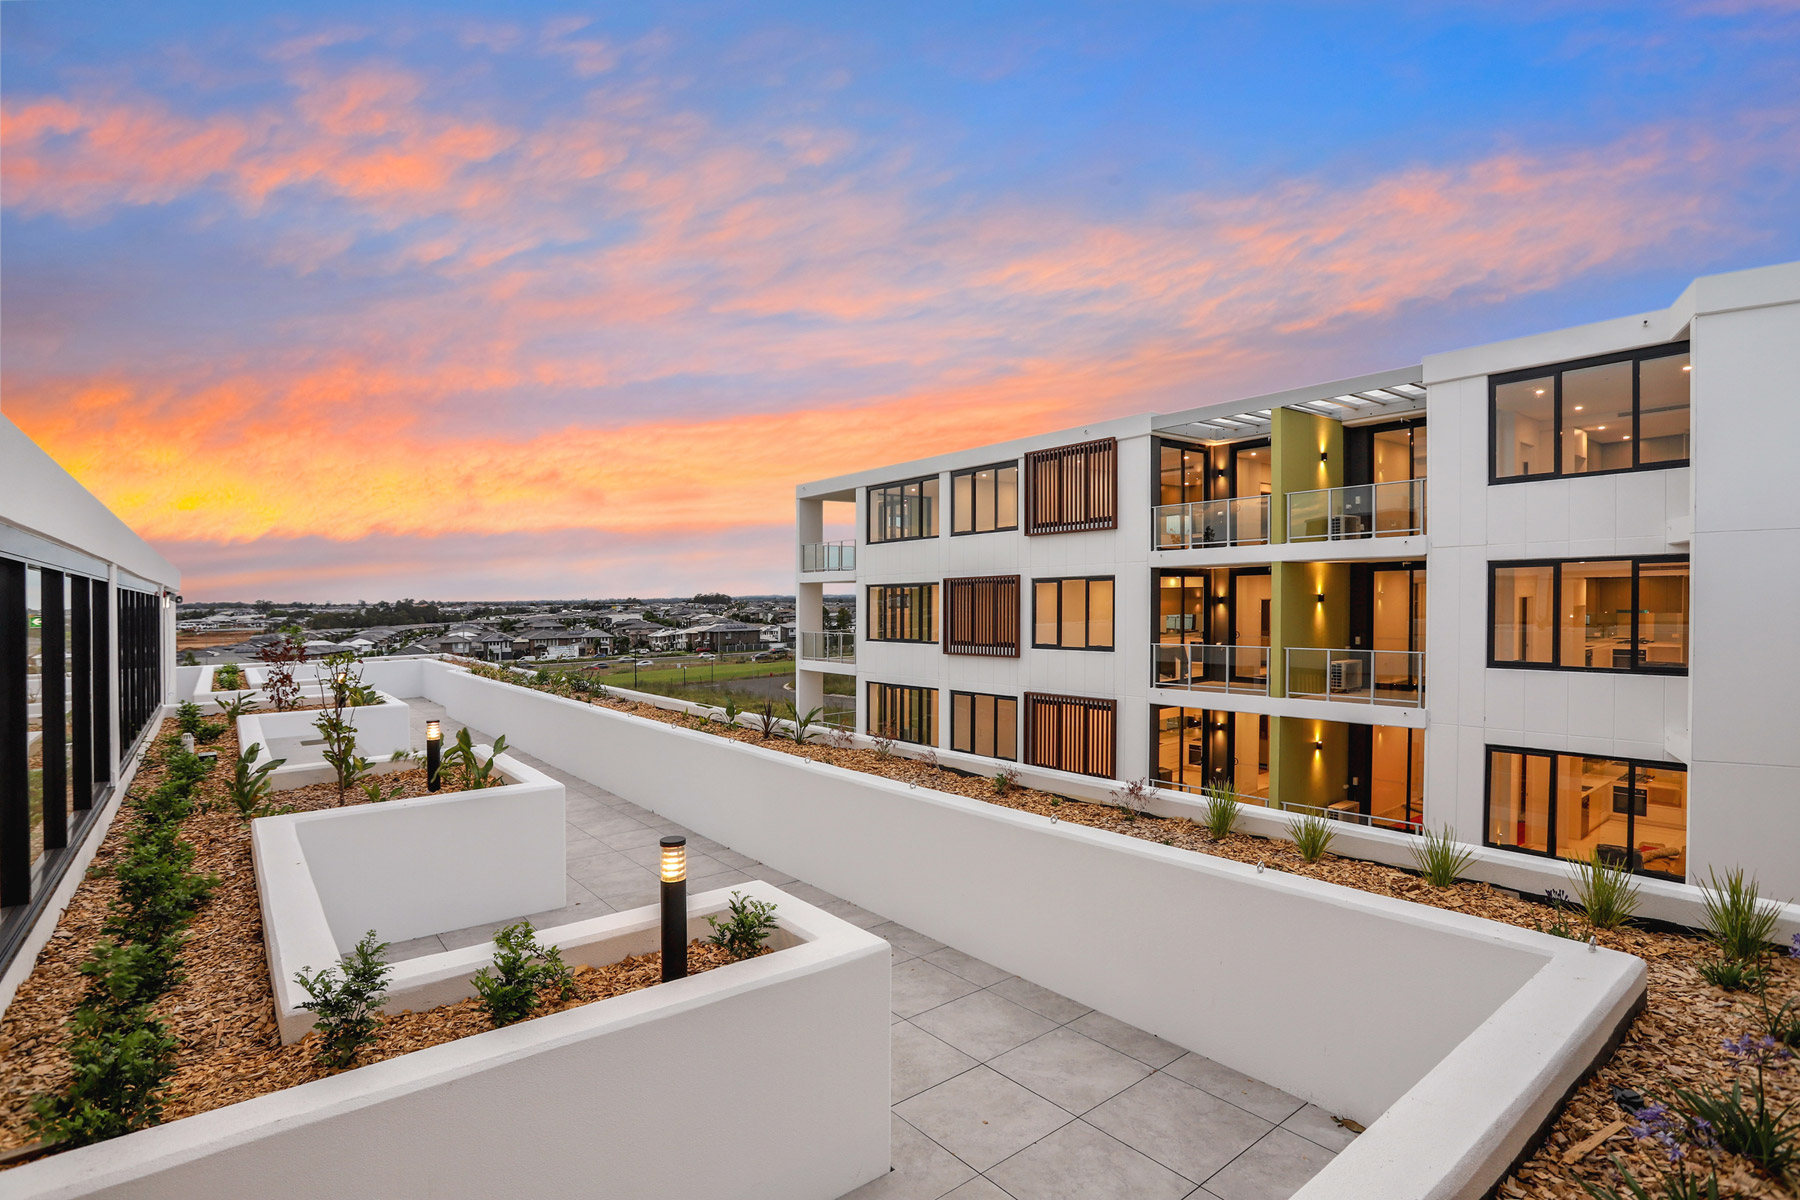
Ophora Tallawong has launched its final release of quality apartments priced under $700,000.
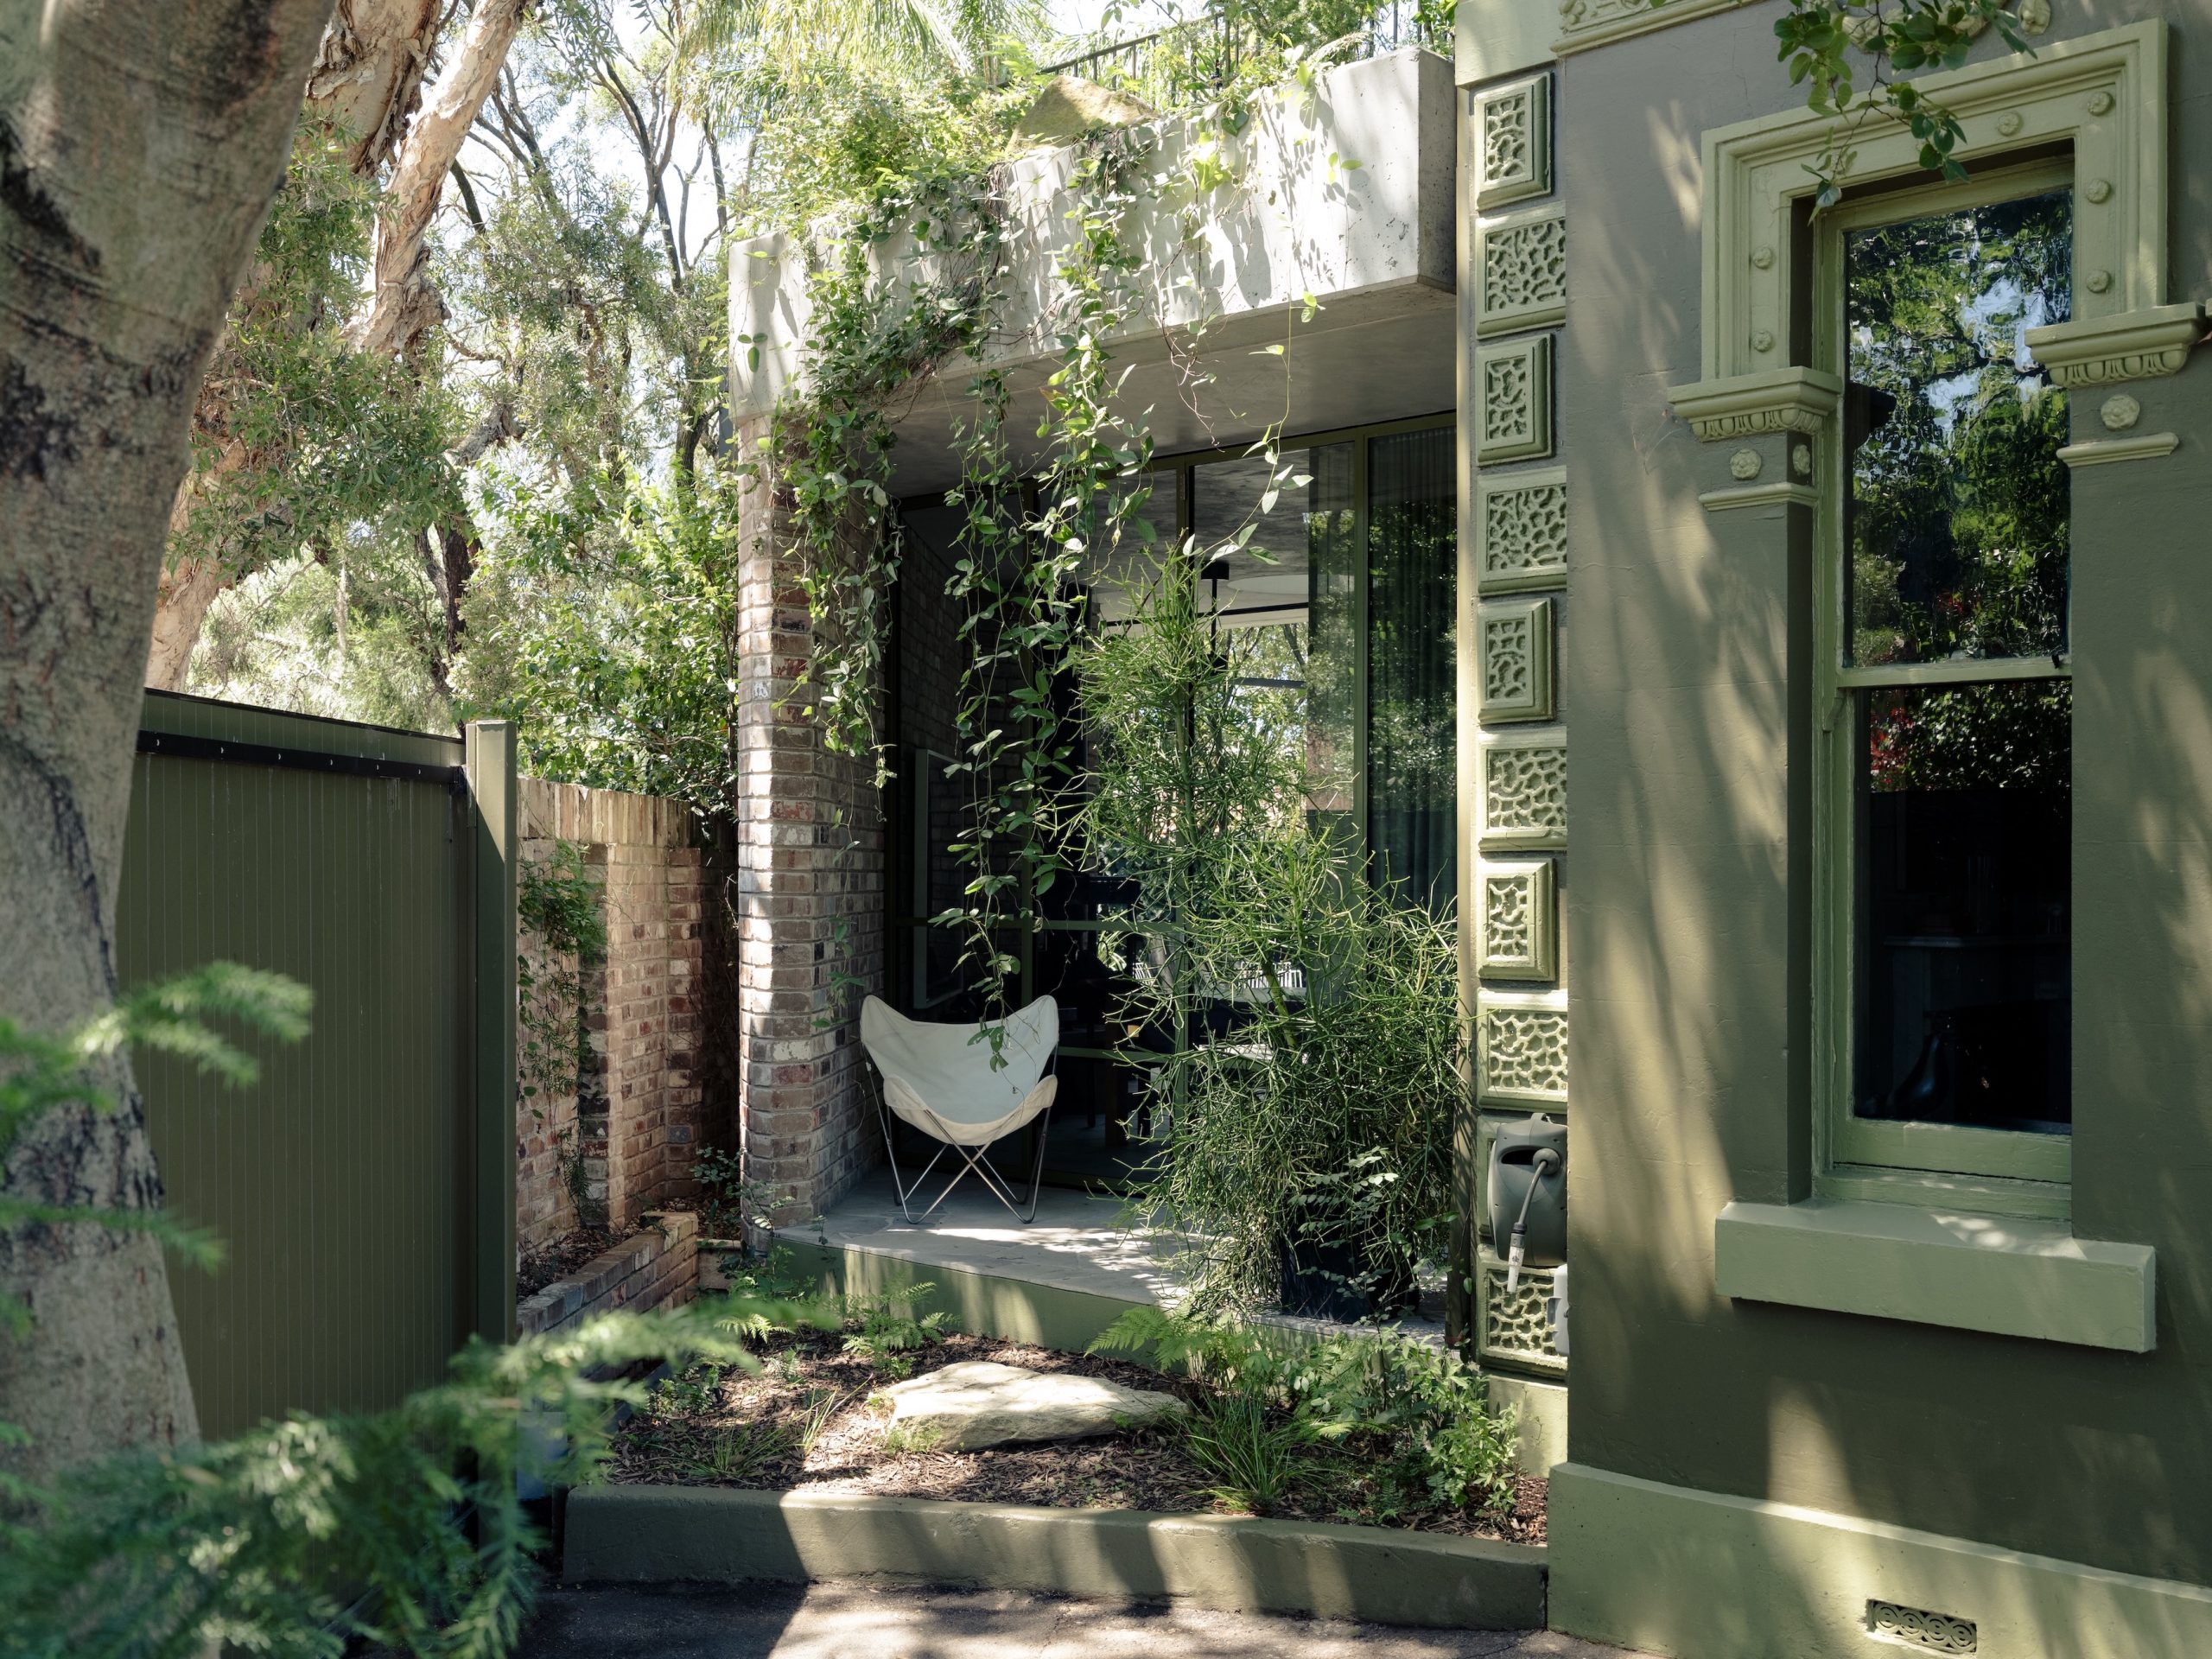
From bushland greens to valley reds, the country’s most awarded designers are proving that the best colour palette was never on a swatch card; it was outside the window all along.