The Art Market Is Tanking. Sotheby’s Has Even Bigger Problems.
The auction house, owned by highly leveraged billionaire Patrick Drahi, is pushing off payments, awaiting a financial lifeline from an Abu Dhabi fund

 10 min
The art market is grinding through a rough patch, and no one is feeling the pain more than Sotheby’s.
The sales downturn, driven in part by China’s economic slowdown, wars and volatile U.S. elections, has hit at a crunchtime for the auction house’s highly leveraged billionaire owner, Patrick Drahi , who is fighting fires amid restructuring in his broader telecom empire, Altice .
Sotheby’s had been riding a rollicking art market wave in recent years, bringing in at least $7 billion in sales annually and setting record-level prices for trophies by Gustav Klimt and René Magritte.
Now, amid signs cash is running low, it is pushing off payments to its art shippers and conservators by as much as six months. Several former and current employees said Sotheby’s this spring gave senior staffers IOUs instead of their incentive pay. And at a meeting this month of higher-ranking executives, some executives expressed worries about whether the company would be able to keep paying its employees on time, according to a person familiar with the discussion.
Drahi has at the same time been under pressure to slash the crushing debt of roughly $60 billion at Altice. The conglomerate’s French arm is now going through restructuring talks with creditors, with the U.S. arm expected to enter restructuring talks later. Some Wall Street analysts had hoped Drahi might sell part of Sotheby’s to help bolster Altice.
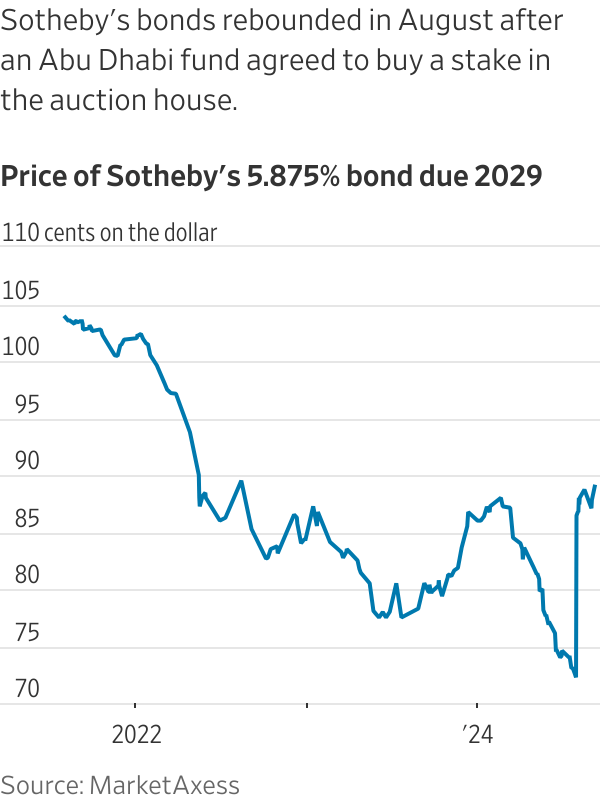
Sotheby’s itself carries $1.8 billion in debt, almost double the level it had before the Franco-Israeli billionaire purchased it in 2019. The value of its bonds swooned in the first half of the year as investors worried that declining sales and higher interest rates would choke off the company’s cash flow.
The auction house received a lifeline with a $1 billion deal to sell a stake to Abu Dhabi sovereign-wealth fund ADQ , announced Aug. 9 but not expected to close until later this year. At the time, Drahi said he would contribute an undisclosed amount as part of the deal.
As it awaits the funds, Sotheby’s is toeing a high-wire act with an uncertain outcome.
Charles Stewart , Sotheby’s chief executive, dismissed fears about Sotheby’s financial standing as overblown, and the company disputed the meeting with higher-ranking executives occurred. Stewart said the company’s bonds, which have rebounded in price since the ADQ rescue was announced, are proof that Sotheby’s has smoothed over any worries. He said the ADQ investment will position the house for growth moving forward. “It’s a massive credit positive,” he said.
A Sotheby’s spokeswoman said: “Under Mr. Drahi’s ownership, Sotheby’s is significantly larger, more diversified and more profitable than ever before. During this period, we have invested hundreds of millions to enhance our facilities, technology and expand our offerings to clients.”
ADQ declined to comment.
The crisis at Sotheby’s comes at a time when the entire art market is reeling . Over the past year, collectors who see art as a financial asset have winced as higher interest rates and inflation made it more expensive to trade art. Contemporary art buyers have also suffered sticker shock after years of paying ever-higher prices for emerging artists—who may never pay off. Some smaller galleries, who rely on collectors to vouch for unknown artists, have shuttered, while dealers have reported lacklustre sales at art fairs.
Those factors have hurt collectors’ overall confidence. “I don’t feel like there’s a bunch of collectors waiting out there to save the day this time,” said Dallas collector Howard Rachofsky.
Growing debt load
Drahi, 61 years old, is famous for taking on a mountain of debt to build telecommunications empire Altice, which operates in the U.S. and Europe. He borrowed from Wall Street when interest rates were low, but now that rates have risen sharply, he has started selling off chunks of his companies to lower his debt burden. Last month, his Altice UK sold a 24.5% stake in its BT Group to the Indian international investment arm of Bharti Enterprises in a deal valued at roughly $4 billion.
Drahi used a similar high-debt strategy to buy Sotheby’s in 2019 for $2.7 billion. Drahi issued $1.1 billion in new bonds and loans to finance the deal, and separately also assumed some portion of Sotheby’s existing $1 billion debt.
He has since spent lavishly, including signing a deal to pay at least $100 million for New York’s Breuer building, a Madison Avenue showpiece once home to the Whitney Museum of American Art and temporarily used by both the Metropolitan Museum of Art and Frick Collection. The company is planning to move in at the end of next year and to lease out part of its current glassy headquarters closer to the East River in Manhattan. Sotheby’s has spent tens of millions more to renovate new luxury-retail-style spaces in Paris and Hong Kong.
Drahi also expanded Sotheby’s ability to auction multimillion-dollar homes by buying a chunk of real-estate seller Concierge, and added RM Sotheby’s, an entity that sells high-end cars.
At the same time, the owner has pulled funds out of the company via dividends. In total since the purchase, Sotheby’s has paid out $1.2 billion of dividends to a parent company controlled by Drahi, according to New Street Research.
The ballooning debt didn’t draw much attention during flush years when an influx of newly wealthy collectors from across China, Russia, the Middle East and even the world of cryptocurrency were clamouring after Sotheby’s offerings.
That changed when the market cooled. Sotheby’s told its bondholders the auction portion of the business had a loss of $115 million in the first half of the year, compared to a $3 million profit in the first half of 2023, according to a copy of Sotheby’s unaudited financials for the first half of the year reviewed by The Wall Street Journal.
Rival Christie’s, owned by luxury magnate François Pinault , has also taken a hit, with its auction sales dropping nearly a quarter during the first half of the year.
Sotheby’s adjusted operating free cash flow fell to $144 million in the 12 months ended June 30, a 43% decline from the same time last year, according to data from New Street Research. The figure measures whether a company is making enough money to pay its bills and turn a profit.
Credit rating firm Moody’s Investors Service in February knocked down the ratings for Sotheby’s bonds to B3, one of its lowest categories of junk debt, specifically citing the dividends paid out. “The downgrade also reflects governance considerations, particularly the company’s decision to continue dividend payments out of its credit group in 2023 despite its operating performance deterioration,” Moody’s said in its decision. S&P downgraded the debt into deep junk territory in June.
Stewart said the company’s credit rating has been lower since the Drahi purchase. He said its updates to bondholders revolve around its auction performance only and don’t include fees from the company’s real-estate holdings or financial-services arm, which Stewart said remain in the black. He declined to divulge the company’s full financial figures.
Stewart also said the dividends remain in the Sotheby’s ecosystem and aren’t being redirected to shore up Drahi or his other businesses.
Drahi’s arrival
Sotheby’s was flush with cash but lagging behind Christie’s in 2018 when Tad Smith, the auction house’s then-CEO, suggested to his board that it find a buyer. The company had been public for three decades, but Smith believed the demands for public shareholder returns hampered its ability to go toe-to-toe with the bigger and privately held Christie’s.
In early 2019, the board let Smith make overtures to prospective buyers, including an entity connected to Abu Dhabi’s royal family that expressed interest, according to a person familiar with the negotiations. Drahi moved more quickly and emerged as the winner.
At first, the art establishment didn’t know much about Drahi. The self-made billionaire was born in Morocco, educated in France and has homes in Switzerland and Israel. He was familiar to Sotheby’s staffers in their Tel Aviv office but wasn’t widely known in art circles.
At the time, he was a traditional collector of 19th- and 20th-century artists rather than trendier, contemporary ones, owning pieces by Pablo Picasso, Henri Matisse and Marc Chagall. But he didn’t sit on major museum boards or pop up regularly on the art-fair circuit.
The Sotheby’s purchase marked Drahi’s first foray into luxury. The art world wondered if he would manage a house that started off auctioning books in London in 1744 the same way he ran his broadband communications companies, where he was known for aggressively cutting costs and using debt to fuel ambitious expansions.
Drahi told Sotheby’s he saw the company as an investment for his family, regularly dismissing rumors he was teeing up Sotheby’s to be resold. In 2021, Sotheby’s promoted his son Nathan, then 26, to run Sotheby’s operations in Asia, a key market.
As part of the sale, Sotheby’s divided its various endeavors—such as its real-estate arm and its financial services arm, which lends against people’s art collections—into affiliated but separate entities from the main unit, which handles Sotheby’s auctions and private art sales.
Stewart said Drahi’s move was intended to keep each division nimble.
The art-world ecosystem noticed Drahi’s arrival in other ways. Soon after the sale, a network of smaller companies that auction houses typically enlist to conserve, frame, crate and ship its art around the world said they got word that the house would be lengthening its pay schedules, from a typical month to two or more. One conservator said payments started to arrive six months after a job was completed.
Sotheby’s also started paying sellers more slowly than its rivals. In the past, both Sotheby’s and Christie’s asked winning bidders to pay for their pieces within 30 business days of a sale, and then paid sellers five days later. Sotheby’s changed its contracts to allow it to pay sellers 15 days later, according to sellers familiar with the house’s contracts. The move allowed the house to hold the funds in its coffers longer.
Sotheby’s said its processing deadlines have been in place for many years to allow the company to adequately process payments.
Pay for top talent
When the pandemic hit, Drahi and his management team reoriented the company to sell art online, a pivot Sotheby’s is credited with embracing faster than its rivals.
Sotheby’s also started laying off staff during the lockdown, and continued to do so after the pandemic. When the ever-swirling calendar of fairs and museum openings and biennials got under way again, advisers including Philip Hoffman of the Fine Art Group said they noticed fewer Sotheby’s staffers turned up. The company would send one or two rainmakers, not a whole team.
Stewart confirmed the pandemic-related staff cuts “like many other companies” and winnowed travel were meant to make the company more efficient, though he said it remains “mission critical” to put its top specialists in front of collectors.
Drahi needed Sotheby’s key dealmakers to remain in place. High-end art deals at auction houses are wrangled primarily by a handful of executives and specialists able to cultivate an air-kiss closeness with collectors. They also must be able to discern a fake Picasso from a real one, and price it to sell well in good markets and bad.
In 2021, Drahi revised the incentive pay program for these top performers. In exchange for accepting an immediate pay cut of up to 20%, employees were told they could expect a cash payout in three years based on the company’s performance and representing up to half of their total compensation.
Some powerful executives still left, dealing a blow to the auction house. Patti Wong , Sotheby’s former international chairman for Asia, now works as a private adviser, and Brooke Lampley , its former global chairman of fine art, is now a senior director at the blue-chip gallery Gagosian.
When the delayed payout came due, staff were told in conference calls—some say last fall and others say in March—that it needed to be postponed; enrollees were issued promissory notes this spring instead, according to several former and current specialists. Specialists said they now are hoping to get paid by year’s end with a portion of the Abu Dhabi funds.
The company disputed the description of the incentive program but declined to give further details.
New fees for sellers
In February, Sotheby’s shocked the art world when it fundamentally restructured the way it collects fees for works that it auctions.
Both Sotheby’s and Christie’s, in efforts to bring sellers to their doors, often waived their fees. They even shared with sellers increasingly fatter slices of the fees they charge buyers—which can add up to roughly 27% to a work’s winning price.
At the same time, buyers have bristled over the fees they pay. Rachofsky, the Dallas collector, said he has long agitated that “auction fees are unsustainably high.”
Sotheby’s new fee plan, which went live in late May, now charges buyers a flat 20% for anything it sells for $6 million or less, and 10% for anything it sells for more. For sellers, Sotheby’s charges a fee of 10% on the first $500,000 of anything it sells for $5 million or less. Terms for larger deals continue to be negotiated.
Christie’s and smaller house Phillips said they also charge an undisclosed seller’s commission, but their fee is negotiable.
Stewart said the goal is to create a system that is “simpler and fairer.”
It’s too soon to tell if Sotheby’s new fee structure will help or hamper its effort to win consignments. Sotheby’s has landed the prized estate of the season, an estimated $200 million collection amassed by Palm Beach beauty mogul Sydell Miller that includes a Claude Monet water lily scene estimated to sell for $60 million. The collection will headline the November sales.
Art adviser Anthony Grant said one of his collectors reasons that Sotheby’s might hustle harder to find bidders for each work now that they’re charging sellers a fee to do so. But Grant said he worries the change could also steer sellers of midmarket pieces to other houses who may not charge them extra for anything.
“It’s one more thing that’s gotten harder for them,” he said of Sotheby’s, where he once worked.
Asia is expected to play a crucial role in Sotheby’s prospects. In recent years, newly wealthy bidders in Asia—spanning mainland China to Seoul to Singapore—have been relied upon to mop up art at the highest levels even when collectors elsewhere held back. Now, China’s economy has slowed, sparking fears about its buyers’ willingness to splurge on blue-chip art.
Instead of scaling back, the major auction houses are all doubling down on the region. Sotheby’s and Christie’s both just opened luxurious new spaces in Hong Kong. Sotheby’s Maison space in Hong Kong’s Central neighborhood, opened in late July, said it has already had 300,000 visitors.
This month, on the eve of what was supposed to be its inaugural fall sale series in Hong Kong, the house announced it was pushing back these sales to November. Advisers who work in the region said the move left the impression that the house had failed to gather enough marquee material.
Sotheby’s said the calendar shift gives it more time to organise shows and a sale lineup, and said the delay wasn’t because the art was too tough to source. It cited its plan to sell an estimated $30 million Mark Rothko from 1954, “Untitled (Yellow and Blue),” in Hong Kong later this year.
Collector and dealer Hong Gyu Shin initially consigned an Oscar Wilde manuscript of “The Picture of Dorian Gray” to Sotheby’s to offer in its Hong Kong sales, he said, but he later changed his mind. He said he wanted the auction house to revel in the piece, which contains Wilde’s own handwritten edits, and he wanted to brainstorm the best way to position it to buyers. Instead, there was little conversation after the paperwork was signed.
“Specialists used to be so excited,” he said, “but now they just slap an estimate on it. When you have historical work, it’s a form of art to sell it.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
As housing drives wealth and policy debate, the real risk is an economy hooked on growth without productivity to sustain it.
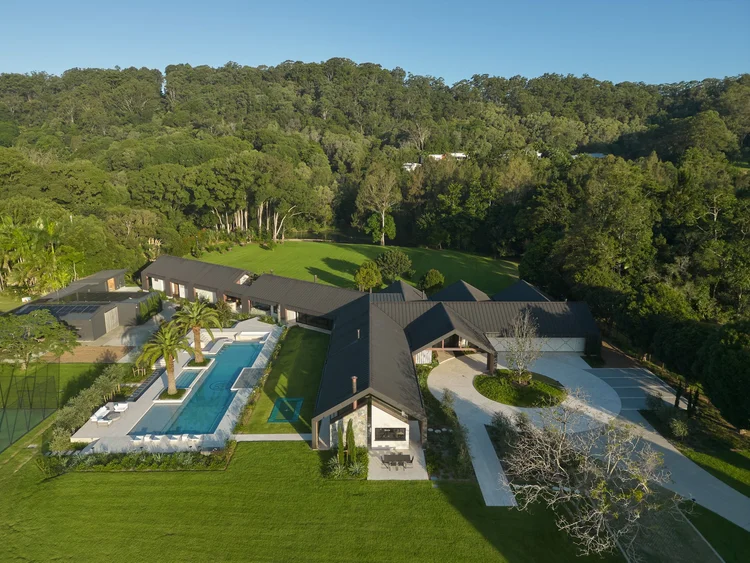
Margot Robbie may have travelled from a Queensland farm to the highest reaches of Hollywood, but a reported $28 million property deal suggests the Gold Coast has never lost its hold on her. The Australian actor and producer is believed to be the mystery buyer of Redwood, a seven-acre Currumbin Valley estate transformed into the …
Continue reading “Margot Robbie Reportedly Behind $28 Million Currumbin Valley Homecoming”