





Europeans Are Becoming Poorer. ‘Yes, We’re All Worse Off.’
An ageing population that values its free time set the stage for economic stagnation. Then came Covid-19 and Russia’s war in Ukraine.

 8 min
Europeans are facing a new economic reality, one they haven’t experienced in decades. They are becoming poorer.
Life on a continent long envied by outsiders for its art de vivre is rapidly losing its shine as Europeans see their purchasing power melt away.
The French are eating less foie gras and drinking less red wine. Spaniards are stinting on olive oil. Finns are being urged to use saunas on windy days when energy is less expensive. Across Germany, meat and milk consumption has fallen to the lowest level in three decades and the once-booming market for organic food has tanked. Italy’s economic development minister, Adolfo Urso, convened a crisis meeting in May over prices for pasta, the country’s favourite staple, after they jumped by more than double the national inflation rate.
With consumption spending in free fall, Europe tipped into recession at the start of the year, reinforcing a sense of relative economic, political and military decline that kicked in at the start of the century.
Europe’s current predicament has been long in the making. An ageing population with a preference for free time and job security over earnings ushered in years of lacklustre economic and productivity growth. Then came the one-two punch of the Covid-19 pandemic and Russia’s protracted war in Ukraine. By upending global supply chains and sending the prices of energy and food rocketing, the crises aggravated ailments that had been festering for decades.
Governments’ responses only compounded the problem. To preserve jobs, they steered their subsidies primarily to employers, leaving consumers without a cash cushion when the price shock came. Americans, by contrast, benefited from inexpensive energy and government aid directed primarily at citizens to keep them spending.
In the past, the continent’s formidable export industry might have come to the rescue. But a sluggish recovery in China, a critical market for Europe, is undermining that growth pillar. High energy costs and rampant inflation at a level not seen since the 1970s are dulling manufacturers’ price advantage in international markets and smashing the continent’s once-harmonious labor relations. As global trade cools, Europe’s heavy reliance on exports—which account for about 50% of eurozone GDP versus 10% for the U.S.—is becoming a weakness.
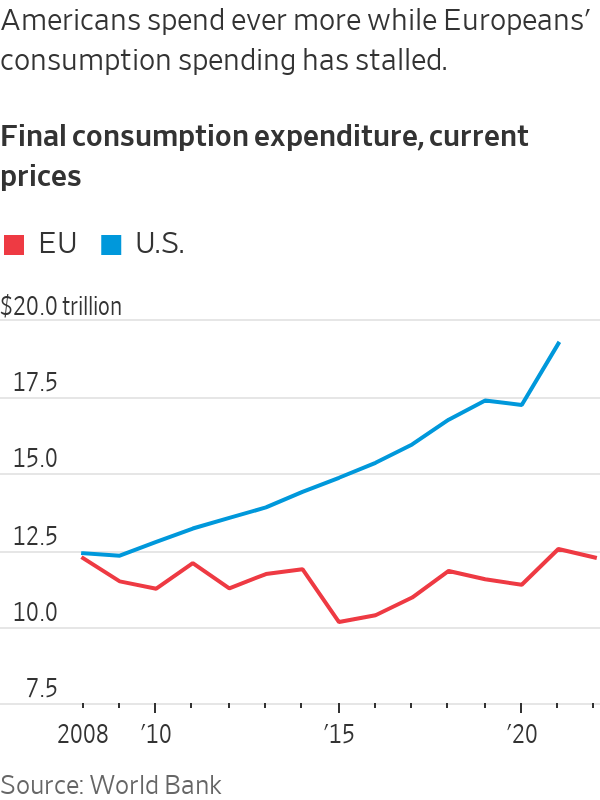
Private consumption has declined by about 1% in the 20-nation eurozone since the end of 2019 after adjusting for inflation, according to the Organization for Economic Cooperation and Development, a Paris-based club of mainly wealthy countries. In the U.S., where households enjoy a strong labor market and rising incomes, it has increased by nearly 9%. The European Union now accounts for about 18% of all global consumption spending, compared with 28% for America. Fifteen years ago, the EU and the U.S. each represented about a quarter of that total.
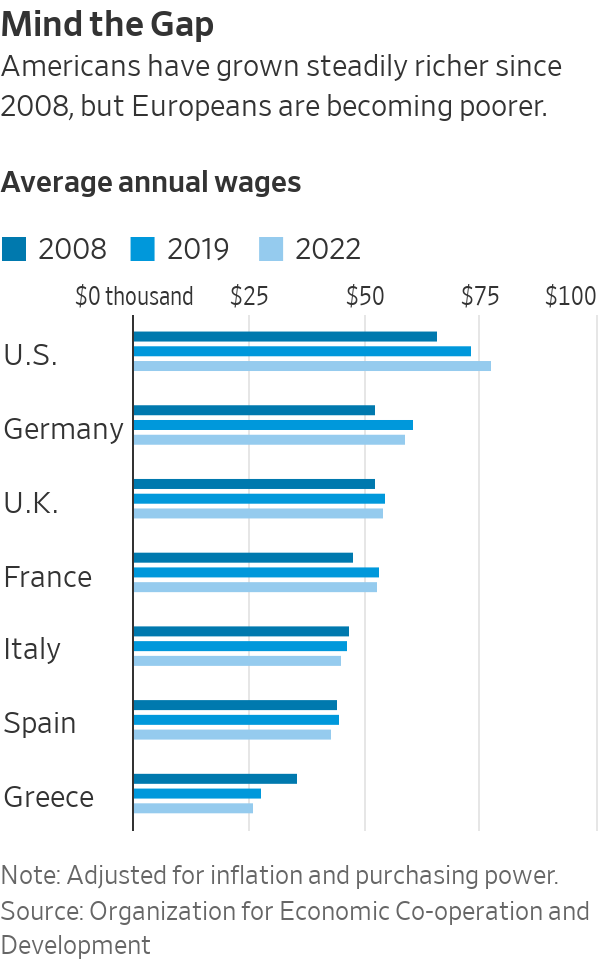
Adjusted for inflation and purchasing power, wages have declined by about 3% since 2019 in Germany, by 3.5% in Italy and Spain and by 6% in Greece. Real wages in the U.S. have increased by about 6% over the same period, according to OECD data.
The pain reaches far into the middle classes. In Brussels, one of Europe’s richest cities, teachers and nurses stood in line on a recent evening to collect half-price groceries from the back of a truck. The vendor, Happy Hours Market, collects food close to its expiration date from supermarkets and advertises it through an app. Customers can order in the early afternoon and collect their cut-price groceries in the evening.
“Some customers tell me, because of you I can eat meat two or three times per week,” said Pierre van Hede, who was handing out crates of groceries.
Karim Bouazza, a 33-year-old nurse who was stocking up on half-price meat and fish for his wife and two children, complained that inflation means “you almost need to work a second job to pay for everything.”
Similar services have sprung up across the region, marketing themselves as a way to reduce food waste as well as save money. TooGoodToGo, a company founded in Denmark in 2015 that sells leftover food from retailers and restaurants, has 76 million registered users across Europe, roughly three times the number at the end of 2020. In Germany, Sirplus, a startup created in 2017, offers “rescued” food, including products past their sell-by date, on its online store. So does Motatos, created in Sweden in 2014 and now present in Finland, Germany, Denmark and the U.K.
Spending on high-end groceries has collapsed. Germans consumed 52 kilograms of meat per person in 2022, about 8% less than the previous year and the lowest level since calculations began in 1989. While some of that reflects societal concerns about healthy eating and animal welfare, experts say the trend has been accelerated by meat prices which increased by up to 30% in recent months. Germans are also swapping meats such as beef and veal for less-expensive ones such as poultry, according to the Federal Information Center for Agriculture.
Thomas Wolff, an organic-food supplier near Frankfurt, said his sales fell by up to 30% last year as inflation surged. Wolff said he had hired 33 people earlier in the pandemic to handle strong demand for pricey ecological foodstuffs, but he has since let them all go.
Ronja Ebeling, a 26-year-old consultant and author based in Hamburg, said she saves about one-quarter of her income, partly because she worries about having enough money for retirement. She spends little on clothes or makeup and shares a car with her partner’s father.
Weak spending and poor demographic prospects are making Europe less attractive for businesses ranging from consumer-goods giant Procter & Gamble to luxury empire LVMH, which are making an ever-larger share of their sales in North America.
“The U.S. consumer is more resilient than in Europe,” Unilever’s chief financial officer, Graeme Pitkethly, said in April.
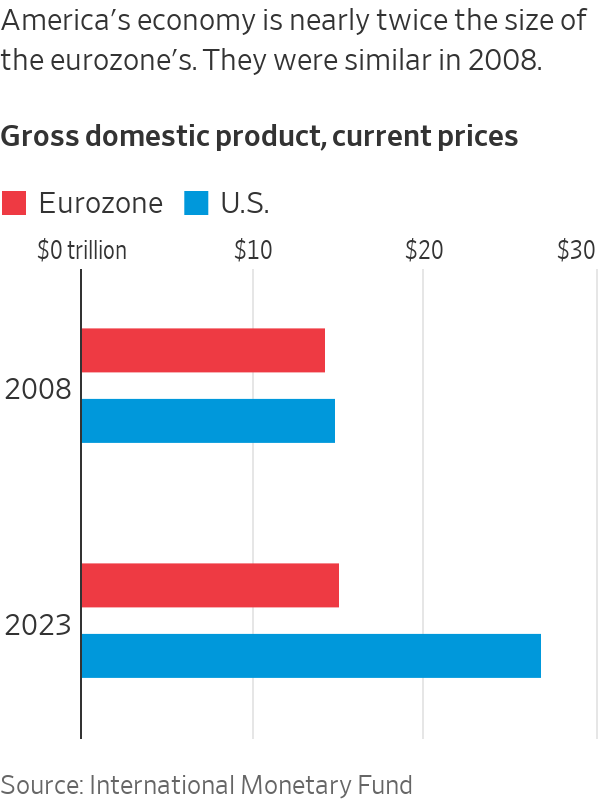
The eurozone economy grew about 6% over the past 15 years, measured in dollars, compared with 82% for the U.S., according to International Monetary Fund data. That has left the average EU country poorer per head than every U.S. state except Idaho and Mississippi, according to a report this month by the European Centre for International Political Economy, a Brussels-based independent think tank. If the current trend continues, by 2035 the gap between economic output per capita in the U.S. and EU will be as large as that between Japan and Ecuador today, the report said.
On the Mediterranean island of Mallorca, businesses are lobbying for more flights to the U.S. to increase the number of free-spending American tourists, said Maria Frontera, president of the Mallorca Chamber of Commerce’s tourism commission. Americans spend about €260 ($292) per day on average on hotels compared with less than €180 ($202) for Europeans.
“This year we have seen a big change in the behaviour of Europeans because of the economic situation we are dealing with,” said Frontera, who recently traveled to Miami to learn how to better cater to American customers.
Weak growth and rising interest rates are straining Europe’s generous welfare states, which provide popular healthcare services and pensions. European governments find the old recipes for fixing the problem are either becoming unaffordable or have stopped working. Three-quarters of a trillion euros in subsidies, tax breaks and other forms of relief have gone to consumers and businesses to offset higher energy costs—something economists say is now itself fuelling inflation, defeating the subsidies’ purpose.
Public-spending cuts after the global financial crisis starved Europe’s state-funded healthcare systems, especially the U.K.’s National Health Service.
Vivek Trivedi, a 31-year-old anaesthesiologist living in Manchester, England, earns about £51,000 ($67,000) per year for a 48-hour workweek. Inflation, which has been about 10% or higher in the U.K. for nearly a year, is devouring his monthly budget, he says. Trivedi said he shops for groceries in discount retailers and spends less on meals out. Some colleagues turned off their heating entirely over recent months, worried they wouldn’t be able to afford sharply higher costs, he said.
Noa Cohen, a 28-year old public-affairs specialist in London, says she could quadruple her salary in the same job by leveraging her U.S. passport to move across the Atlantic. Cohen recently got a 10% pay raise after switching jobs, but the increase was completely swallowed by inflation. She says friends are freezing their eggs because they can’t afford children anytime soon, in the hope that they have enough money in future.
“It feels like a perma-freeze in living standards,” she said.
Huw Pill, the Bank of England’s chief economist, warned U.K. citizens in April that they need to accept that they are poorer and stop pushing for higher wages. “Yes, we’re all worse off,” he said, saying that seeking to offset rising prices with higher wages would only fuel more inflation.
With European governments needing to increase defence spending and given rising borrowing costs, economists expect taxes to increase, adding pressure on consumers. Taxes in Europe are already high relative to those in other wealthy countries, equivalent to around 40-45% of GDP compared with 27% in the U.S. American workers take home almost three-quarters of their pay checks, including income taxes and Social Security taxes, while French and German workers keep just half.
The pauperisation of Europe has bolstered the ranks of labor unions, which are picking up tens of thousands of members across the continent, reversing a decades long decline.
Higher unionisation may not translate into fuller pockets for members. That’s because many are pushing workers’ preference for more free time over higher pay, even in a world of spiralling skills shortages.
IG Metall, Germany’s biggest trade union, is calling for a four-day work week at current salary levels rather than a pay raise for the country’s metalworkers ahead of collective bargaining negotiations this November. Officials say the shorter week would improve workers’ health and quality of life while at the same time making the industry more attractive to younger workers.
Almost half of employees in Germany’s health industry choose to work around 30 hours per week rather than full time, reflecting tough working conditions, said Frank Werneke, chairman of the country’s United Services Trade Union, which has added about 110,000 new members in recent months, the biggest increase in 22 years.
Kristian Kallio, a games developer in northern Finland, recently decided to reduce his working week by one-fifth to 30 hours in exchange for a 10% pay cut. He now makes about €2,500 per month. “Who wouldn’t want to work shorter hours?” Kallio said. About one-third of his colleagues took the same deal, although leaders work full-time, said Kallio’s boss, Jaakko Kylmäoja.
Kallio now works from 10 a.m. to 4.30 p.m. He uses his extra free time for hobbies, to make good food and take long bike rides. “I don’t see a reality where I would go back to normal working hours,” he said.
Igor Chaykovskiy, a 34-year-old IT worker in Paris, joined a trade union earlier this year to press for better pay and conditions. He recently received a 3.5% pay increase, about half the level of inflation. He thinks the union will give workers greater leverage to press managers. Still, it isn’t just about pay. “Maybe they say you don’t have an increase in salary, you have free sports lessons or music lessons,” he said.
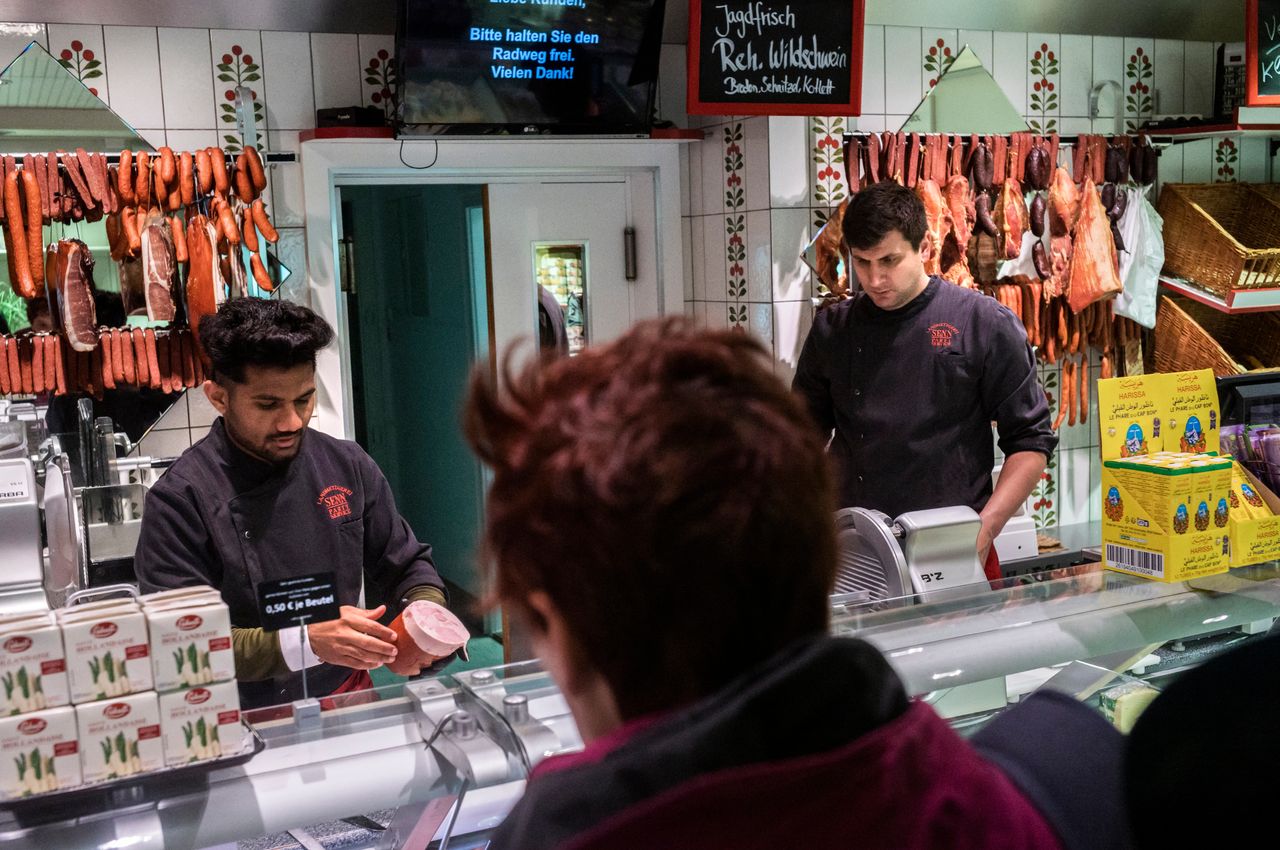
At the Stellantis auto factory in Melfi, southern Italy, employees have worked shorter hours for years recently due to the difficulty of procuring raw materials and high energy costs, said Marco Lomio, a trade unionist with the Italian Union of Metalworkers. Hours worked have recently been reduced by around 30% and wages decreased proportionally.
“Between high inflation and rising energy costs for workers,” said Lomio, “it is difficult to bear all family expenses.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

ABC Bullion has launched a pioneering investment product that allows Australians to draw regular cashflow from their precious metal holdings.
Studio apartments have almost disappeared from new Australian developments. Lura is bringing them back to Burleigh Heads from $495,000.


