I’m a Supercommuter. Here’s What It’s Really Like.
The money, miles and stamina it takes to work in New York and live in Columbus, Ohio

 5 min
Sometimes I sleep in a different New York City hotel room every night.
On a recent Monday, it was a Midtown Manhattan Hampton Inn. The next night, a budget hotel downtown. Then I moved to a Hyatt in Queens, near John F. Kennedy International Airport, where I waited to check in behind a group of pilots and flight attendants.
The reason for this madness: My job is in New York, but my apartment is in Columbus, Ohio. When hotel prices are high, I property-surf to find a lower rate.
For more than a year, to the bafflement of family, friends and colleagues, I have attempted to live and work as a supercommuter. What began as a postpandemic experiment of flying to and from New York each week has turned into what I am hesitant to call a lifestyle.
Like many, I moved out of the city early in the pandemic, relocating near family in the Midwest. When it came time to return in 2022, I was underwhelmed at the housing options in my price range. I toured one-room studios facing brick walls and climbed crumbling staircases to reach dank apartments with ancient fixtures. I also had grown accustomed to midweek evening walks with my sister in Ohio, and a short drive to see my parents. I didn’t want to fully give that up.
Using back-of-the-envelope math, I thought I could keep my expenses—rent in Ohio, plus travel costs—at or below the price of a nice New York studio, or roughly $3,200 a month. The Wall Street Journal requires office attendance at least three days a week and, since I commute by choice, I pay all my travel expenses.
Luxury suites and room service
The challenge felt oddly thrilling. If anybody could find a way to subvert high New York real-estate costs, while remaining close to family, I thought it might be me. For years, I’ve been an on-call travel guru to friends and co-workers, coaching people on how to navigate flight cancellations and play the credit-card bonus games. I memorise aircraft configurations and spend hours reading mileage blogs and industry sites like Airliners.net.
Before mileage runs became useless, I obsessed over reaching top-tier airline status by spending as little as possible. (Family members still roll their eyes at the six hours I spent in Anchorage one December afternoon to requalify for Delta’s Diamond tier.) When a flight is oversold, I am quick to volunteer my seat in exchange for a voucher. (My best-ever haul: $2,000 after giving up my seat on multiple oversold flights one Saturday in San Francisco.)
Nerding out about this stuff has allowed me to travel farther and in more rarefied air than I could otherwise afford.
Entering my supercommuter era, I had visions of flying to New York on a weekday morning (8,500 points one way on American Airlines), spending the day meeting sources and filing stories, and retiring to one of my favourite points hotels—the Beekman. Mornings would begin with a free breakfast thanks to my Hyatt status, before a short subway ride to the office. After two nights, I’d return to Columbus and my roomy apartment, half the price of a Manhattan studio.
Shocking no one, that fantasy soon came crashing down.
Burning points on fancy hotel rooms was the first problem. The life of a journalist is hard to predict. I repeatedly found myself on deadline and having to rebook flights or stay an extra night, costing me money or miles.
Once I was back in the city, it also got harder to say no. Stay an extra night to attend a friend’s birthday party or meet a CEO in town just for the day? Sign me up. I didn’t want my living situation to strain relationships or interfere with my job, which I love.
To conserve hotel points, I swapped the Beekman’s elegant rooms in lower Manhattan for a Hyatt attached to a casino in Jamaica, Queens. My rooms overlooked a sea of empty parking spaces, but required half as many points as Manhattan alternatives.
Flight delays and blown budgets
By summer, with my miles dwindling and New York hotel rates rising, I reluctantly began to rely on the kindness of those around me. Hearing I might need a place, one friend mailed me the keys to her family’s unoccupied apartment in New Jersey. Another let me stay in her smartly designed Brooklyn one-bedroom for weeks as she traveled. A cherished deskmate, known for her tell-it-like-it-is demeanour, repeatedly offered a bedroom in her Chelsea loft, handing over the keys with a sometimes expletive-tinged reminder to: “Get a f—ing apartment.”
I watered plants, walked friends’ dogs and fed their cats while they were away. Still, working in a city without a permanent home took a toll. I came to dread the go-to question asked at parties and work events in New York: “So where do you live?”
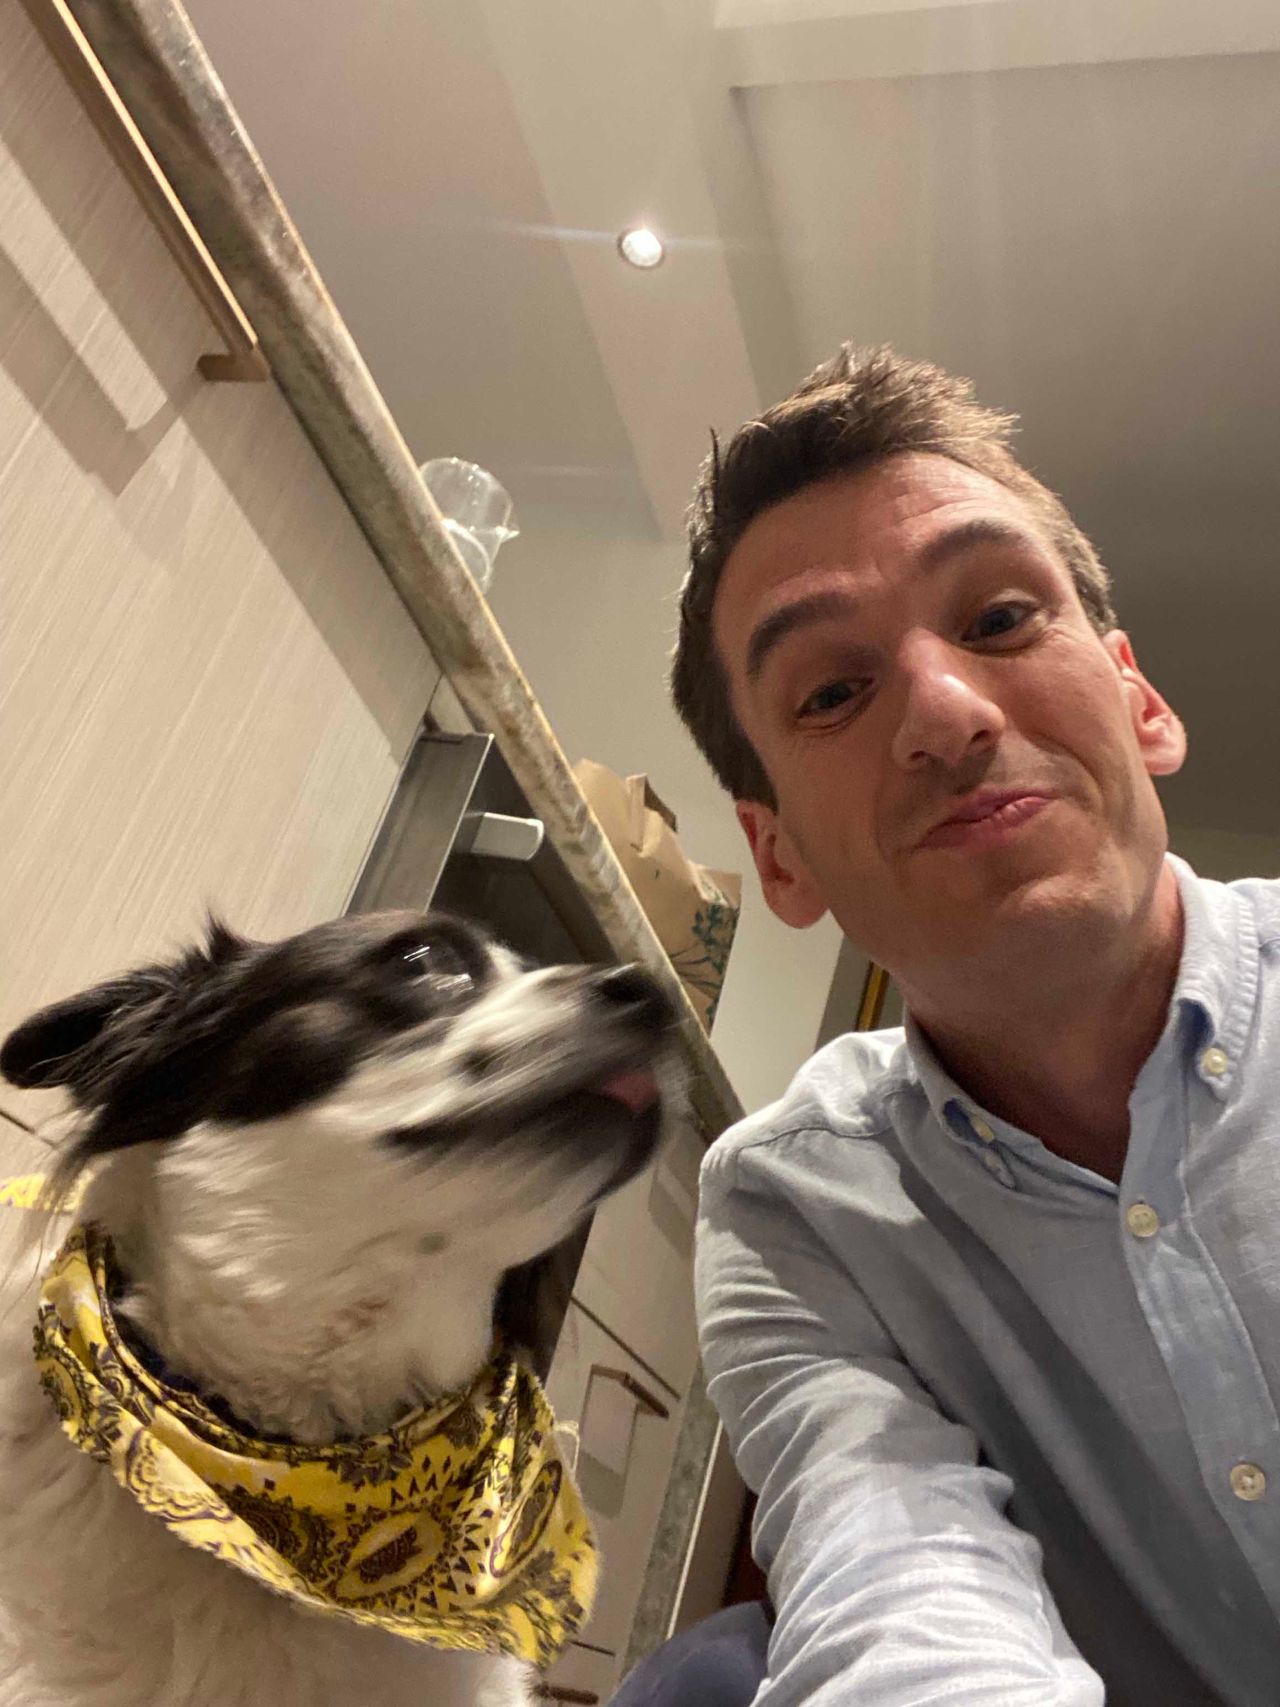
CHIP CUTTER/THE WALL STREET JOURNAL
If I admitted, “it’s kind of complicated,” I got sucked into explaining my life as a supercommuter. Sometimes, I’d just tell people the location of that evening’s hotel. (Chelsea!)
Costs mounted in the fall, New York’s prime tourist and business-travel season. Friends teased me for embracing a life of chaos. They weren’t wrong. Without a refrigerator or stove, late-night dinners often consisted of yogurt and fruit purchased from a 24-hour CVS. Needing to pack light, I stored shoes under my desk and left spare outfits on an office coat rack.
To get to the office on time, I set my alarm in Columbus for 4:15 a.m. and hustled to the airport for 6 a.m. flights. When everything went according to plan, I made it door-to-door in three hours. If delays occurred, I scrambled to rebook on other flights.
My obsessive tracking of New York hotel prices taught me that dynamic pricing isn’t reserved for airlines. Hotel costs can fluctuate half a dozen times on the check-in date, so instead of booking in advance, I’d wait to pull the trigger until 10 p.m. some days after the rates fell.
In the end, the math didn’t work. I blew my budget by 15% and drained my miles balance. But I flew so much and stayed in so many hotels that I kept my elite status with Hyatt and American.
I still enjoy having one foot in the Midwest and one on the East Coast, though I’m not sure how long I can keep it up. I’m writing this from Columbus, where I overlook a beautiful park outside my picture window. My lease is up, but hotel rates in Manhattan this winter have plunged now that the holidays are over. Maybe that New York apartment search can be put off a little longer.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
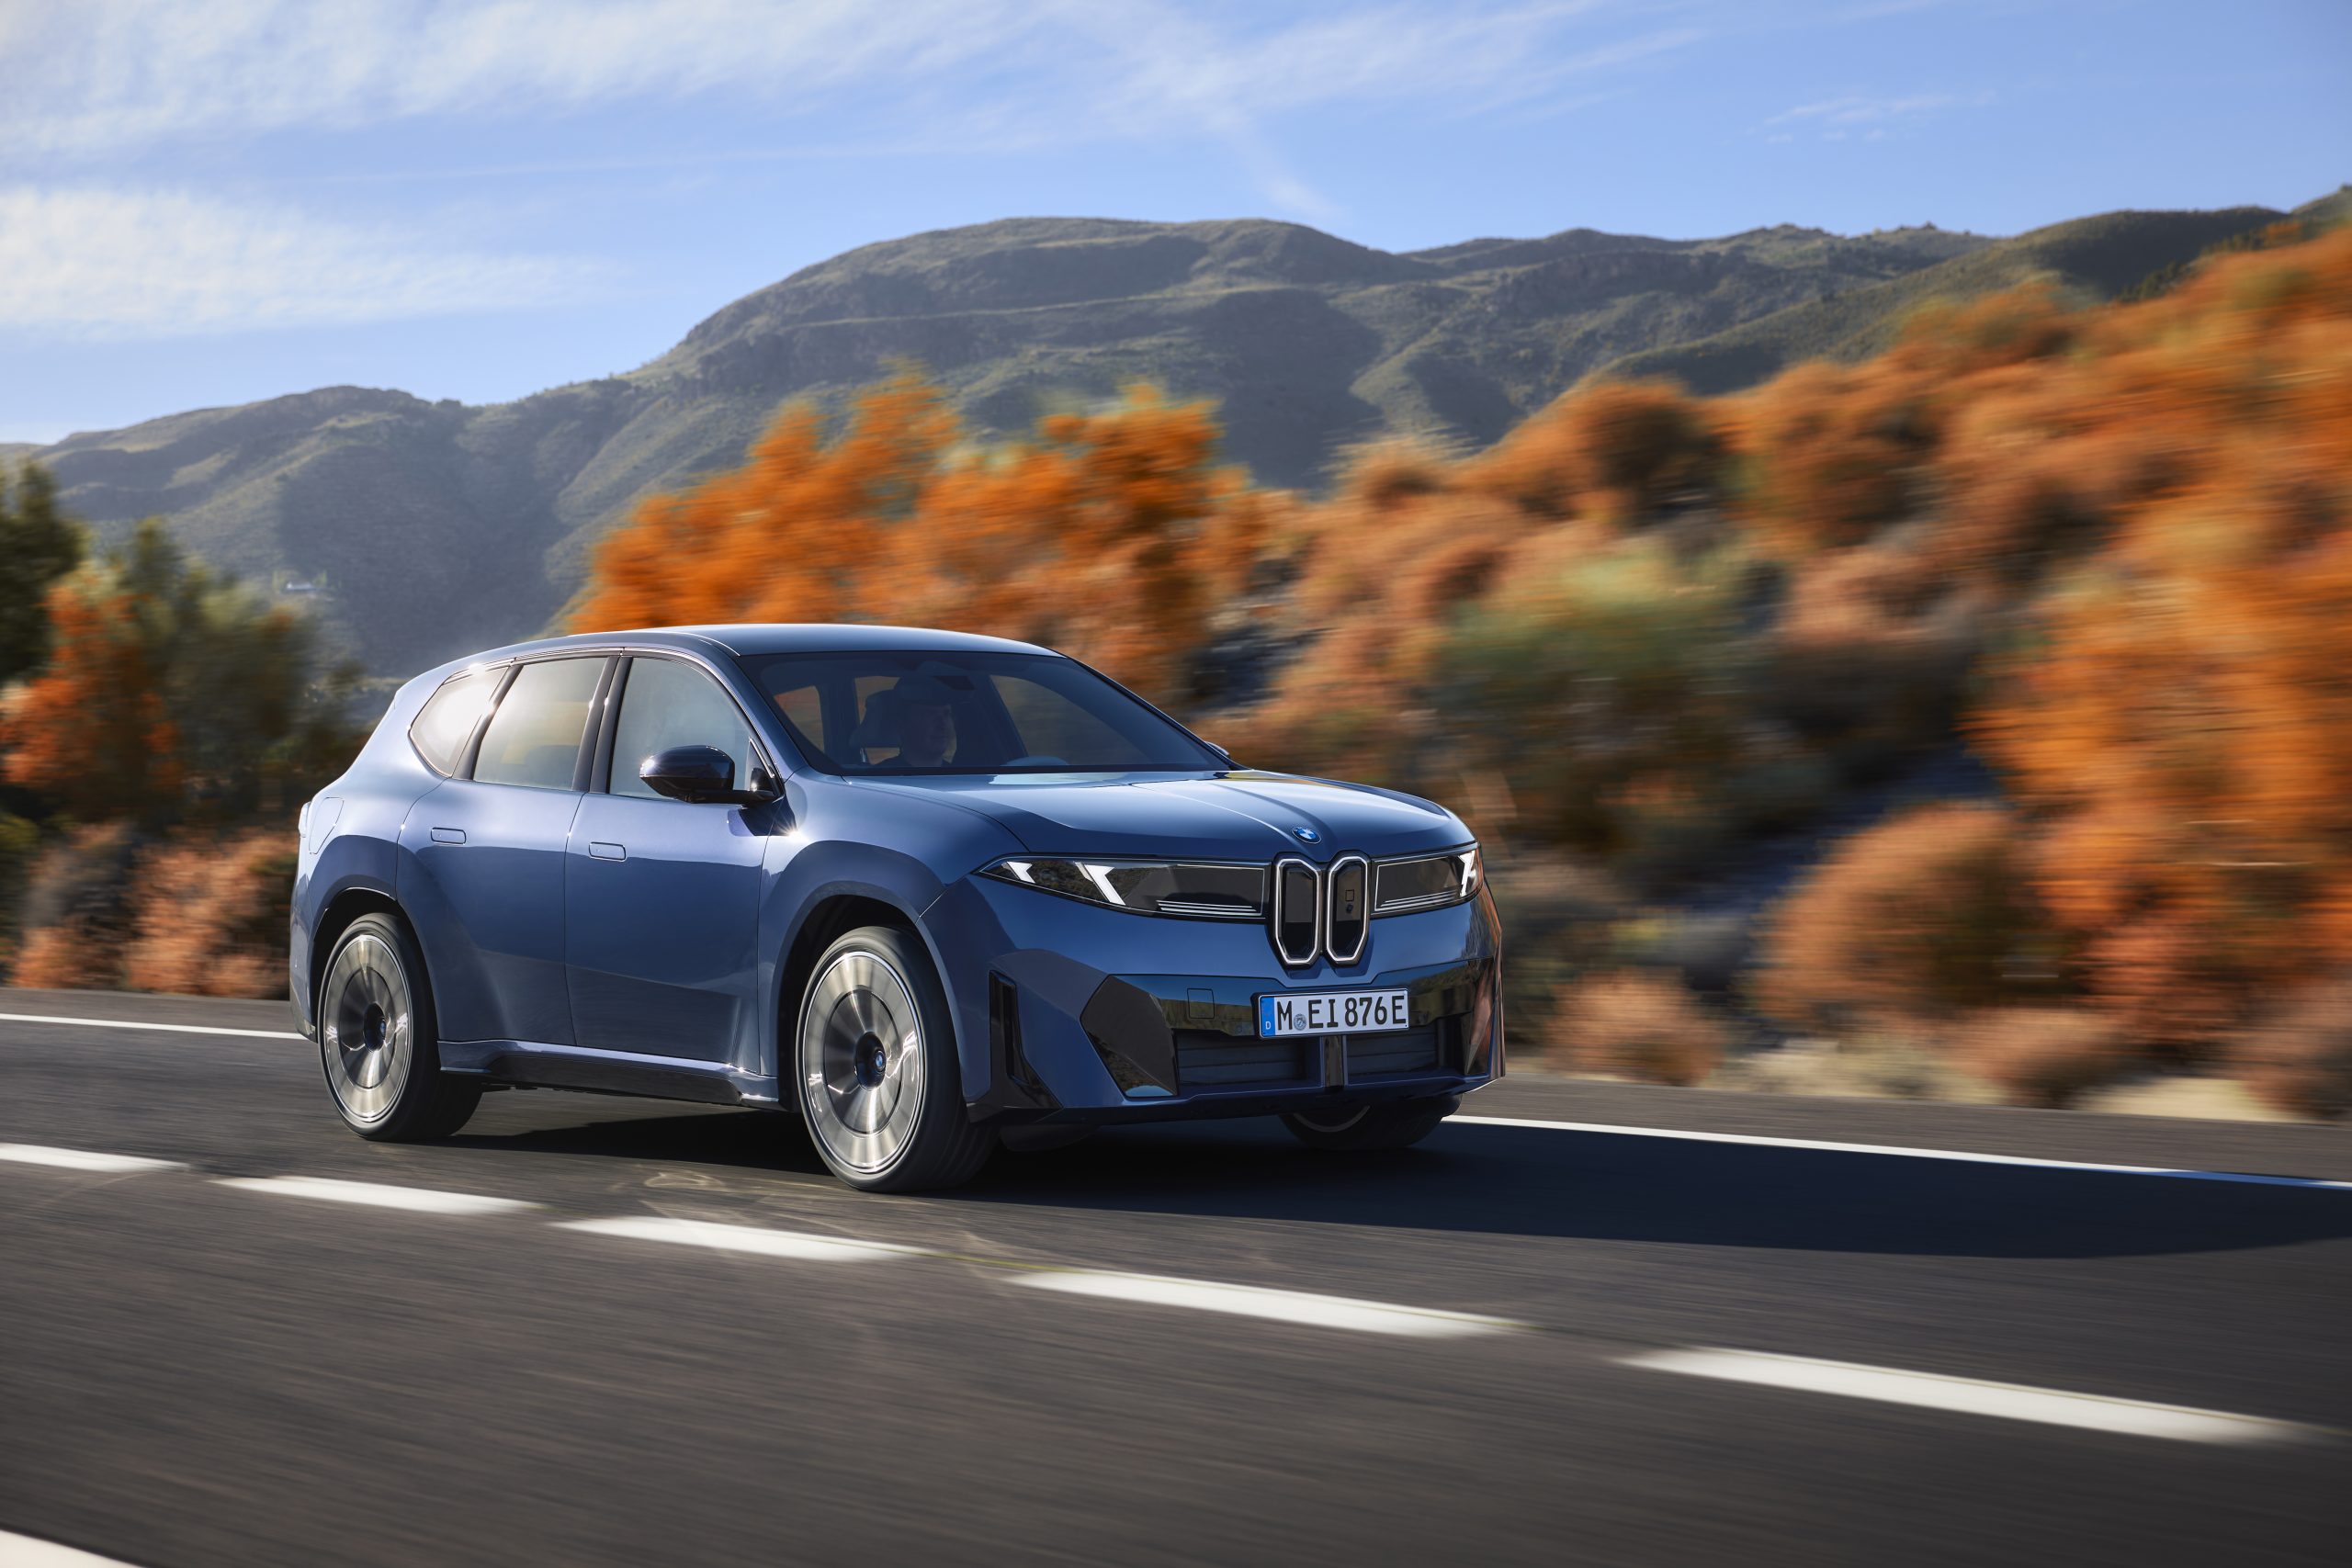
BMW has unveiled the Neue Klasse in Munich, marking its biggest investment to date and a new era of electrification, digitalisation and sustainable design.

A divide has opened in the tech job market between those with artificial-intelligence skills and everyone else.