

Americans Are Still Spending Like There’s No Tomorrow
Concerts, trips and designer handbags are taking priority over saving for a home or rainy day
 4 min
Consumers should be spending less by now.
Interest rates are up. Inflation remains high. Pandemic savings have shrunk. And the labour market is cooling.
Yet household spending, the primary driver of the nation’s economic growth, remains robust. Americans spent 5.8% more in August than a year earlier, well outstripping less than 4% inflation. And the experience economy boomed this summer, with Delta Air Lines reporting record revenue in the second quarter and Ticketmaster selling over 295 million event tickets in the first six months of 2023, up nearly 18% year-over-year.
Economists and financial advisers say consumers putting short-term needs and goals above long-term ones is normal. Still, this moment is different, they say.
A tough housing market has more consumers writing off something they’d historically save for, while the pandemic showed the instability of any long-term plans related to health, work or day-to-day life. So, they are spending on once-in-a-lifetime experiences because they worry they may not be able to do them later.
“It’s not a regret-filled, spur-of-the-moment decision,” says Michael Liersch, who oversees a team of advisers as head of advice at Wells Fargo. “It’s the opposite of that, where I would regret not having done it.”
Liersch cautions that it’s too soon to say whether the spate of spending is a fleeting moment or a new normal. And consumers remain frustrated about inflation as the price of many goods remains significantly higher than a few years ago.
Ibby Hussain, who works in marketing for a financial communications firm, says the Brooklyn, N.Y., apartment he and his fiancée rent for $3,000 a month would cost a million dollars to buy. At current rates, that means around $5,000 a month after a $200,000 down payment, not including property taxes. “And it’s not even that nice of an apartment.”
So, instead of saving for a down payment like he expected to after turning 30 and getting engaged in the past year, he splurged.
First, he bought a $1,600 Taylor Swift Eras Tour ticket and then he spent $3,500 on a bachelor party trip to Ibiza, Spain.
“I might as well just enjoy what I have now,” he says.
A travel boom
Ally Bank, whose online platform started allowing customers to create savings buckets for different goals in 2020, says users create about one-and-a-half times more experience-oriented buckets such as travel and “fun funds” versus those associated with longer-term planning.
Lindsey and Darrell Bradshaw went into credit-card debt to finance a vacation to Maui this past spring. The couple booked the trip only a few weeks after Lindsey, 37, quit her job to be a full-time caregiver to their 8-year-old son, who has special needs.
“We did not have the money and we were like, ‘Let’s just do this anyway,’ ” says Darrell Bradshaw, a 39-year-old general contractor in Seattle.
The trip cost about $10,000, including three, $1,000 last-minute plane tickets, 10 nights at a $385-a-night 4-star resort and several elaborate meals.
Even though the family decided to cancel subscriptions and cut back on dining out to help offset the bill, they say they have no regrets—especially since they got to see Lahaina just a few months before it was decimated by deadly wildfires.
Fears about a changing climate are driving some people to try to see places before they’re gone. In a monthly Deloitte survey of 19,000 global consumers, climate change was the only topic among 19 different concerns that respondents reported feeling significantly more worried about over the past year.
Josh Richner says he greatly lowered his retirement contribution to afford a cross-country trip that included a $7,000 Alaskan cruise so his family could see the ice caps, which have been melting at a rapid clip.
“I’ve never spent that much on a trip before,” says the 35-year-old, who says the splurge was also motivated by the pandemic and a health scare.
About six months ago, Richner and his wife decided to sell their Columbus, Ohio, home to travel the country with their two young children. Working for National Legal Center, a law firm that helps consumers resolve debt, he knows the potential consequences of living in a way that gives priority to the present. But he isn’t worried.
“I just hit a point where the thing that we had been talking about maybe hopefully doing some day, we’re going to do it now,” he says. “I’m not going to worry about money anymore. I don’t have it in me.”
Splurge purchases
Consumers might not be able to keep splurging forever. Labour strikes and student loan repayments could both lead people to pull back. Rising gas prices could also deter travel.
For those who study spending, however, the robustness up to this point has been a surprise.
In the New York Federal Reserve Bank’s August SCE Household Spending Survey, households reported spending 5.5% more than last year. The share of households that said they made at least one large purchase in the previous four months increased to 64% from 57%, its highest reading since August 2015.
“Normally at a time when you have higher inflation, but also higher interest rates, you don’t expect spending to hold up so well,” says Wilbert van der Klaauw, an economic research adviser on household and public policy at the Fed.
Rather than funnel all their spare change into a house or retirement account, Candice and Jasmine Kelly started a bucket-list fund after attending back-to-back funerals a few months ago. The couple adds a few hundred dollars from their paychecks each month into the fund, which they have used to try fancy restaurant tasting menus and buy Jasmine her dream designer handbag.
Instead of waiting to have fun when they retire, Candice, a 26-year-old management analyst in Charlotte, N.C., says the couple is trying to do the opposite. They want to enjoy their money while they’re young—even if it means working longer.
“All the rules that exist around money and lifestyle are just things people made up, so we’re playing a different game, and honestly I think we’re having more fun,” says Candice.
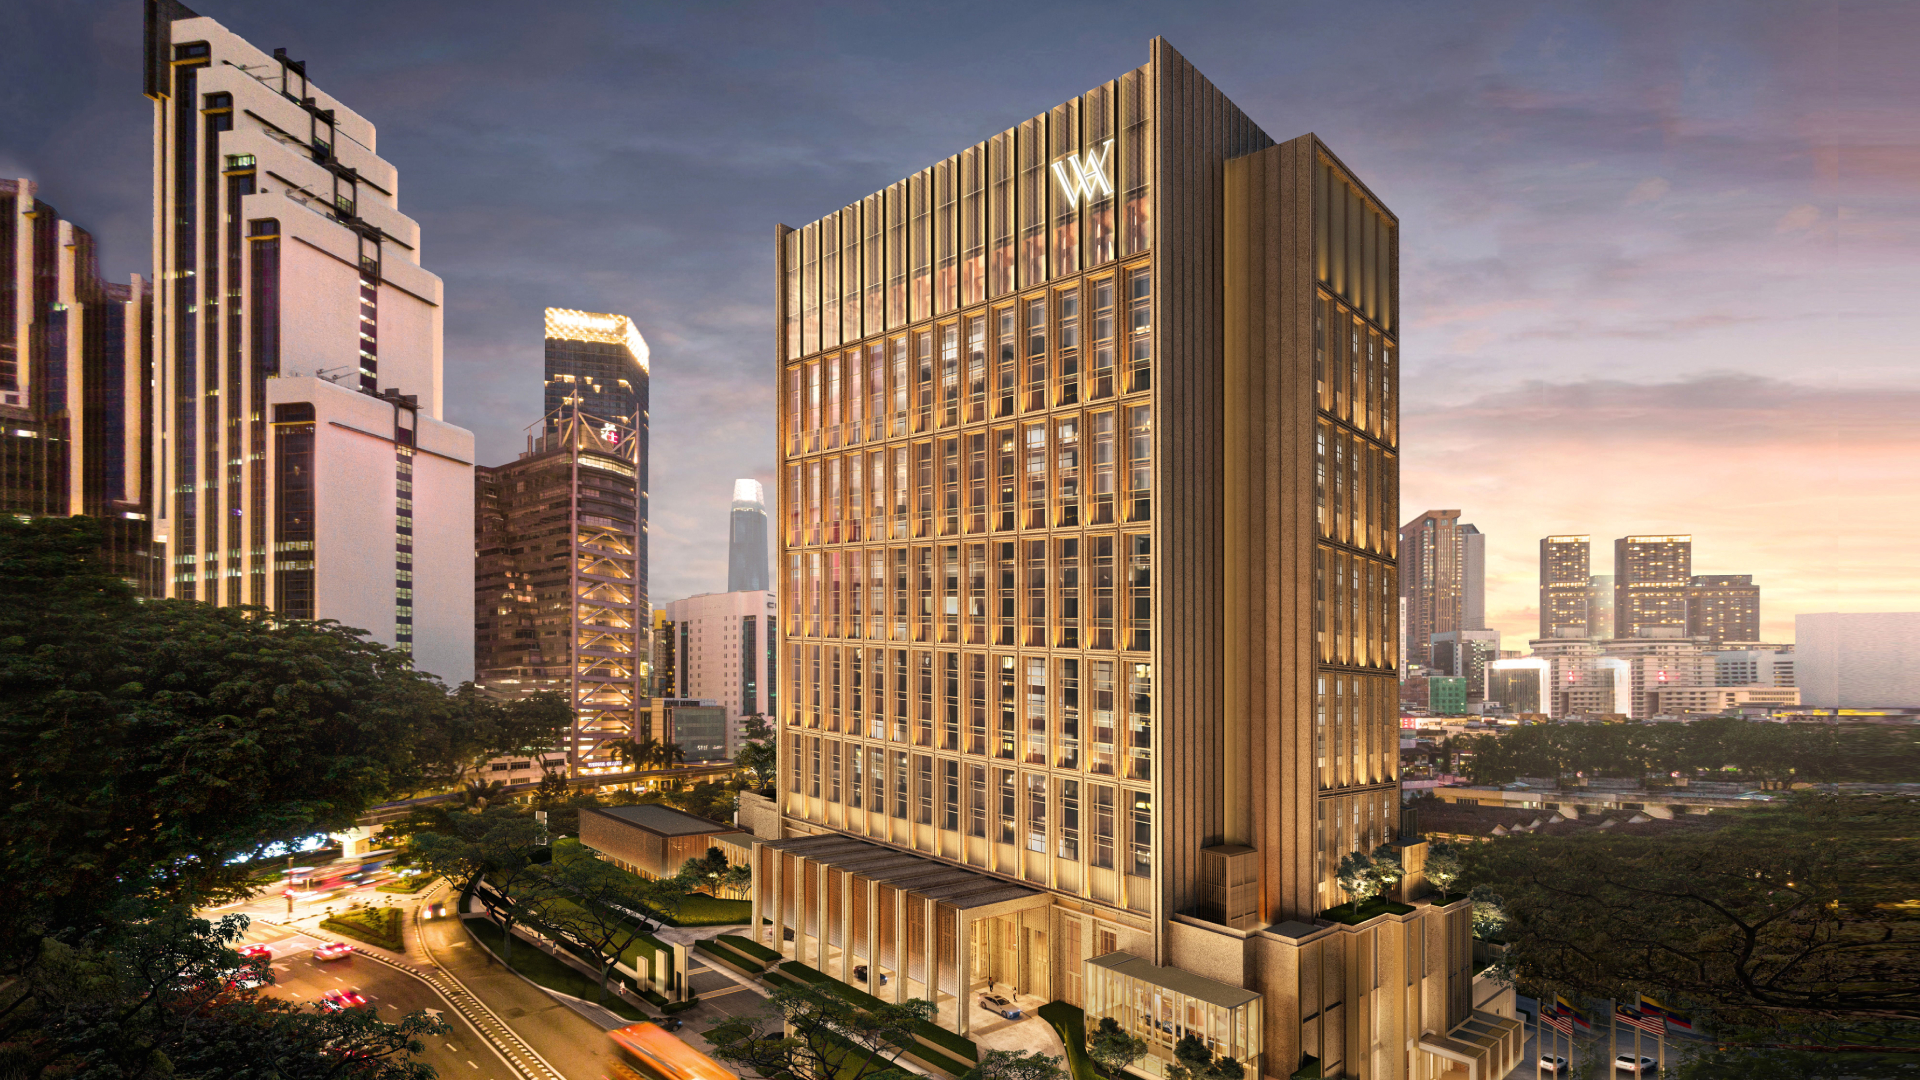
Waldorf Astoria Kuala Lumpur is scheduled to open on 30 October, introducing the Hilton luxury brand to Malaysia with an all-suite hotel in the city’s Golden Triangle.
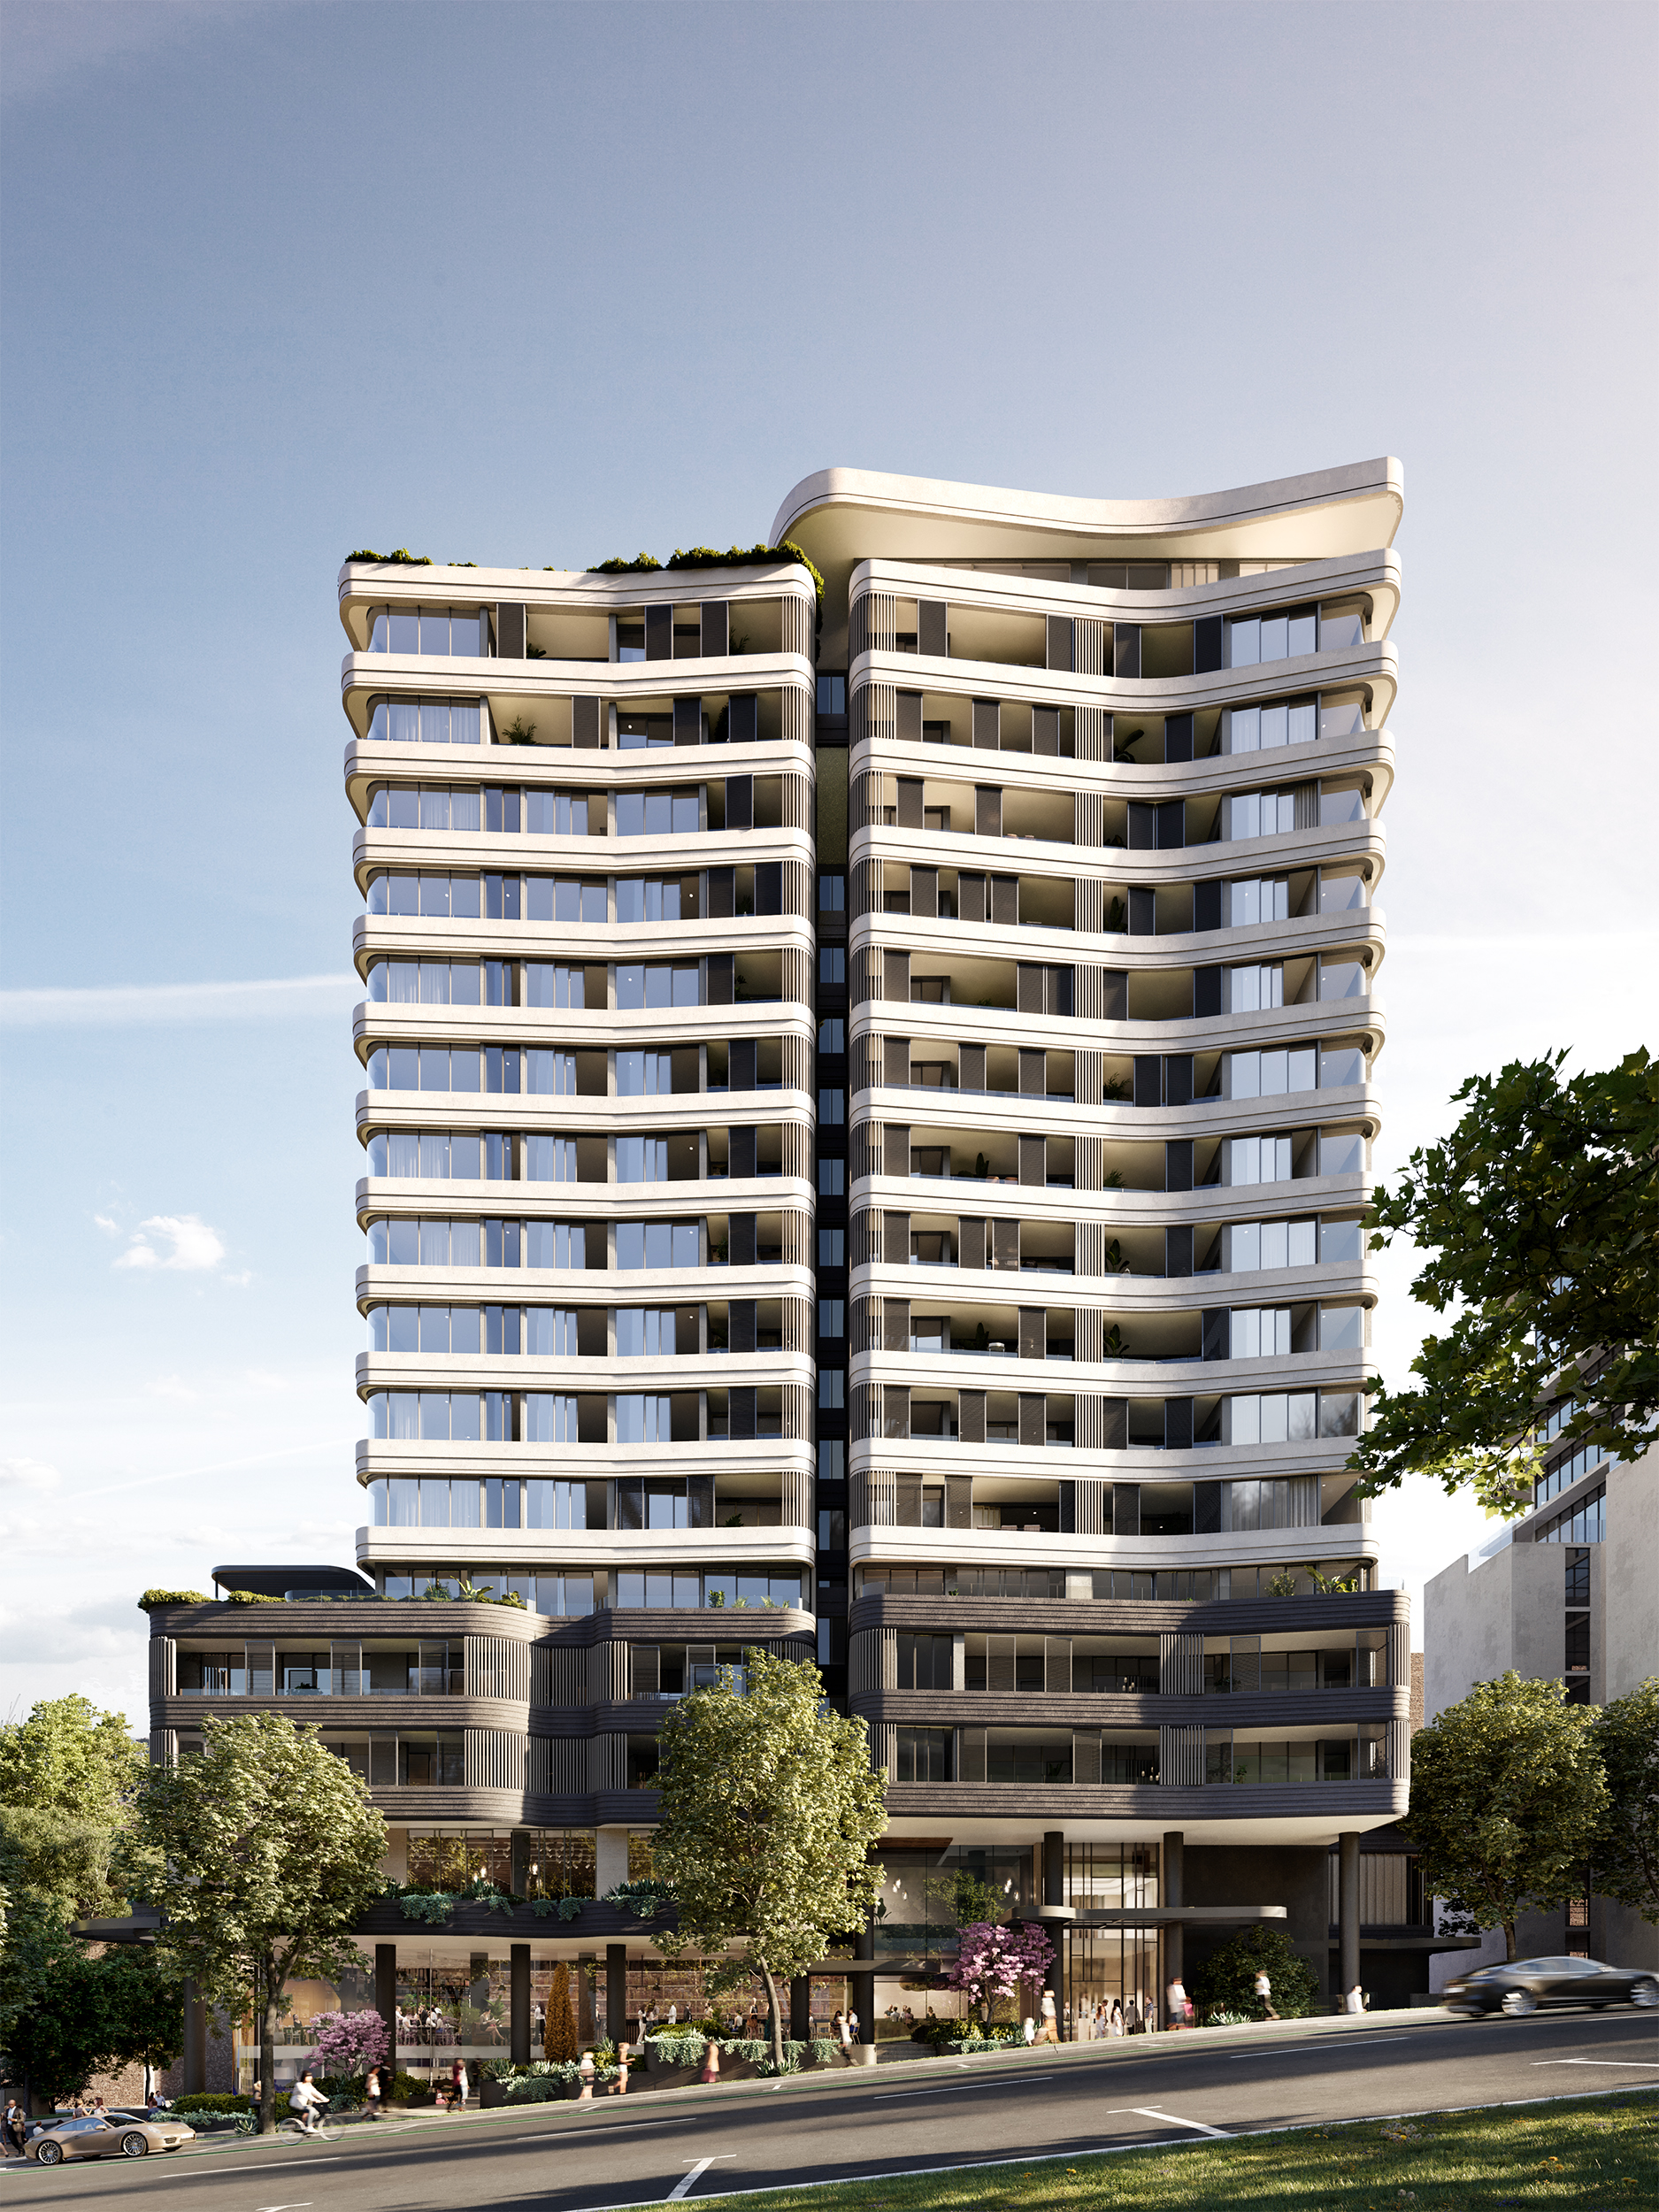
Located steps from Crows Nest Metro, the near-complete development brings luxury living to Sydney’s Lower North Shore.
Employment fell by 39,300 and unemployment held at a revised 4.7 per cent, giving the RBA more room to pause in November.
2 min
Australia’s labour market weakened in September, reducing—but not eliminating—the case for another Reserve Bank rate rise in November.
The seasonally adjusted unemployment rate was 4.7 per cent, according to the Australian Bureau of Statistics. August was revised to the same level, while September employment fell by 39,300 people. The number of unemployed Australians increased by 8,900 to 732,000.
The weakness extended beyond the headline rate. The employment-to-population ratio fell 0.3 percentage points to 63.6 per cent, participation declined 0.2 points to 66.8 per cent and underemployment edged up to 6.3 per cent. Part-time employment fell by 73,700, partly offset by a 34,400 increase in full-time work.
For the RBA, this is a clearer sign that restrictive monetary policy is cooling demand. Higher unemployment and falling employment reduce wage pressure over time and increase the risk that another rate rise would push the economy harder than necessary.
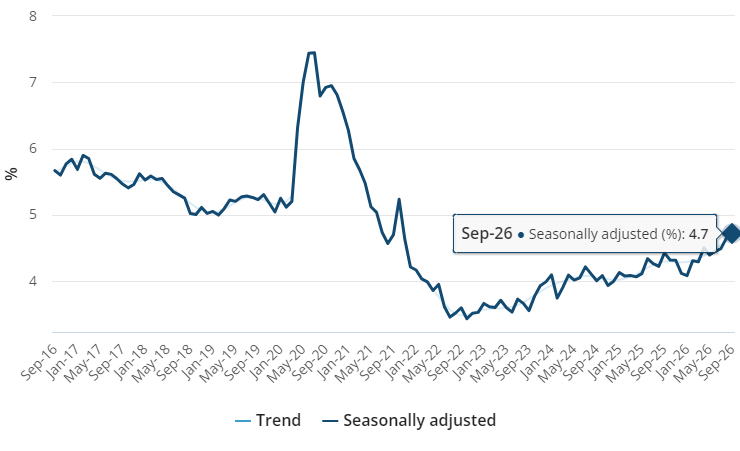
That makes a November increase less certain. It does not make a hold inevitable. The RBA must balance labour-market softness against inflation, and the September-quarter consumer price index due later in October will carry more direct weight in the decision.
For mortgage holders and property investors, the practical conclusion is not to trade one data release. Borrowers should continue testing repayments at higher rates, preserve liquidity and avoid basing a purchase on an assumed near-term reversal. Refinancing decisions should be assessed against total cost, not simply the advertised rate.
Property markets may initially welcome a reduced probability of another increase because borrowing capacity and sentiment are highly rate-sensitive. But a weakening labour market is not unambiguously positive for housing: job security supports mortgage serviceability, rental demand and buyer confidence.
The September numbers have given the RBA a credible reason to wait. Inflation will determine whether it can use it.
As housing drives wealth and policy debate, the real risk is an economy hooked on growth without productivity to sustain it.

Two coming 2027 models – the first of the “Neue Klasse” cars coming to the U.S. early next year – have been revealed.