





As Chinese Tastes Change, Farmers Everywhere Rip Up and Replant
The windfall is transforming entire regions, but some are starting to worry: What if China stops buying?

 4 min
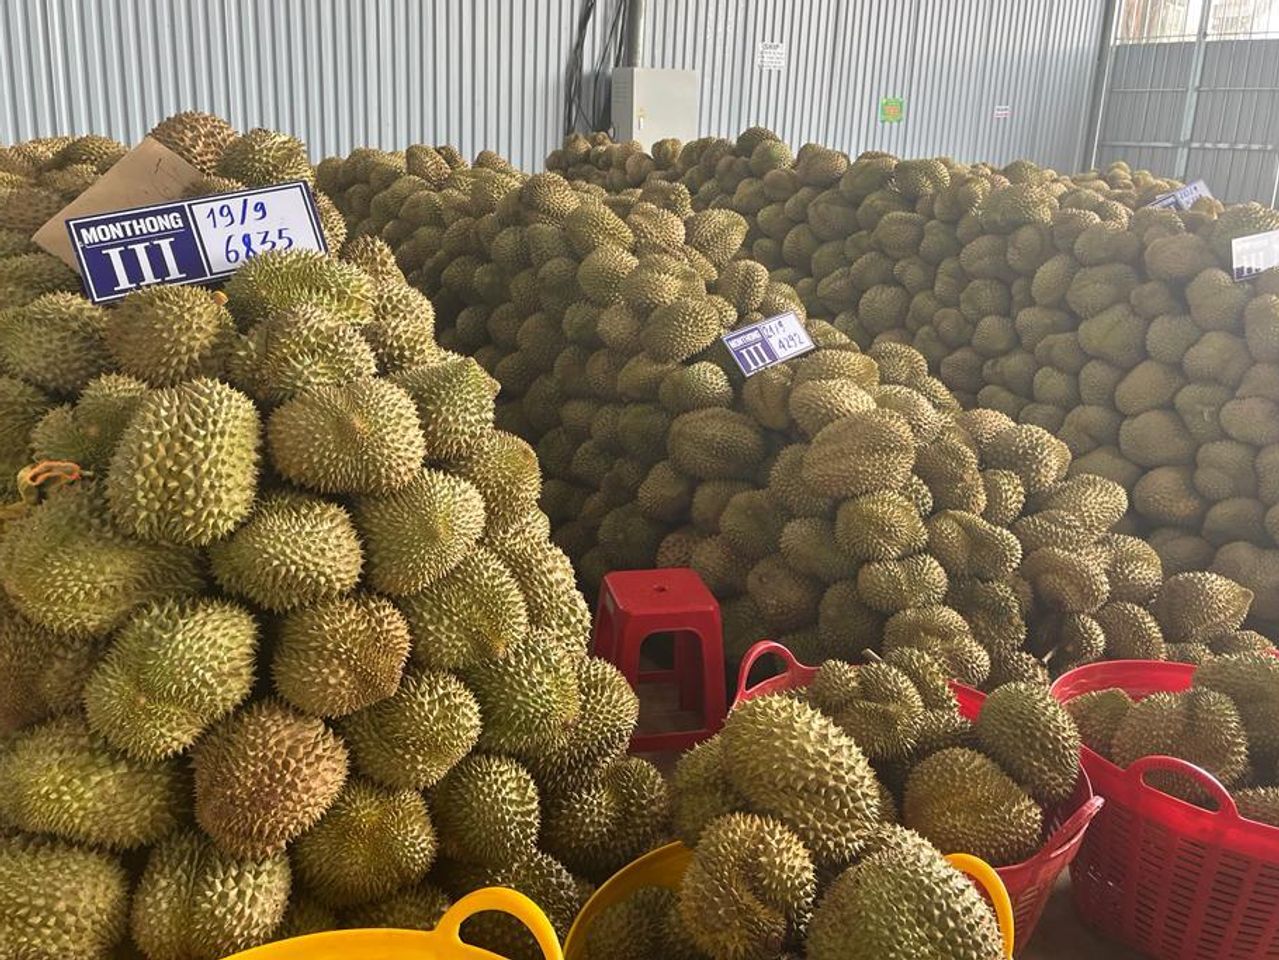
EA YONG, Vietnam—In the verdant highlands of central Vietnam, warehouses the size of airplane hangars dominate small farming towns, bristling with mounds of tropical fruit. The bounty is destined for a colossal market: China.
Farmers are felling coffee trees traditionally grown in this cool hilly region to plant spiky durians, pungent fruits that have become wildly popular in China. They are reaping the windfall to buy new irrigation systems, pay off loans and build shiny marble facades to their homes.
“We locals aren’t just doing well, we can even be considered rich,” said Pham Van Trung, 54, as he ate a late lunch of pork and rice wine. Trung made $81,000 this year selling durian, and said the region was swarming with Chinese buyers.
China’s appetite for foreign produce has grown in recent decades along with the wealth of its consumers. The amount of food the world’s second most populous nation imports has risen to over $200 billion a year—more than any other country—from about $15 billion two decades ago, according to the World Trade Organization. Avocado farmers in Kenya, shrimp cultivators in India, soy producers in Russia and banana growers in Cambodia are all cashing in.
While economic growth in China has slowed recently and its population is shrinking, demand for nutrient-rich foods such as beef and tropical fruit has remained high.
Last year, the Chinese noshed through more than 800,000 metric tons of imported durian and nearly six million metric tons of imported meat—both world-leading totals. It bought 90 million metric tons of soybeans from overseas last year, accounting for roughly 60% of global trade, for use in making tofu and to feed the country’s hundreds of millions of pigs.
Feeding China’s massive middle class presents a historic opportunity for countries seeking to boost the incomes of people in poor, rural areas. But it also poses a quandary: how to tap in to its huge market without becoming dependent on a trade partner that can be fickle.
In recent years, China has restricted imports of Norwegian salmon, Taiwanese pineapples, Philippines bananas and Australian lobsters. It usually cites contamination, pests or issues with quality—but Beijing’s curbs have also often coincided with political disputes.
China slapped hefty antidumping duties on Australian wine exports in 2020 after Australia called for an independent probe into the origins of Covid-19. In 2012, China halted purchases from banana growers in the Philippines, saying mealybugs had been discovered in shipments, after a flare-up between the countries in the South China Sea.
“With the size of the Chinese economy, it can always use trade to punish an exporter,” said Yun Sun, director of the China program at the Stimson Center, a think tank in Washington, D.C. Selling to China is “an opportunity, and it is a risk,” she said.
The risk is higher because when the chance to export to China’s massive market opens up, often entire agricultural belts go all in. This can lead to what Sun calls “singularification,” or the concentration of a local economy around one product, making it vulnerable to disruption.
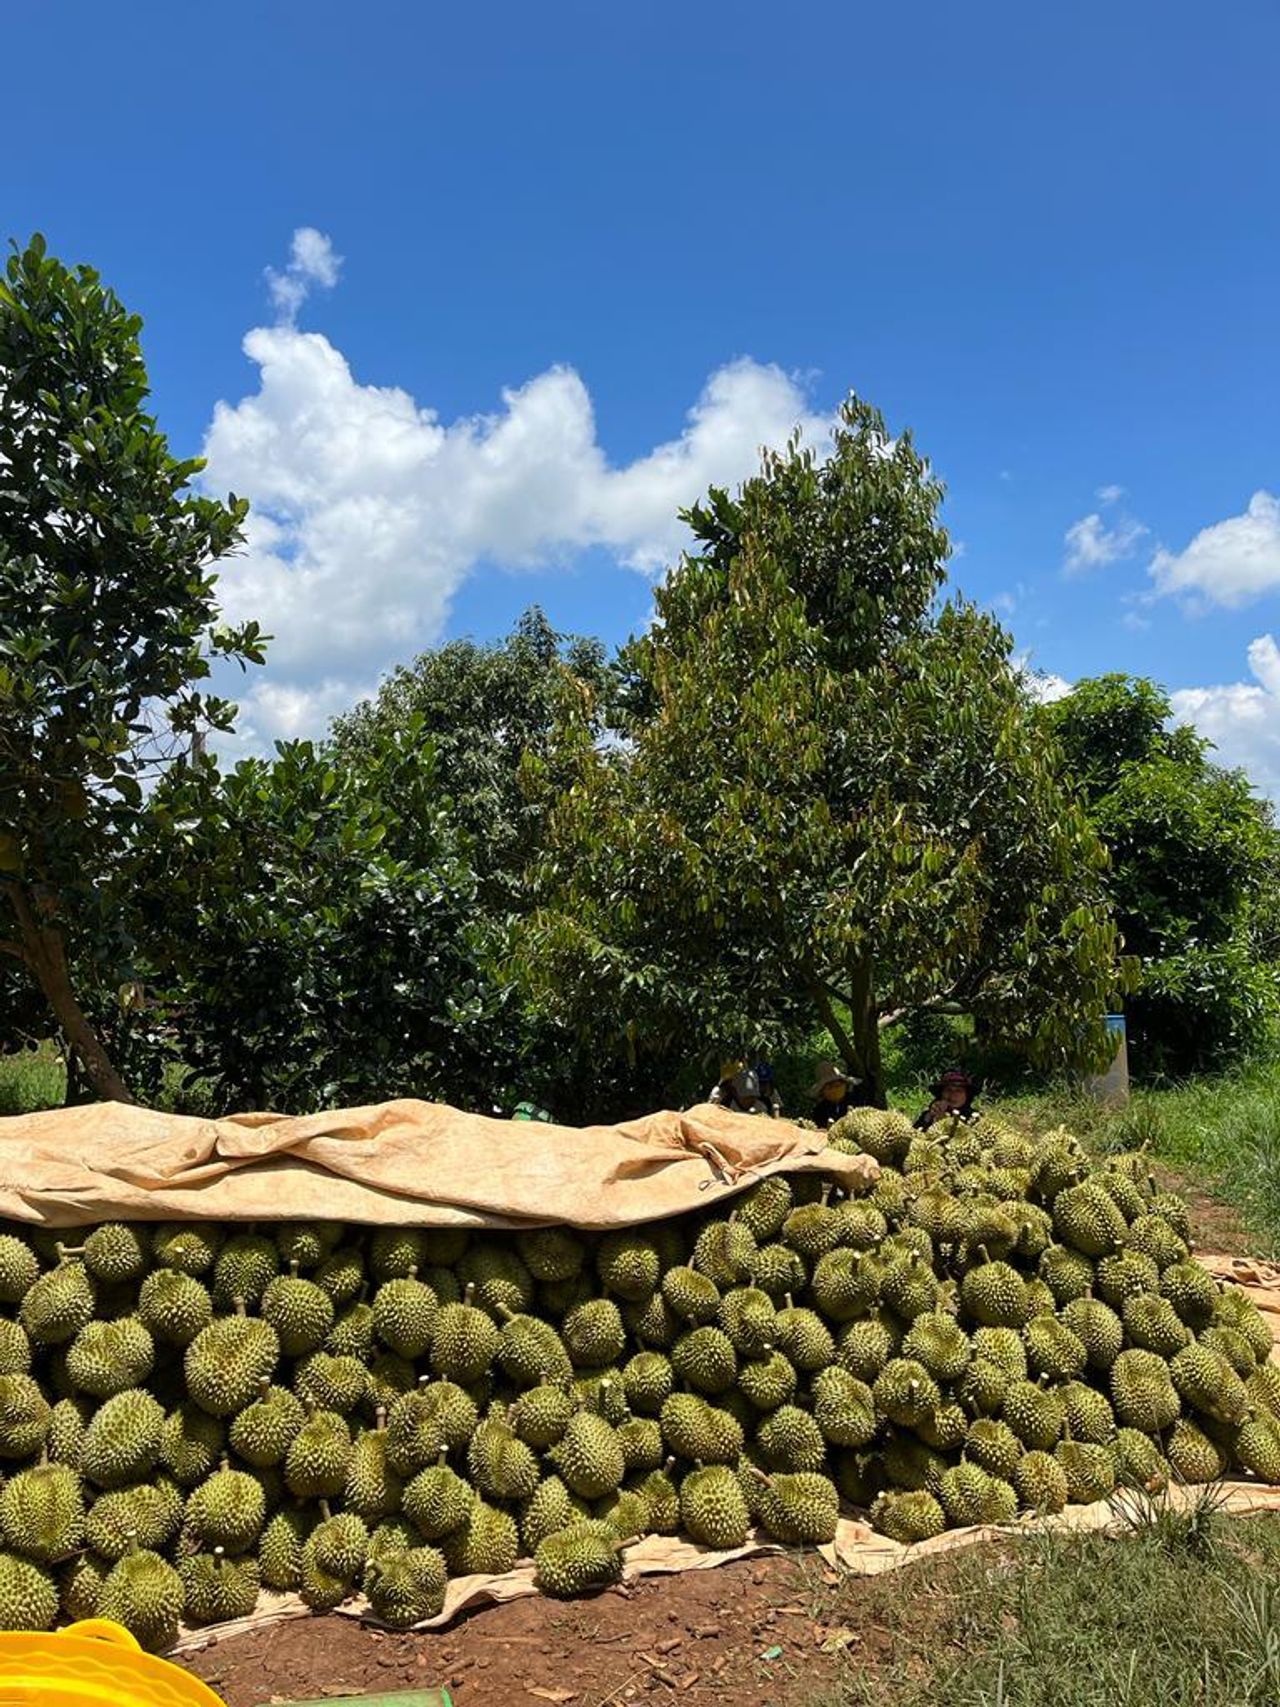
That is what appears to be happening in Vietnam’s central highlands. The region is famed for its Robusta coffee, which is sold around the world. But last year, Beijing opened the gates to large-scale imports of Vietnamese durian—and farmers here began uprooting their coffee crops. Traders flocked to snap up the produce, causing local prices to more than double this year.
Be Duc Huynh, a 26-year-old farmer who got rid of his entire coffee crop, said he makes about five times as much from a hectare of durian as he earned from coffee. He harvested four tons of durian this year, up from one ton last year—all of it destined for China.
China buys around 90% of durian exports from Vietnam, which also sells much of its dragon fruit, bananas, mangoes and jackfruit to its giant neighbour. In recent months around 60% of Vietnam’s fruit and vegetable exports have gone to China, up from one-third a decade ago, according to official figures compiled by data provider CEIC.
During the autumn harvest time, the village air carried the sharp smell of the fruit. Families stacked mounds of durian in front of their homes to entice traders, who thwacked the durian shells with knife handles to test for quality. Hard means it is too young; soft means it is ripe and can sell for a higher price.
On a recent afternoon, durian trader Nguyen Thai Huyen dug into the flesh with her painted-pink fingernails, tasting bits of durian to determine their ripeness. Huyen posts snappy videos on TikTok of her visits to plantations and the mountains of durian she has on offer.
“A few years ago people considered durian a crop to reduce poverty,” she said. “Now it is the million-dollar crop.”
She has tried selling to Japan, but said buyers there only take small amounts. She isn’t especially worried about being too reliant on China, though. She says durian’s popularity has room to grow in the country, where many are still unfamiliar with the fruit.
Vietnam’s government is less certain. Earlier this year the agriculture ministry issued a warning about what state media called reckless durian cultivation, saying many farmers were abandoning traditional crops such as coffee and rice and planting durian in areas unsuited to it. Agriculture experts cited in state media have encouraged farmers to develop alternative markets to China and try to sell more of their produce locally.
Traders say that is easier said than done. The fruit has few takers outside of the region, and recent high prices put durian out of reach of many local Vietnamese.
Still, farmers say they want to be careful. In September, some fruit exports including durian were halted after Beijing complained about mealybugs and other pests. It reminded farmers of a major disruption in January 2022 when truckloads of Vietnamese produce rotted after China sealed off its southern border to contain the spread of Covid-19.
H’Meng, a farmer who goes by one name, has planted hundreds of durian trees in recent years. Now, she said, she is planning to grow more coffee. The prices are more stable, she said, because the market for coffee isn’t focused on one nation.
“I’m worried about becoming too dependent on China,” she said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

Three-Michelin-starred chef Massimiliano Alajmo will host an intimate Mediterranean sailing aboard Crystal Serenity, redefining fine dining at sea.
From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.


