

Energy and Materials Lift the ASX From Three-Month Low
The ASX 200 rose about 0.27% as energy and materials advanced. Woodside and gold miners gained while financials and technology weakened.
 2 min
The Australian sharemarket rebounded from its lowest close in three months on Wednesday, with energy and materials companies leading a cautious recovery.
The S&P/ASX 200 finished approximately 23 points, or 0.27 per cent, higher at 8,695.6 on 16 September. A second data source placed the closing index at 8,696.5, up 24 points or 0.28 per cent. The official close should be confirmed through a licensed feed before publication.
The broader All Ordinaries added 25.2 points, or 0.28 per cent, to 8,874.5.
Energy was the strongest sector, rising 2.19 per cent as Australian producers reflected the previous overnight increase in global oil prices. Woodside gained 2.84 per cent. Brent had settled near US$108.75 a barrel before the local session, although it later traded around US$107.68.
Materials advanced 1.28 per cent and provided the largest positive contribution to the index. Gold producers featured prominently among the strongest stocks, with Pantoro rising 9.3 per cent and St Barbara gaining 8.18 per cent. BCI Minerals added 7.48 per cent.
Financials fell 0.37 per cent, detracting from the benchmark despite earlier strength. Rate expectations remained a significant influence after Westpac joined the other major banks in forecasting a possible Reserve Bank increase in November. Higher rates can expand bank margins in some circumstances but also raise funding costs and increase the risk of loan stress and slower credit growth.
Technology remained weak. Life360 declined 5.46 per cent, while healthcare names that had rallied during Tuesday’s sell-off gave back ground. 4DMedical lost 5.35 per cent and Telix Pharmaceuticals fell 4.96 per cent.
James Hardie dropped 5.23 per cent. Codan moved against the weaker technology tone, gaining 7.51 per cent.
The session produced positive breadth, with more advancers than decliners among the largest 250 stocks, but the broader backdrop remains unsettled. Oil prices have revived inflation concerns, bond yields are elevated and investors are assessing the prospect of further monetary tightening in Australia and the United States.
The rebound therefore recovered only part of Tuesday’s 0.9 per cent decline. For Thursday, investors will be watching overnight central-bank developments, energy markets and whether gains can broaden beyond resources.
Market dashboard — 16 September 2026
S&P/ASX 200* Approximately 8,695.6, up 23.1 points or 0.27 per cent; verify the official closing print
All Ordinaries: 8,874.5, up 25.2 points or 0.28 per cent
Best-performing sector: Energy, up 2.19 per cent
Materials: Up 1.28 per cent
Weak sector: Financials, down 0.37 per cent
Leading mover: Pantoro, up 9.30 per cent
Notable large-cap mover: Woodside, up 2.84 per cent
Notable loser: Sunrise Energy Metals, down 6.22 per cent
Life360: Down 5.46 per cent
Australian dollar: About US71.3 cents in the preceding market snapshot
Gold: Approximately US$4,375 an ounce in the afternoon snapshot
Brent crude: Approximately US$107.68 a barrel in the afternoon snapshot
Studio apartments have almost disappeared from new Australian developments. Lura is bringing them back to Burleigh Heads from $495,000.
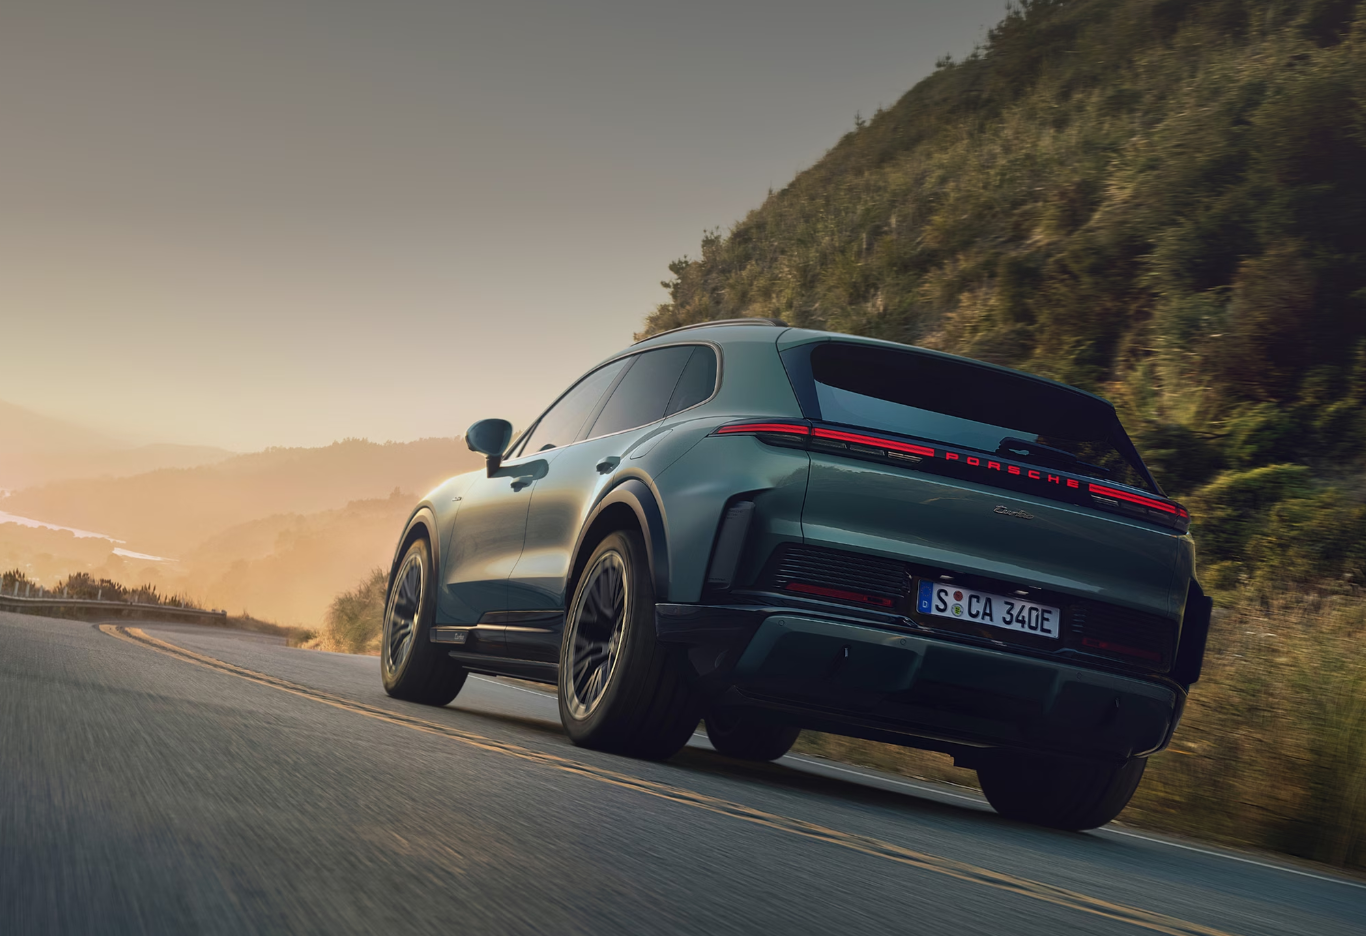
Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.
The ASX 200 gained 0.4 per cent in the week ended 9 October as property and energy rose while technology and small caps declined.
5 min
Heavyweights Lift the ASX as Small Caps and Technology Fall Behind
The S&P/ASX 200 finished the week ended 9 October at 8,716.6, up 0.4 per cent, but the headline concealed a sharply divided market as listed property, energy and selected blue chips advanced while technology, iron ore miners and smaller companies fell.
Australia’s sharemarket finished the week higher, but the gain was less convincing than the index alone suggested.
The S&P/ASX 200 closed Friday, 9 October at 8,716.6, gaining 0.4 per cent over the five trading sessions. The broader All Ordinaries added 0.26 per cent to 8,877.7. By contrast, the Small Ordinaries fell 1.34 per cent to 3,281.9, showing that the market’s progress relied heavily on larger, more liquid companies rather than a broad increase in investor confidence.
The index’s path was uneven. It edged up on Monday, rose 0.57 per cent on Tuesday, slipped 0.09 per cent on Wednesday and lost 0.77 per cent on Thursday before recovering 0.64 per cent on Friday.
That final-session rise of 55.7 points allowed the benchmark to finish the week in positive territory and brought it approximately back to break-even for the calendar year.
The strongest sector was listed property, which gained 3.73 per cent. The move was visible in Goodman Group, one of the market’s largest property securities, which rose 4.82 per cent across the week based on adjusted closing prices.
A-REITs remain sensitive to movements in global bond yields, funding costs and asset valuations, so the sector’s strength indicated a meaningful rotation towards income-producing real assets. It did not eliminate the longer-term questions surrounding office demand, asset valuations, development pipelines or refinancing costs.
Energy gained 2 per cent as Brent crude finished the week around US$101.42 a barrel, up approximately 0.85 per cent. Woodside Energy rose 3.46 per cent over the week, although the sector was far from uniform.
Uranium shares came under pressure on Friday, with several names falling sharply. That demonstrated why a supportive move in the energy index should not be interpreted as a universal signal for every energy commodity or producer.
Technology was the weakest major sector, declining 1.97 per cent over the week despite a substantial rebound on Friday. Pro Medicus, WiseTech Global and Life360 all rallied in the final session after suffering sizeable drawdowns from their August levels. The late recovery softened the weekly damage without erasing the market’s broader caution towards higher-valuation growth shares.
Materials also struggled. BHP fell 0.44 per cent over the week, Rio Tinto lost 1.48 per cent and Fortescue declined 5.25 per cent. The size of those companies meant their weakness offset part of the support supplied by property, energy and healthcare.
The banks were another drag. Commonwealth Bank fell 1.43 per cent, Westpac declined 1.75 per cent, National Australia Bank lost 2.13 per cent and ANZ eased 0.51 per cent.
Macquarie Group moved in the other direction, gaining 1.12 per cent. With the major banks representing an unusually large share of the Australian index, even modest simultaneous falls can materially restrain the benchmark.
Healthcare provided some of the strongest large-cap performances. CSL rose 4.84 per cent and ResMed gained 2.49 per cent. General insurer QBE advanced 5.63 per cent, making it the strongest performer among the 20 large-cap companies tracked below.
Consumer-facing companies also contributed. Woolworths rose 3.23 per cent, Coles gained 1.22 per cent and Wesfarmers added 1.48 per cent. Aristocrat Leisure finished 2.91 per cent higher. Those gains helped balance the losses across the banks and diversified miners.
How the ASX’s top 20 moved
The following figures compare adjusted closing prices on Friday, 2 October with Friday, 9 October. Percentages have been rounded to two decimal places.
The top 20 is based on the largest-company framework used for this wrap. Rankings can change with share prices, index reviews and corporate actions.
Commonwealth Bank (CBA): Down 1.43 per cent, from $151.45 to $149.29.
BHP Group (BHP): Down 0.44 per cent, from $61.21 to $60.94.
Westpac Banking Corporation (WBC): Down 1.75 per cent, from $34.32 to $33.72.
National Australia Bank (NAB): Down 2.13 per cent, from $38.50 to $37.68.
ANZ Group (ANZ): Down 0.51 per cent, from $37.37 to $37.18.
Wesfarmers (WES): Up 1.48 per cent, from $76.22 to $77.35.
Macquarie Group (MQG): Up 1.12 per cent, from $245.63 to $248.37.
CSL (CSL): Up 4.84 per cent, from $175.35 to $183.84.
Woodside Energy (WDS): Up 3.46 per cent, from $31.24 to $32.32.
Rio Tinto (RIO): Down 1.48 per cent, from $164.81 to $162.37.
Goodman Group (GMG): Up 4.82 per cent, from $25.91 to $27.16.
Woolworths Group (WOW): Up 3.23 per cent, from $38.35 to $39.59.
Telstra Group (TLS): Down 1.24 per cent, from $4.83 to $4.77.
Fortescue (FMG): Down 5.25 per cent, from $16.19 to $15.34.
Coles Group (COL): Up 1.22 per cent, from $23.03 to $23.31.
Northern Star Resources (NST): Up 1.54 per cent, from $24.02 to $24.39.
QBE Insurance Group (QBE): Up 5.63 per cent, from $23.81 to $25.15.
Aristocrat Leisure (ALL): Up 2.91 per cent, from $59.76 to $61.50.
ResMed (RMD): Up 2.49 per cent, from $31.79 to $32.58.
James Hardie Industries (JHX): Up 0.06 per cent, from $36.07 to $36.09.
The Top 20 results show why the overall index could advance despite weakness in the banks and miners. Eleven of the 20 companies finished higher, but more importantly, several of the gains were substantial.
QBE, CSL and Goodman rose close to or above 5 per cent, while Woodside and Woolworths advanced more than 3 per cent. Those moves countered falls across all four major banks and the three largest diversified iron ore exposures.
Fortescue was the weakest company in the group, down 5.25 per cent. National Australia Bank recorded the largest decline among the major banks, while Rio Tinto was the weaker of the two larger diversified miners after Fortescue.
It is important not to invent a company-specific explanation where none was confirmed. Some weekly movements reflected sector rotations, commodity prices, interest-rate expectations and changes in investor positioning rather than a fresh announcement by the company.
Where no material ASX announcement clearly explained the move, the percentage should be treated as market performance rather than evidence of a particular event.
Weekly market dashboard
Trading week: 5–9 October 2026.
S&P/ASX 200: 8,716.6, up 0.40 per cent.
All Ordinaries: 8,877.7, up 0.26 per cent.
Small Ordinaries: 3,281.9, down 1.34 per cent.
Best sector: Listed property, up 3.73 per cent.
Weakest sector: Information technology, down 1.97 per cent.
Energy: Up 2.00 per cent.
Brent crude: Approximately US$101.42 a barrel, up 0.85 per cent.
AUD/USD at Friday’s close: Approximately US69.81 cents.
Strongest tracked large cap: QBE Insurance, up 5.63 per cent.
Weakest tracked large cap: Fortescue, down 5.25 per cent.
What investors will watch next
The immediate question is whether the rally can broaden. A market supported by a handful of large companies can continue rising, but it is more vulnerable if those leaders reverse.
Improvement in the Small Ordinaries and technology sector would provide stronger evidence that investors are becoming comfortable taking risk beyond defensive and income-producing assets.
Oil remains another major variable. Prices above US$100 a barrel can support producers such as Woodside, but they also increase transport, manufacturing and household costs. That creates a complicated backdrop for inflation and interest-rate expectations.
Global bond yields, US earnings and local company announcements will also shape the coming week. For Australian investors, the concentration of the domestic market means movements in the banks, BHP, Rio Tinto, CSL, Wesfarmers, Goodman and Woodside can overwhelm an otherwise mixed session.
The week’s 0.4 per cent gain was constructive, but it was not a declaration that risk had disappeared. The more accurate reading is that investors favoured selected large companies, listed property, energy and defensive consumer names while remaining cautious about smaller companies, technology and iron ore exposure.
That distinction matters. An investor whose portfolio resembled the headline index may have finished ahead. Someone weighted towards smaller companies, technology or bulk miners may have experienced a very different week.
This article provides general information only. It does not constitute personal financial advice or a recommendation to buy, sell or hold any security. Market prices and index composition can change rapidly.
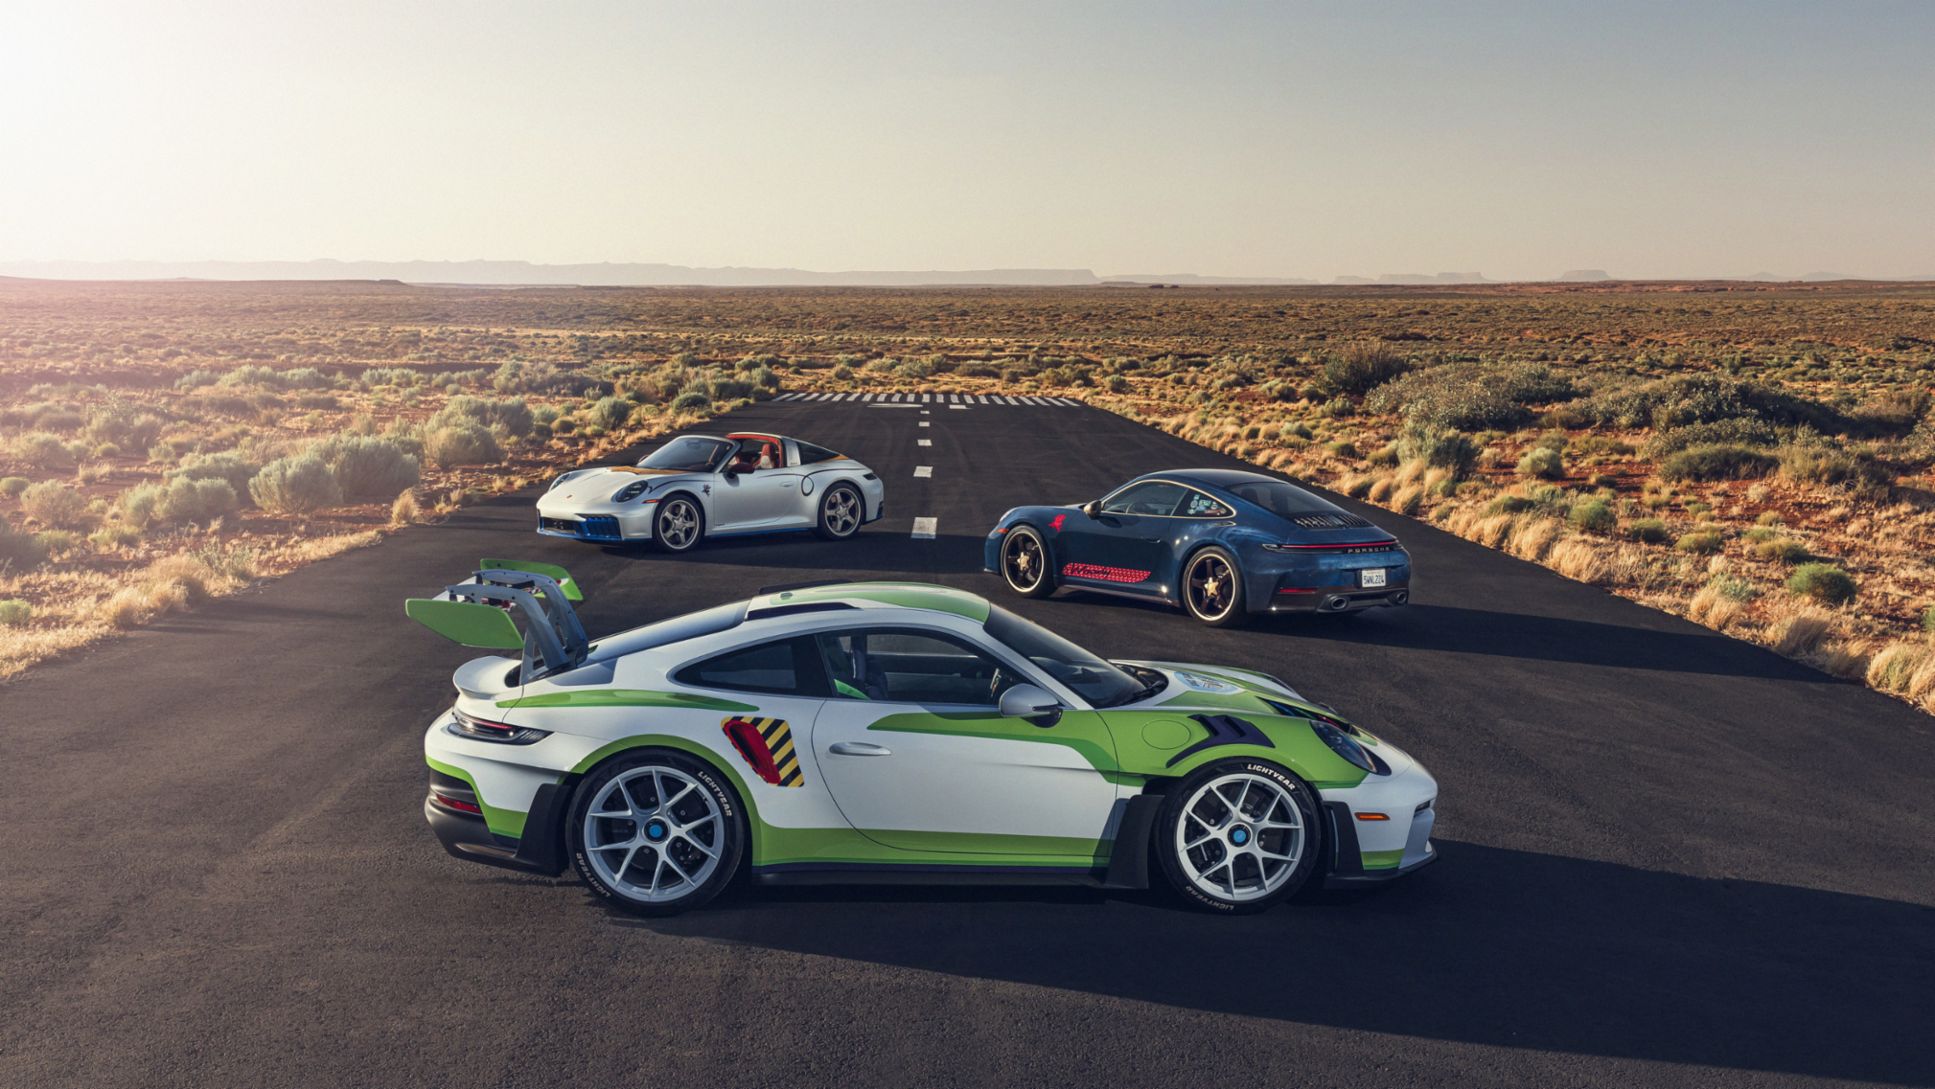
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation

A survey of people with at least $1 million in investable assets found women in their 30s and 40s look nothing like older generations in terms of assets and priorities