Britain Is Getting Back on Track
Successes in Ukraine and the Pacific and Rishi Sunak’s leadership shore up standing lost to Brexit and Covid.

 3 min
War in Europe, crisis in the Middle East, growing tensions across East Asia, and a widening chasm between a beleaguered West and the Global South: Writing a Global View column in times like these is not always the happiest of tasks. But at least one good-news story has been building quietly over the last few months. Global Britain is becoming a reality and the world is better off because of it.
The world has changed since the British voted to leave the European Union in 2016. After Brexit, enthusiastic backers expected an aggressively deregulating Britain would become a kind of Singapore-on-Thames. Russian oligarchs, Chinese moguls and Arab oil sheikhs would flock to London, eager to enjoy a sophisticated financial market that was less regulated and more hospitable than either the EU or the U.S. Free-trade agreements with the U.S. above all, but also fast-growing Asian nations, would more than compensate for the loss of the U.K.’s privileged position in the EU.
That’s not how things worked out, and the world is a much tougher place for middle powers than anyone expected when Brexit passed. Even as Covid disrupted the world economy and shut Britain’s lucrative tourism sector down, the open international economy of 2016 began to wither. Russia’s war in Ukraine and deepening U.S.-China tensions ended the dream that London could prosper as a neutral financial centre. Rising protectionism world-wide made trade agreements harder to reach and highlighted the importance of belonging to big trading blocs like the EU.
On top of this, a spat with the EU over the Northern Ireland Protocol, aimed at keeping the border with the Irish Republic open after Brexit, proved a much larger problem for Britain than Boris Johnson’s government anticipated. The details are fiendishly complicated, but in his rush to “get Brexit done,” Mr. Johnson signed an agreement with the EU that Unionist Protestants in Northern Ireland saw as weakening ties with Britain. The resulting tensions threatened the stability of the troubled region, and by the end of his premiership Mr. Johnson was threatening to break his own agreement with the EU. That stance infuriated Brussels and alienated an Irish-American named Joe Biden, killing any talk of a free-trade agreement between Britain and the U.S.
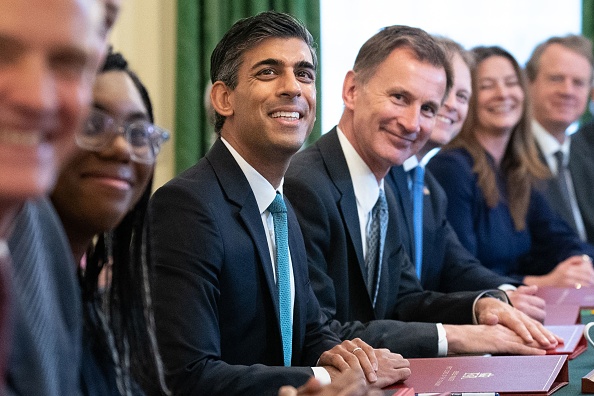
That’s not where things stand today. Building on foundations laid down in the Johnson era, Prime Minister Rishi Sunak has repaired relations with European partners and Washington even as Britain has carved out a significant place in Asia. Britain at long last may be finding a role.
Britain’s recent foreign-policy successes stand on two pillars. The first is Aukus, the agreement to work cooperatively with the U.S. to help Australia build a fleet of nuclear-powered submarines. The trust among these three countries enables a level of technological and economic cooperation that potentially extends far beyond the submarine program. With Britain moving toward membership in the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (based on the Trans-Pacific Partnership that the U.S. helped negotiate but then refused to join), the U.K. has achieved a stronger presence than any European state in the fast-growing Indo-Pacific region.
Meanwhile, Britain’s unswerving support for Ukraine has put London back at the centre of European politics. Britain’s stance earned deep gratitude from Poland, the Baltic states, Sweden and Finland. That, along with Mr. Sunak’s more constructive approach toward Brussels, strengthened pro-British feelings inside the EU and helped pave the way for the major concessions on the Northern Ireland Protocol that enabled Mr. Sunak to forge the groundbreaking Windsor Framework. If the deal, announced last month, holds up, it would remove a major stumbling block in U.S.-U.K. relations.
The payoff could be substantial. Last week Sen. Chris Coons (D., Del.), a close Biden ally, introduced a bipartisan bill with John Thune (R., S.D.) authorising fast-track talks on a U.S.-U.K. free-trade agreement. The White House plans a Biden visit next month to commemorate the 25th anniversary of the Good Friday Agreement, which ended the violence in Northern Ireland. British negotiators hope for Britain’s eventual inclusion in tech talks between Washington and Brussels.
With an unpopular Tory government facing a revived, de-Corbynized Labour Party, and with inflation wreaking havoc on British living standards and touching off waves of strikes among public employees, foreign-policy success may not be enough to save the ruling Conservatives from the wrath of the voters. But it is likely to help, and if the Sunak government can continue to carve out a serious role for post-Brexit Britain in world politics, the next election could be a much closer affair than most forecasters currently predict.
Regardless, Americans should welcome Britain’s return to the high table of world politics. A stronger Britain means a healthier West, and given the otherwise grim state of world affairs, Washington can use all the help it can get.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
From bushland greens to valley reds, the country’s most awarded designers are proving that the best colour palette was never on a swatch card; it was outside the window all along.
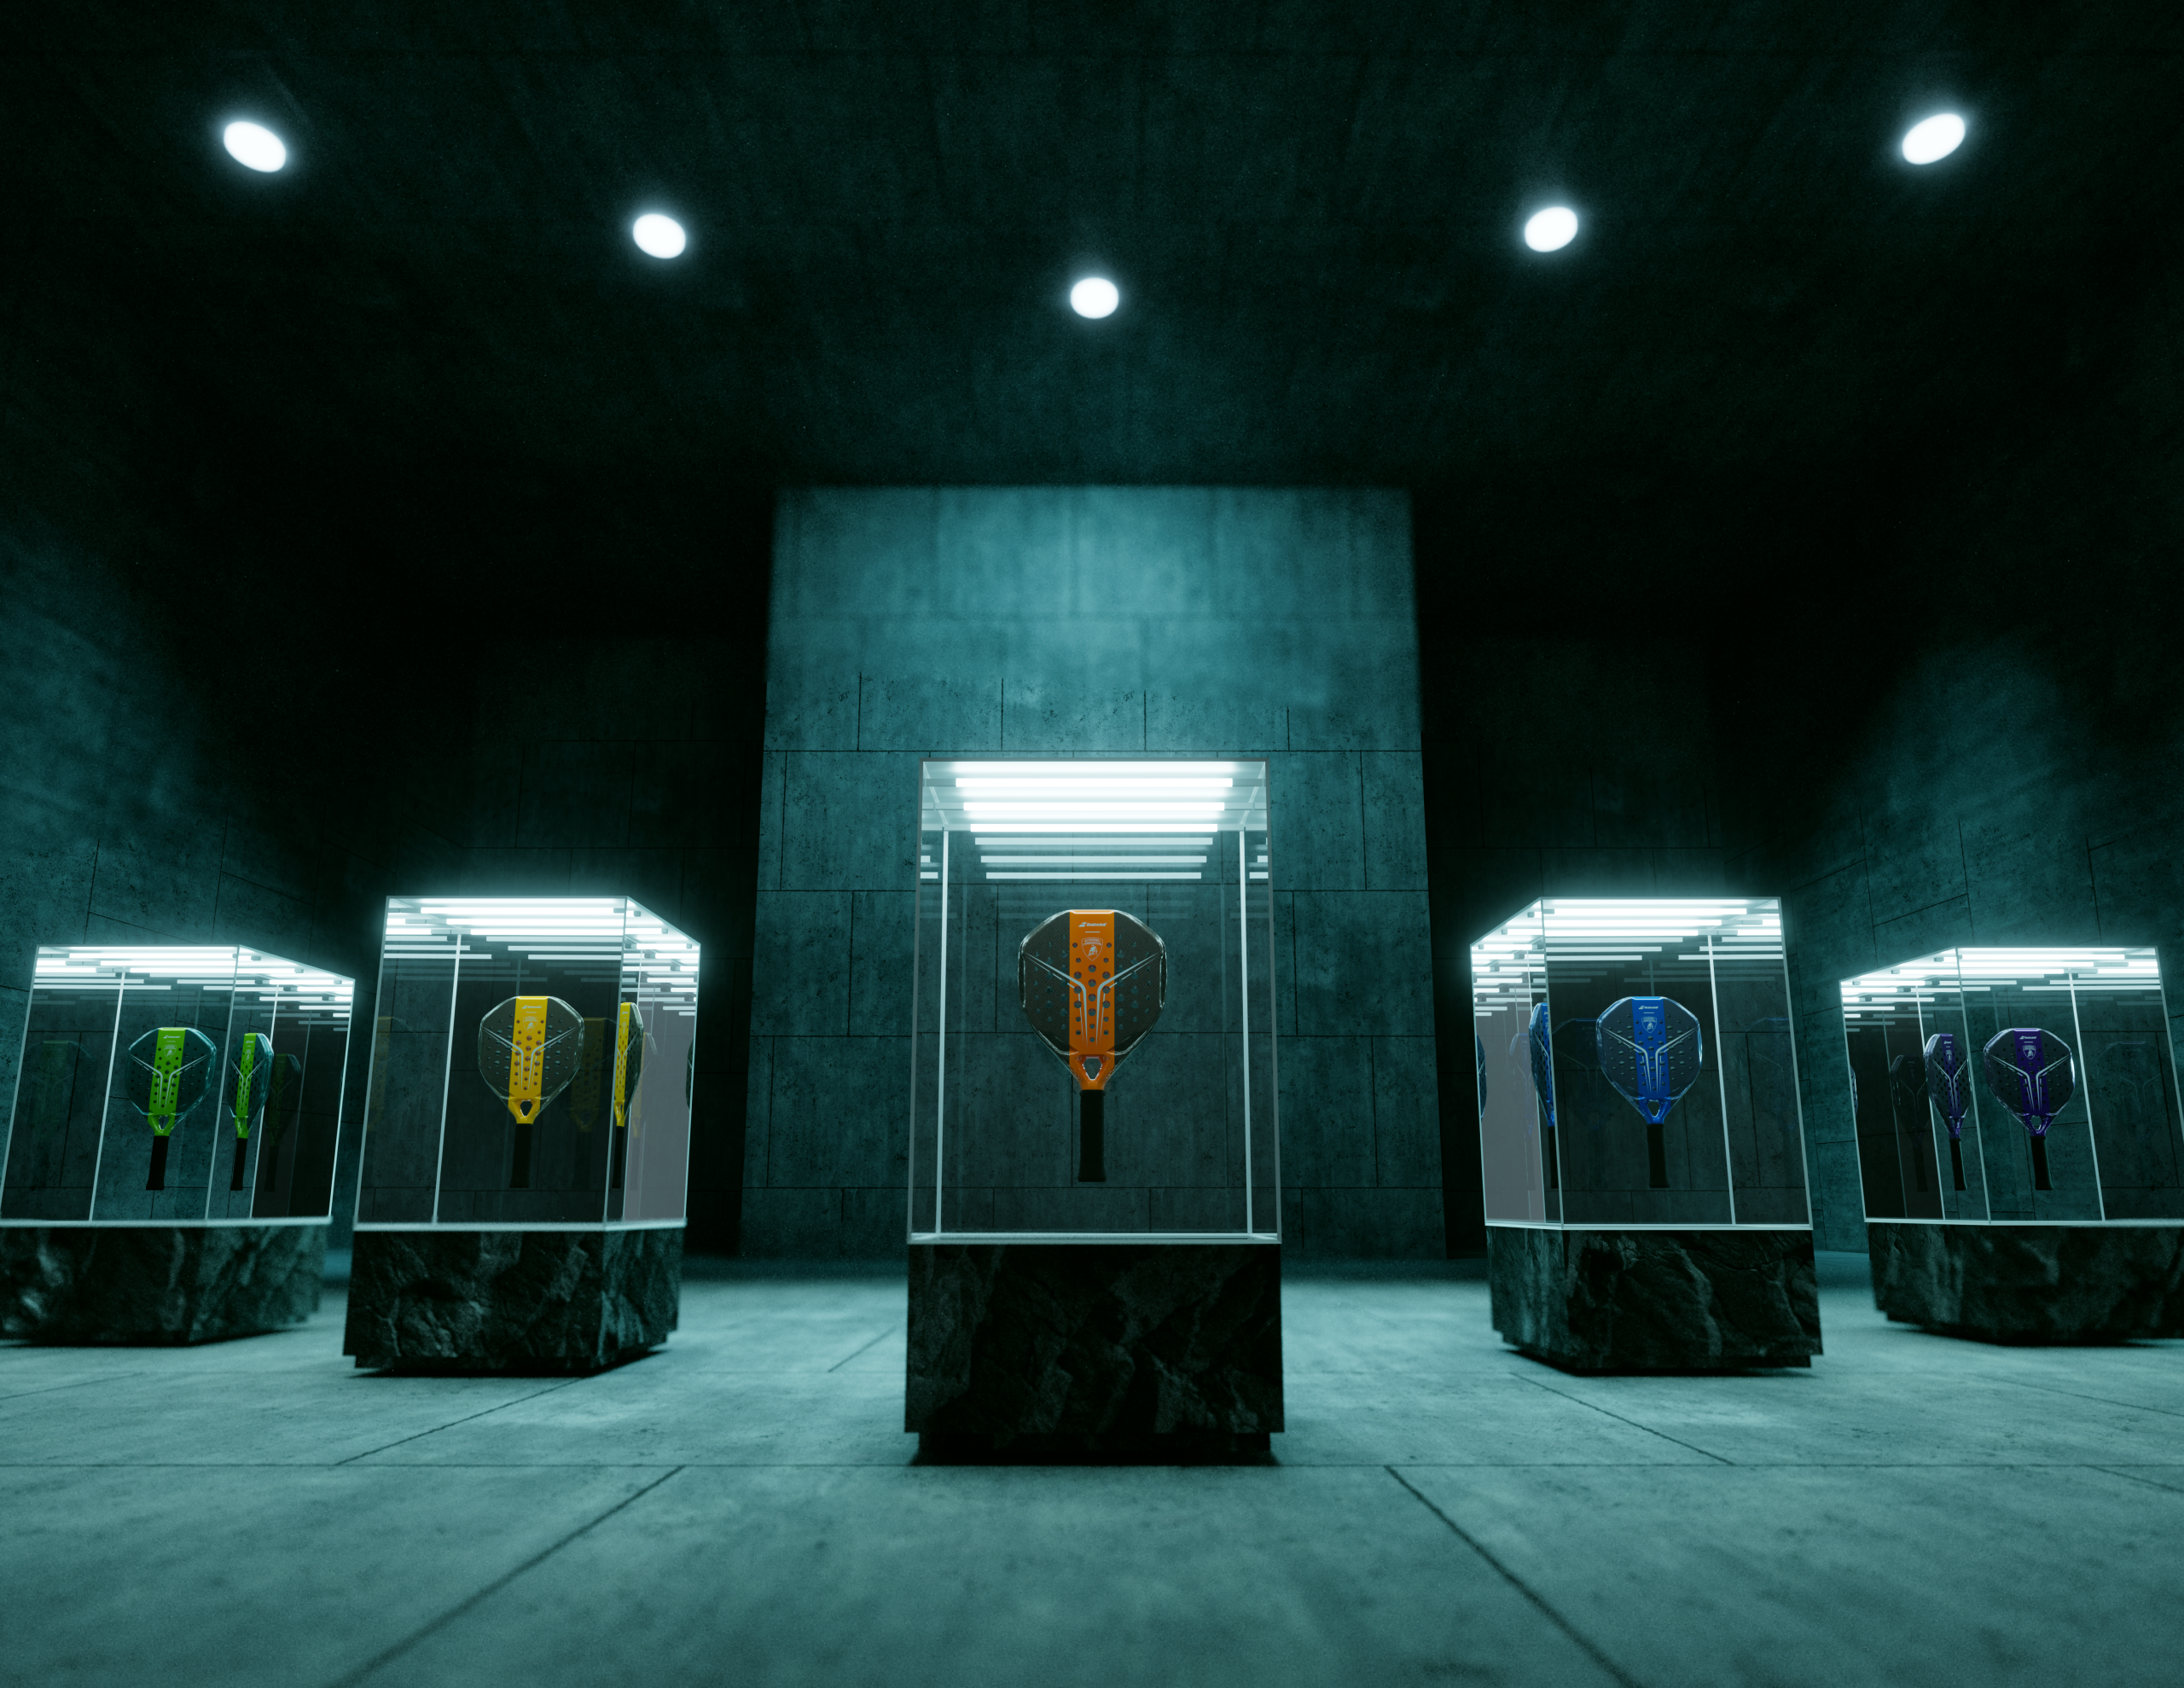
Automobili Lamborghini and Babolat have expanded their collaboration with five new colourways for the ultra-exclusive BL.001 racket, limited to just 50 pieces worldwide.