ChatGPT Is Causing a Stock-Market Ruckus
Investors race to assess the rise of artificial intelligence as a possible ‘iPhone moment’

 3 min
The rise of artificial intelligence is taking the tech world by storm. The technology is also making waves on Wall Street.
It is early days for so-called generative AI, a form of artificial intelligence that can conjure original ideas in the form of text, video or other media. But the tool has caused a stir in companies, schools, governments and the general public for its ability to process massive amounts of information and generate sophisticated content in response to prompts from users.
Big technology companies are investing billions of dollars in the technology. Startups are raising cash and trying to develop business models using AI at a rapid pace.
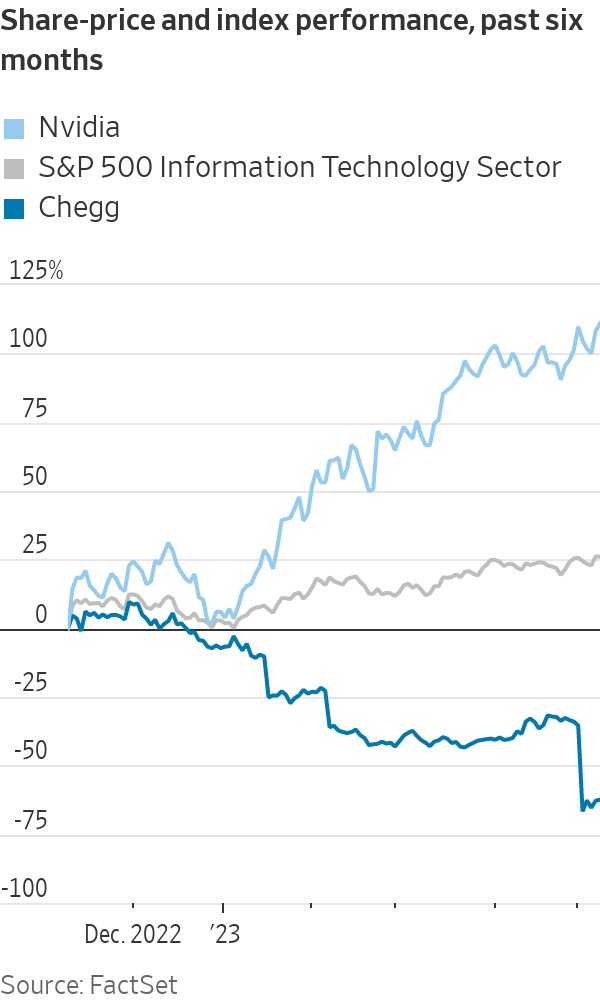
Investors are gauging the extent to which AI’s arrival will upend companies, industries and contemporary business practices—and placing bets accordingly. That has sent stocks swinging wildly in both directions: Chip maker Nvidia’s shares are surging, while shares of study-materials company Chegg have plummeted.Enthusiasm for the potential of AI is one reason big tech companies are among this year’s strongest performers.
There is little doubt that generative AI chatbots are popular. ChatGPT reached 100 million users in two months, the fastest app on record, analysts at Goldman Sachs said in a research note. In comparison, TikTok took nine months to reach that milestone, while Instagram took 30.
“We view AI as huge, and we’ll continue weaving it in our products on a very thoughtful basis,” Apple Chief Executive Tim Cook said last week on a conference call with analysts.
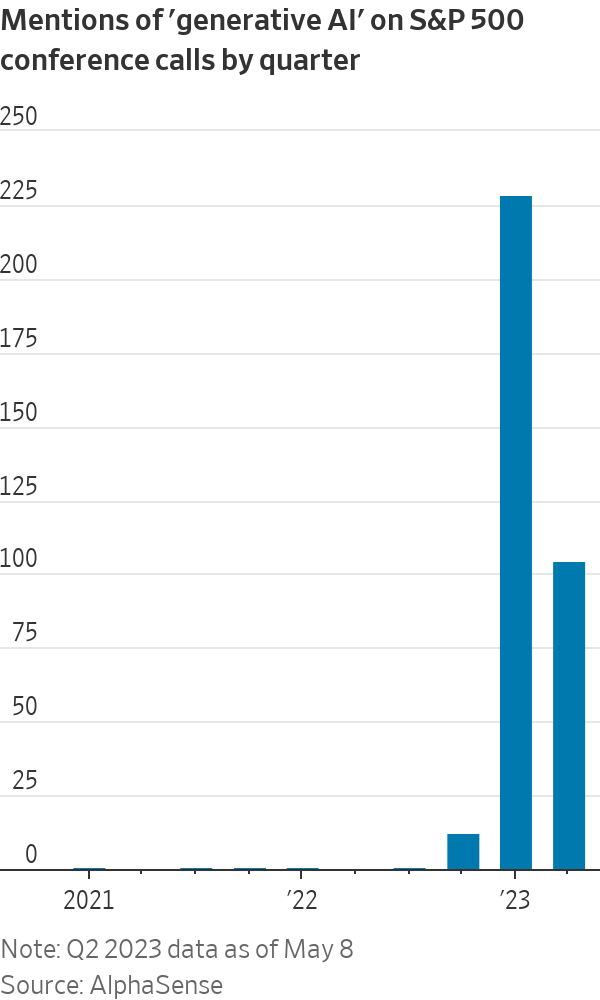
Apple isn’t alone. There have been more than 300 mentions of “generative AI” on company conference calls worldwide so far this year, according to data from AlphaSense. The phrase barely garnered a mention before 2023.
Major health systems are experimenting with AI to see whether the technology can help boost the productivity of their medical staffs. Entrepreneurs and venture-capital investors hope generative AI will revolutionise businesses from media production to customer service to grocery delivery. Even Coca-Cola told investors it is experimenting with the technology.
Some investors wonder whether generative AI is the latest tech with the potential to disrupt entire industries. The dawn of online streaming spelled the end of home-video-rental companies such as Blockbuster, while cameras on phones helped render photo processing obsolete and helped spark Apple’s rise and Kodak’s decline.
Artificial intelligence is “almost certainly overhyped in its initial implementation,” said Michael Green, chief strategist at Simplify Asset Management. “But the longer-term ramifications are probably greater than we can imagine.”
Microsoft has added nearly $500 billion in market value since the tech giant announced a $10 billion investment in startup OpenAI, developer of ChatGPT, in January. Shares of Nvidia, which makes chips needed to power the chatbots, have risen 96% so far this year. Google parent Alphabet shed $100 billion in market value in a single day earlier this year after its chatbot Bard underwhelmed investors, though those losses quickly reversed.
Alphabet shares are up 22% this year.
Those moves might prove ephemeral as the technology’s power becomes clearer, said Daniel Morgan, senior portfolio manager at Synovus Trust. “The most difficult thing to ascertain is, what is going to be the impact of all that spending to these companies on revenues and profits?” His fund owns shares of Microsoft, Alphabet and Nvidia.
The flurry of investor interest has pushed valuations higher. Nvidia trades at 164 times its past 12 months of earnings, according to FactSet. Microsoft and Alphabet trade at 33 times and 24 times, respectively.
Portfolio managers said the race to understand the implications of AI’s emergence is essential, both to invest in the technology’s winners and to avoid its eventual losers. Shares of Chegg fell 48% last week after the study-materials company said that the rise of ChatGPT was harming its ability to attract new customers.
“You just don’t know all the knock-on effects,” said Will Graves, chief investment officer at Boardman Bay Capital Management. “If this really is an iPhone moment, nobody saw that Uber was coming out of the iPhone to hammer the taxi industry.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Strong family financial planning can help reduce taxes and support younger generations. From intrafamily loans and asset gifts to inheritance disclaimers, strategic cooperation can create meaningful financial benefits—when families have the trust and structure to make it work.
4 min
Happy is the family whose members—parents, grandparents and grown children—trust each other enough to cooperate on shared goals, especially financial ones. When that is truly the case, Uncle Sam’s tax rules can help as well.
This matters especially now that mortgage rates are above 7%, and many families are looking for ways to help younger members. If the elders have resources and are confident younger ones can cooperate, a family loan could make homeownership possible while providing the elders with a useful income stream.
Other strategies can actually lower taxes, such as when funding 529 plans or Roth IRAs, or when someone inherits a traditional IRA with required withdrawals larger than they will need.
Here are three strategies useful for functional families.
Intrafamily loans
It is perfectly legal for families to lend money to a relative for a down payment or even a private mortgage.
But it is important not to cut corners, says Ryan McKeown, a CPA with Modern Wealth Enhancement in Minnesota. If the loan is for a down payment, be honest with the mortgage provider and have a formal agreement. The lender owes tax on the interest payments received.
If the loan is for a private mortgage, both sides should have legal representation with a formal written agreement, including payment terms. The lender owes tax on the interest, and the borrower often can deduct it if he or she itemizes.
To avoid IRS trouble, the interest rate shouldn’t be lower than the agency’s Applicable Federal Rate at the time of the loan. Currently that is about 5% for loans longer than nine years; about 4.5% for loans three to nine years; and about 4% for loans three years or less. Currently, traditional mortgage rates are generally above 7%.
In addition, the lender could use the $19,000 annual gift-tax exemption (described below) to forgive some or all of the interest or principal annually. If both lenders and borrowers are married, that is up to $76,000 a year. There is no tax for the borrower on such forgiveness, because it is from a gift.
If you’re going this route, McKeown advises against having a fixed plan to forgive the debt. Instead, do it in one-off letters specifying the amount—and keep careful records. Otherwise the IRS might try to treat the loan as a taxable gift.
Asset gifts
Powerful tax-saving moves for families often use gift-tax provisions. Under current law, anyone can give anyone else up to $19,000 of assets annually, free of gift tax. That means a married couple with three grandchildren could give them a total of $114,000 in 2026.
The gifts can be cash or other assets, like stock. For noncash gifts, the cost basis—which is the starting point for measuring taxable gain after a sale—“carries over” to the recipient. So if someone buys $1,000 of stock and gives it away when it is worth $5,000, the recipient’s cost basis is $1,000. If the recipient later sells the shares for $8,000, the taxable gain is $7,000.
Here’s an example showing how gifts could save a family taxes. Grandma is a widow of modest means, while her child and spouse have prospered. The couple has two children, and they want to contribute $5,000 to a 529 college-savings plan for each—but they need to sell stock to do it. Their tax rate on the sale would be 18.8%, and they would need to sell about $11,000 of stock.
However, Grandma’s federal tax rate on the stock sale is 0%. If the couple gives $10,000 of shares to Grandma, she could sell them, pay no tax, and fund the grandchildren’s 529 plans. This saves about $1,000 of tax.
These moves are legal, and they could be used in other ways, such as to help a young person fund a Roth IRA.
But trust among family members is essential: Under the law, givers can’t put conditions on a gift. Grandma could use her stock proceeds to take a cruise, but she makes 529 contributions instead.
Mark Sellner, a retired tax attorney and CPA living in Sarasota, Fla., uses this strategy. His children sell stock he gives them and fund 529 plans for his grandchildren.
The family’s tax savings aren’t huge, but he likes other benefits. The sales by his children don’t boost his adjusted gross income, which in turn could raise his Medicare Irmaa premiums or his 3.8% surtax on net investment income.
Sellner doesn’t worry about his children using the funds for another purpose.
“There can’t be any strings attached to gifts. Of course, it is up to us to decide whether to make them in the future,” he says.
Two caveats: The “kiddie tax” applies to most children under age 24, and it is levied at the parents’ rate on investment income above $2,700 in 2026. Consider this before making gifts to a young person.
Investors who give away stock also forgo the step-up, an important provision that exempts assets held at death from capital-gains tax.
Sellner knows he’s losing a step-up, but says, “The children could use a little more now. Why should they wait 20 years to get it?”
Disclaimers
A disclaimer is a highly useful strategy in which one heir renounces an inheritance in favor of another heir. Assuming family members cooperate, this can save taxes.
Here’s one example. Dad died and had a large traditional IRA that he left to Mom. She has enough assets and income to cover her expenses, and she lives in a state with a stiff estate tax. The inherited IRA would put her estate over the threshold.
Also surviving are three young-adult children. If Mom disclaims all or part of Dad’s IRA within nine months of his death, that amount could go directly to the children. They will have 10 years to empty the account, and the family as a whole will likely save estate and income taxes.
Disclaimers have many key details, especially regarding beneficiary documents. Although heirs have great freedom in choosing what assets to disclaim, the rules about who gets disclaimed property are rigid. It is best if the original owner names tiers of heirs so that if one disclaims, the next recipient is clear.
High-end homeowners are choosing to upgrade rather than relocate, investing in bespoke design, premium finishes and long-term lifestyle value.

From office parties to NYE fireworks, here are the bottles that deserve pride of place in the ice bucket this season.