Does Warren Buffett Know Something That We Don’t?
Berkshire Hathaway is hoarding cash in a pattern seen before the financial crisis, but it has a new reason this time

 4 min
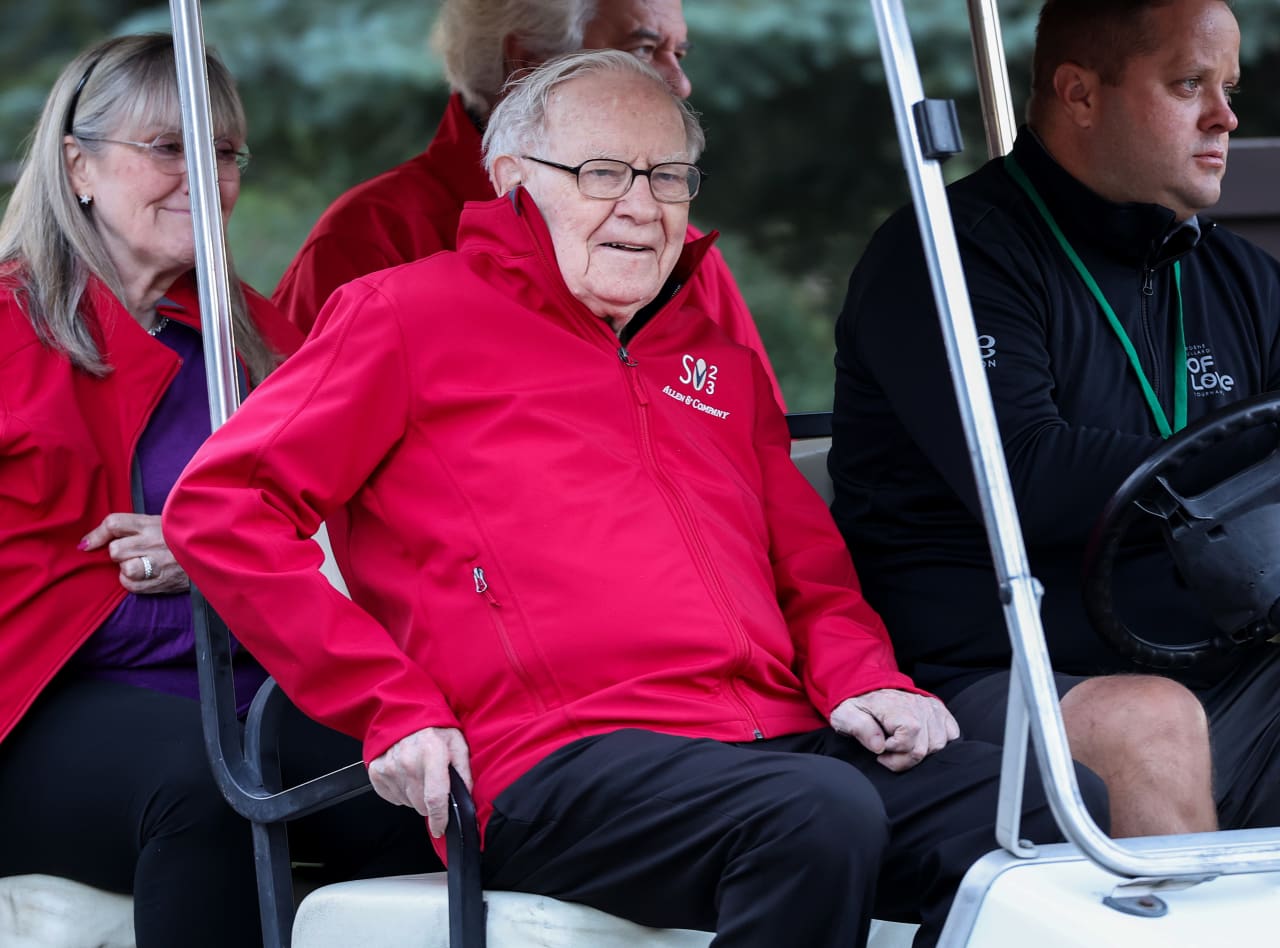
When the world’s most-followed investor doesn’t feel comfortable investing, should the rest of us be worried?
Warren Buffett , who has quipped that his favourite holding period for a stock is “forever,” continues to have substantial money at work in American companies. But he has never taken this much off the table either—a whopping $325 billion in cash and equivalents, mostly in the form of Treasury bills.
To appreciate the immensity of that hoard, consider that it would allow Berkshire to write a check, with change left over, for all but the 25 or so most-valuable listed U.S. corporations—iconic ones such as Walt Disney, Goldman Sachs , Pfizer, General Electric or AT&T. In addition to letting the dividends and interest pile up on its balance sheet, the conglomerate has aggressively sold down two of its largest shareholdings, Apple and Bank of America, in the past several months. And, for the first time in six years, it has stopped buying more of the stock it knows best— Berkshire Hathaway.
Does that mean mere investing mortals should be cautious about the market? Maybe, but it tells us even more about Berkshire.
Buffett and his late business partner Charlie Munger didn’t outperform the stock market 140-fold by being market-timers. Probably Munger’s most famous quote is his first rule of compounding: “Never interrupt it unnecessarily.” Investors who follow Berkshire closely and hope for a bit of its magic to rub off on their portfolios pay very close attention to what it is buying and selling, but much less to when.

Yet the seemingly always optimistic and patient Buffett has turned cautious before, famously shutting his extremely successful partnership in 1969 when he said markets were too frothy and also building up substantial cash in the years leading up to the global financial crisis—money he deployed opportunistically.
“He’s cognisant of the fact that markets gyrate and go to extremes,” says Adam J. Mead, a New Hampshire money manager and Buffetologist who is the author of “The Complete Financial History of Berkshire Hathaway.”
Stock values being stretched doesn’t mean they are on the precipice of a crash or even a bear market. Instead, zoom out and look at what today’s valuations say about returns over the next several years, which will include both good and bad periods. Goldman Sachs strategist David Kostin predicted recently that the S&P 500’s return over the next decade would average just 3% a year—less than a third of the postwar pace.
Kostin’s report went over like a record scratch at a time of high investor optimism, but it is consistent with other forecasts. Giant asset manager Vanguard recently predicted an annual return range of 3% to 5% for large U.S. stocks and just 0.1% to 2.1% for growth stocks over a decade. And Prof. Robert Shiller ’s cyclically adjusted price-to-earnings ratio is consistent with an average return of about 0.5% a year after inflation —similar to Kostin’s projection.
Then there is the even simpler “Buffett Indicator,” which the Oracle of Omaha once called “probably the best single measure of where valuations stand at any given moment.” There are variants on the theme, but it is basically a ratio of all listed stocks to the size of the U.S. economy. Taking the Wilshire 5000 Index as a proxy it is now around 200%, which would leave it more stretched than at the peak of the tech bubble.
With T-bills now yielding more than the prospective return on stocks, it might seem that Buffett has taken as many chips off of the table as possible since there is no upside in risky stocks. But he is on record saying that he would love to spend it.
“What we’d really like to do is buy great businesses,” he said at Berkshire’s 2023 annual meeting. “If we could buy a company for $50 billion or $75 billion, $100 billion, we could do it.”
With Berkshire now worth $1 trillion, it would take a deal of that size to move the needle. Mead explains that a transaction matching acquisitions like 2010’s Burlington Northern Santa Fe deal or the 1998 acquisition of insurer General Re would be worth $100 billion scaled to today’s balance sheet.
Could it also mean that Buffett sees value in keeping dry powder ahead of the next crisis or general froth in the market? Yes, but he isn’t saying, and individual investors also have more options than he does. First of all, we don’t have to pay a 20% or more premium to the market price to invest in a business like Berkshire would in a takeover. We also can sail in much shallower waters and smaller ponds. For example, Vanguard’s 10-year projections range from 7% to 9% a year for non-U.S. developed market stocks and 5% to 7% for U.S. small capitalisation stocks. Other than a very profitable bet on Japanese trading companies in recent years, though, Buffett has kept his money mostly stateside and likely will continue to do so.
Changes at Berkshire are inevitable, though—and not just because the 94-year-old is nearing the end of his remarkable career. Buffett hasn’t hesitated to return cash to shareholders, almost exclusively through stock buybacks, yet he clearly deems even his own stock too pricey for that.
Berkshire also has reached a size at which it can’t replicate its long-run record of deploying its profits and handily beating the market. It is going to have to hand money back somehow—probably through a dividend, reckons Mead. Eventually it becomes necessary to interrupt compounding.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

A thoughtful timber-led renovation in Byron Bay has reimagined an existing house as a warm, resort-style family sanctuary grounded in natural materials.

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.