For These Collectors, It’s Still All About the Cash
Rare banknotes can yield big bucks, if you know what to look for

 4 min
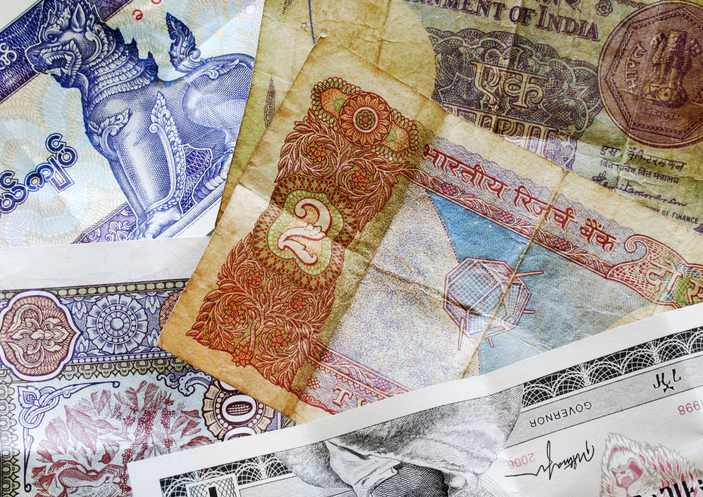
Even as the world increasingly moves toward digitised commerce, where transactions are conducted with the tap of a credit card and billions of dollars are moved electronically between banks, there is one group of people for whom hard cash is still king: collectors.
As an alternative asset class, collectible banknotes offer significant potential value to investors, and the market for these paper artefacts is thriving. Aris Maragoudakis , director of world currency auctions at Stack’s Bowers Galleries in Costa Mesa, Calif., estimates the hobby sees annual trade of well over $500 million globally.
In fiscal year 2016, the World Paper Money department at Stack’s recorded about $4 million in sales. By fiscal year 2024, this figure had risen to $14.5 million. The company reported an 18% increase in sales for world paper money (which doesn’t include U.S. paper-money numbers) in fiscal year 2023, followed by 25% growth in fiscal year 2024.
Elsewhere, the Noonans Mayfair London realised £5 million, or about $6.5 million, in world banknote sales in 2023, up from £2.5 million the previous year, a representative said.
The rise of digital technology has helped broaden the base of collectors. Online auctions, forums and databases have made it easier for collectors to connect, trade and research. Greater access to information about collectible money, as well as to collectible banknotes themselves, have transformed the hobby from a game of chance to a strategic pursuit where enthusiasts can actively search for and acquire valuable pieces.
“The advent of social media such as Instagram and WhatsApp have brought in a spate of new collectors, especially youngsters,” says Rezwan Razack , a specialist in vintage banknotes and chairman of the Indian chapter of the International Bank Notes Society, or IBNS.
While social media has made more people aware of older paper currencies and their histories, the declining use of physical banknotes has made them even more alluring and fascinating to collectors.
Where is the value?
Banknotes routinely become obsolete due to political shifts, security upgrades, monetary policies and technological advancements. The question is: Which ones are worthy possessions?
A plethora of factors underpin the desirability of collectible paper money. The major ones are:
• Condition: The condition of a piece can have a significant impact on its value. “There are bills that sell for $1,000 with a fold or two, but finding one free of any folds, stains, or tears could be worth several times that,” says Maragoudakis.
The condition of a bill is evaluated based on a 30-point scale ranging from poor to uncirculated crisp. Within each condition, a bill is given a number grade; a higher number—on a scale typically from 1 to 70—means the banknote is in better shape.
For example, a 10,000-yuan note issued in 1951 by the People’s Bank of China, graded Very Fine 20, sold for $150,000 at a Stack’s Bowers auction. Three years later at another Stack’s Bowers auction, a similar note in better condition, graded Almost Uncirculated 50, fetched $358,500.
• Serial number : Banknotes with striking serial numbers are often worth more to collectors than those without. On eBay, a rare polymer £20 bill with the serial number AA44 444444 received 16 bids and sold for more than £317.
A set of four exceptionally rare Chinese 1953 10 yuan notes from the People’s Bank of China recently sold for $432,000 because in addition to their quality, they were consecutive in serial number.
• Scarcity : The appeal and worth of banknotes, as with other collectibles, are often tied to their rarity.
For instance, high-value banknotes were often printed in limited quantities due to their significant purchasing power, says Hakim Hamdani , director at large and a collector at the Netherlands branch of the IBNS. When these high-denomination notes are discontinued, many people cash them in rather than keeping them as collectibles.
Take the 1921 10,000-shilling note from British East Africa (now Kenya and Tanzania), of which few were printed and issued. At that time, it was equivalent to about $2,000, a substantial sum in 1920s colonial Africa. When they were demonetized, most were redeemed, making the few remaining in private hands highly desirable.
Dennis Hengeveld , president of World Banknote Auctions in Sacramento, Calif., says that depending on the condition, some of these notes have fetched between $35,000 and just over $100,000 at auctions.
A rare $500 Canadian bill from 1911 brought C$528,750 (about $386,400) at a recent auction, the largest sum ever paid for a Canadian banknote. The specimen features the image of Queen Mary and is one of only four of the bills known to exist.
• Error notes : Governments often withdraw banknotes from circulation to deter counterfeiting, but also due to printing anomalies such as incorrect signatures, numerical discrepancies, misprints and typographical errors. Such deviations can elevate their value among enthusiasts.
In the U.S., double denominations—such as a front displaying a $10 bill and the reverse displaying a $20 bill—are the most prized error notes. The value of some of these pieces could top $85,000, according to Heritage Auctions.
How can I get started?
Despite the potential for a lucrative return, experts say the primary motivation for building a collection should be enjoyment and an appreciation of the history that banknotes provide. It would be best to build a collection with the idea of having fun, says Hengeveld of World Banknote Auctions, which was recently acquired by Stack’s Bowers.
Of course, it’s essential to do your due diligence to avoid fraud. Always buy notes from established dealers and confirm their authenticity with reputable grading services. Independent grading companies such as Paper Money Guaranty and Professional Coin Grading Service provide authentication and grading to ensure notes are genuine and their condition accurately assessed.
Auction houses and local dealers offer currency notes in different price ranges. Online retailers (eBay, Amazon.com, Collectibles & Currency), dealers and galleries (Certified Coin Exchange, George H. LaBarre), and numismatic shows (the MIF Paper Money Fair and World’s Fair of Money) are other useful sources.
As well, there is no shortage of stories where people discovered highly valuable collectible banknotes in attics, books, dressers and photo frames of deceased family members. In Ontario, a rare Canadian $500 bill from 1911 was discovered among the personal belongings of a deceased individual. The nearly discarded banknote, one of only three in existence, brought $322,000 at auction.
Those looking to dip their toes into collectible money may find valuable insights in trade magazines including Bank Note Reporter and the Greensheet, or books such as the U.S. Error Note Encyclopedia and Standard Guide to Small-Size U.S. Paper Money.
Additionally, Paper Money Guaranty, the Smithsonian Learning Lab and other websites can offer a wealth of information on various aspects of grading, collecting and how to properly care for banknotes.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
High-end homeowners are choosing to upgrade rather than relocate, investing in bespoke design, premium finishes and long-term lifestyle value.

A survey of people with at least $1 million in investable assets found women in their 30s and 40s look nothing like older generations in terms of assets and priorities