How Investing Will Change if the Dollar No Longer Rules the World
Should the U.S. currency and stocks no longer rise together, Americans will need to broaden their portfolios.

 3 min

If you’ve been investing your savings for the past 15 years, there is a situation you’ve hardly ever encountered: the U.S. dollar getting structurally weaker. Given the fallout from President Trump’s “Liberation Day,” you may need to get used to it.
Wall Street was caught off guard when the greenback dropped against major currencies following this past week’s tariff news. Markets feared that protectionism could put an end to the U.S.’s economic dominance since the global financial crisis.
International money managers, who had massively biased their holdings toward U.S. assets, are feeling the urge to find another source of high returns. American investors, long comfortable ignoring foreign stocks, may no longer have that luxury.
“We are working on the assumption that in the next five years, the dollar is going to lose another 10% to 15%,” said Luca Paolini, chief strategist at Switzerland’s Pictet Asset Management.
To be sure, asset managers in many cases are making short-term, defensive moves to protect against a potential recession. It also follows a trend of money leaving the “Magnificent Seven” stocks specifically— Apple , Microsoft , Amazon.com , Alphabet , Meta Platforms , Nvidia and Tesla —for reasons not fully related to Trump .
These companies drove much of the exceptional returns of the past decade and a half, but their collective price/earnings ratio hit a staggering 46 times last December. At such a lofty level, it doesn’t take much for a fall to ensue.
Even excluding the Magnificent Seven, though, Americans who bought the rest of the S&P 500 15 years ago earned a total return of around 380%. Europeans who did the same, unhedged, earned about 490%—thanks to the dollar’s more than 20% gain against the euro, according to FactSet.
The reverse also holds: Eurozone equities returned about 220% in euros, but only 150% in dollars. Japanese equities tell a similar story—the Nikkei 225 gained 300% in yen, but just 160% in dollars. No wonder Americans haven’t rushed to add these stocks to their 401(k)s.
What is striking is that a stronger dollar should, mechanically, hurt U.S. stocks—by reducing the dollar value of overseas earnings—and help foreign ones. Historically, it has been better to buy the S&P 500 when the dollar was weakening. Over the past five years, that held true: Fed rate hikes strengthened the dollar while hurting equities.
But in the seven years before Covid-19, the dollar and U.S. equities moved in sync. That was the heyday of the “American exceptionalism trade,” when U.S. assets outperformed across the board—not just in tech. This included currency-sensitive sectors like industrials.
Two forces helped drive this. One was the fracking boom, which made the U.S. largely energy self-sufficient, cutting corporate costs and turning the dollar into a kind of “petrocurrency.” Investors learned in 2014 the counterintuitive lesson that the U.S. economy may actually suffer when crude prices nosedive, and benefit when they rise.
Indeed, the other factor was that U.S. consumer spending was unrelenting, even at times when gas-pump prices increased. For years, it has been powered by government deficit spending, a tech sector exporting services globally at scale, and the wealth effects from a booming stock market.
Most of that now risks being turned upside down, exposing investors to the prospect of falling equities alongside a weakening currency.
Trump has pledged to plug the budget deficit, which could arguably weaken the dollar. Meanwhile, he has launched a tariff war that has tanked the equity market, triggered retaliation from China and may provoke European blowback against U.S. tech giants.
The new regime could echo the early 2000s, when investors turned against both tech and U.S. stocks in the aftermath of the dot-com bubble. At the time, the dollar also had a positive correlation with equities, as capital flowed into the so-called Brics—Brazil, Russia, India, China, and South Africa.
In a report to clients Friday, Jeff Schulze of ClearBridge Investments noted that international equities have historically picked up the slack when the S&P 500 lagged behind. In such cases, the MSCI EAFE and MSCI Emerging Markets indexes beat the benchmark U.S. index by an annualized average of 2.0 percentage points and 12.1 percentage points, respectively.
A weaker dollar itself helps support the financial resilience of developing nations. Meanwhile, the European Union has rekindled investor hopes that it can close the growth gap with the U.S. through fiscal stimulus, industrial policy and energy independence.
At the same time, this is nothing like the 2000s. The rest of the world is far more exposed to trade than the U.S.’s relatively closed economy and will have to grapple with China rerouting a huge glut of cheap goods there.
Another option for investors, then, is to remain in U.S. equities and hedge the currency risk—but that is expensive—or to broaden exposure to discounted “value” stocks and try to identify potential long-term winners.
An economy reshaped by Trump would imply more investment and less consumption. Since the only profitable way to onshore production—whether a Nike shoe or a General Motors SUV—is to use machines instead of labor, capital goods manufacturers may eventually benefit. But they are also among the hardest hit by today’s indiscriminate disruption to global supply chains.
Given the complete lack of clarity, the only solution for those who still need the long-term upside of stocks may be to do all of it at the same time. Right now, diversification isn’t just a strategy, it is a lifeline.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


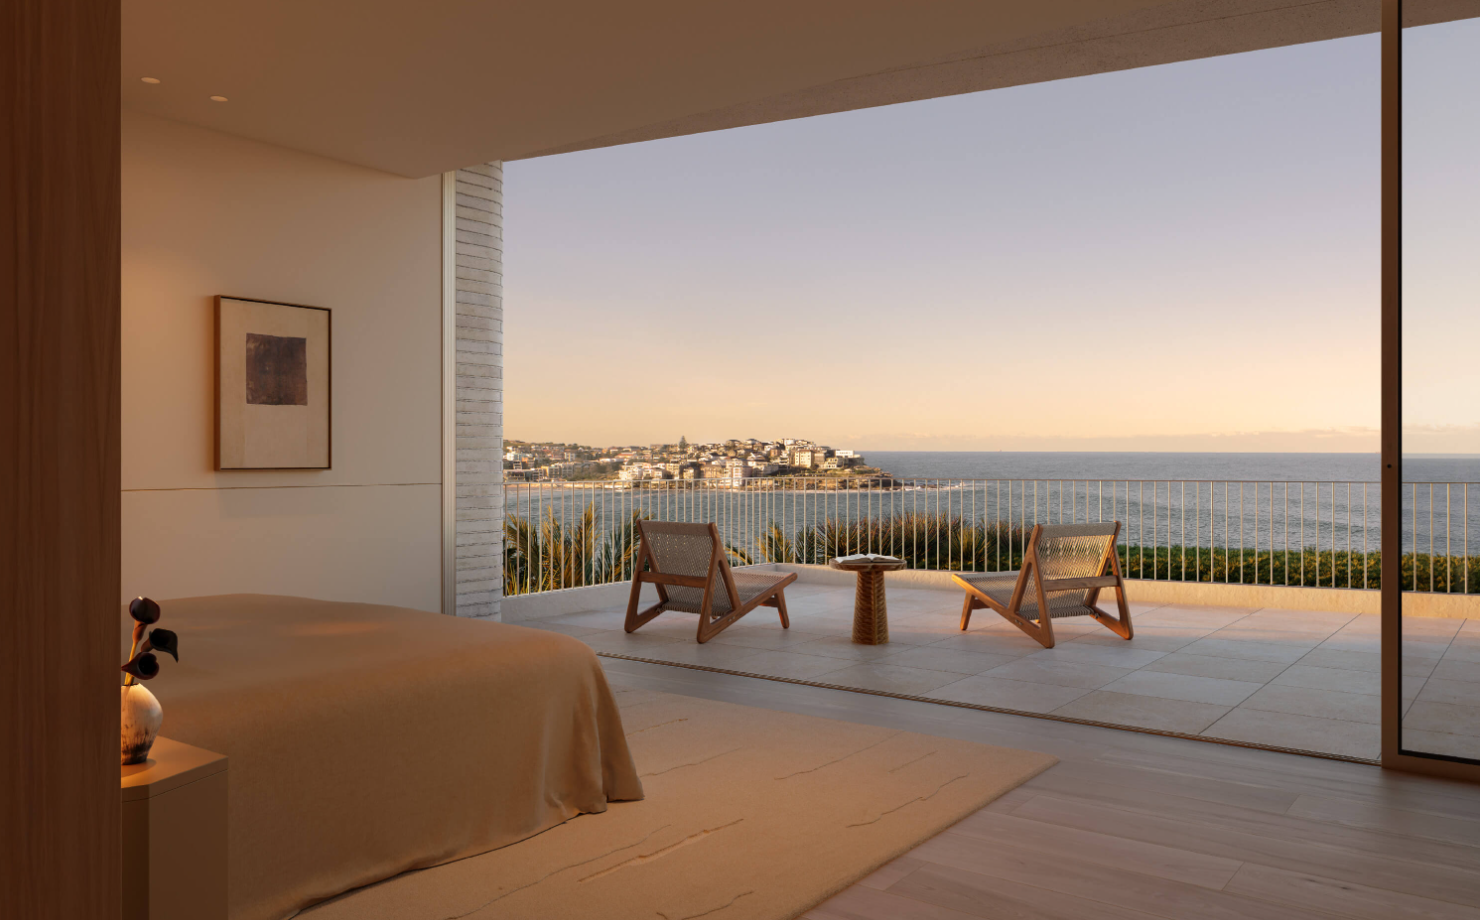
For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
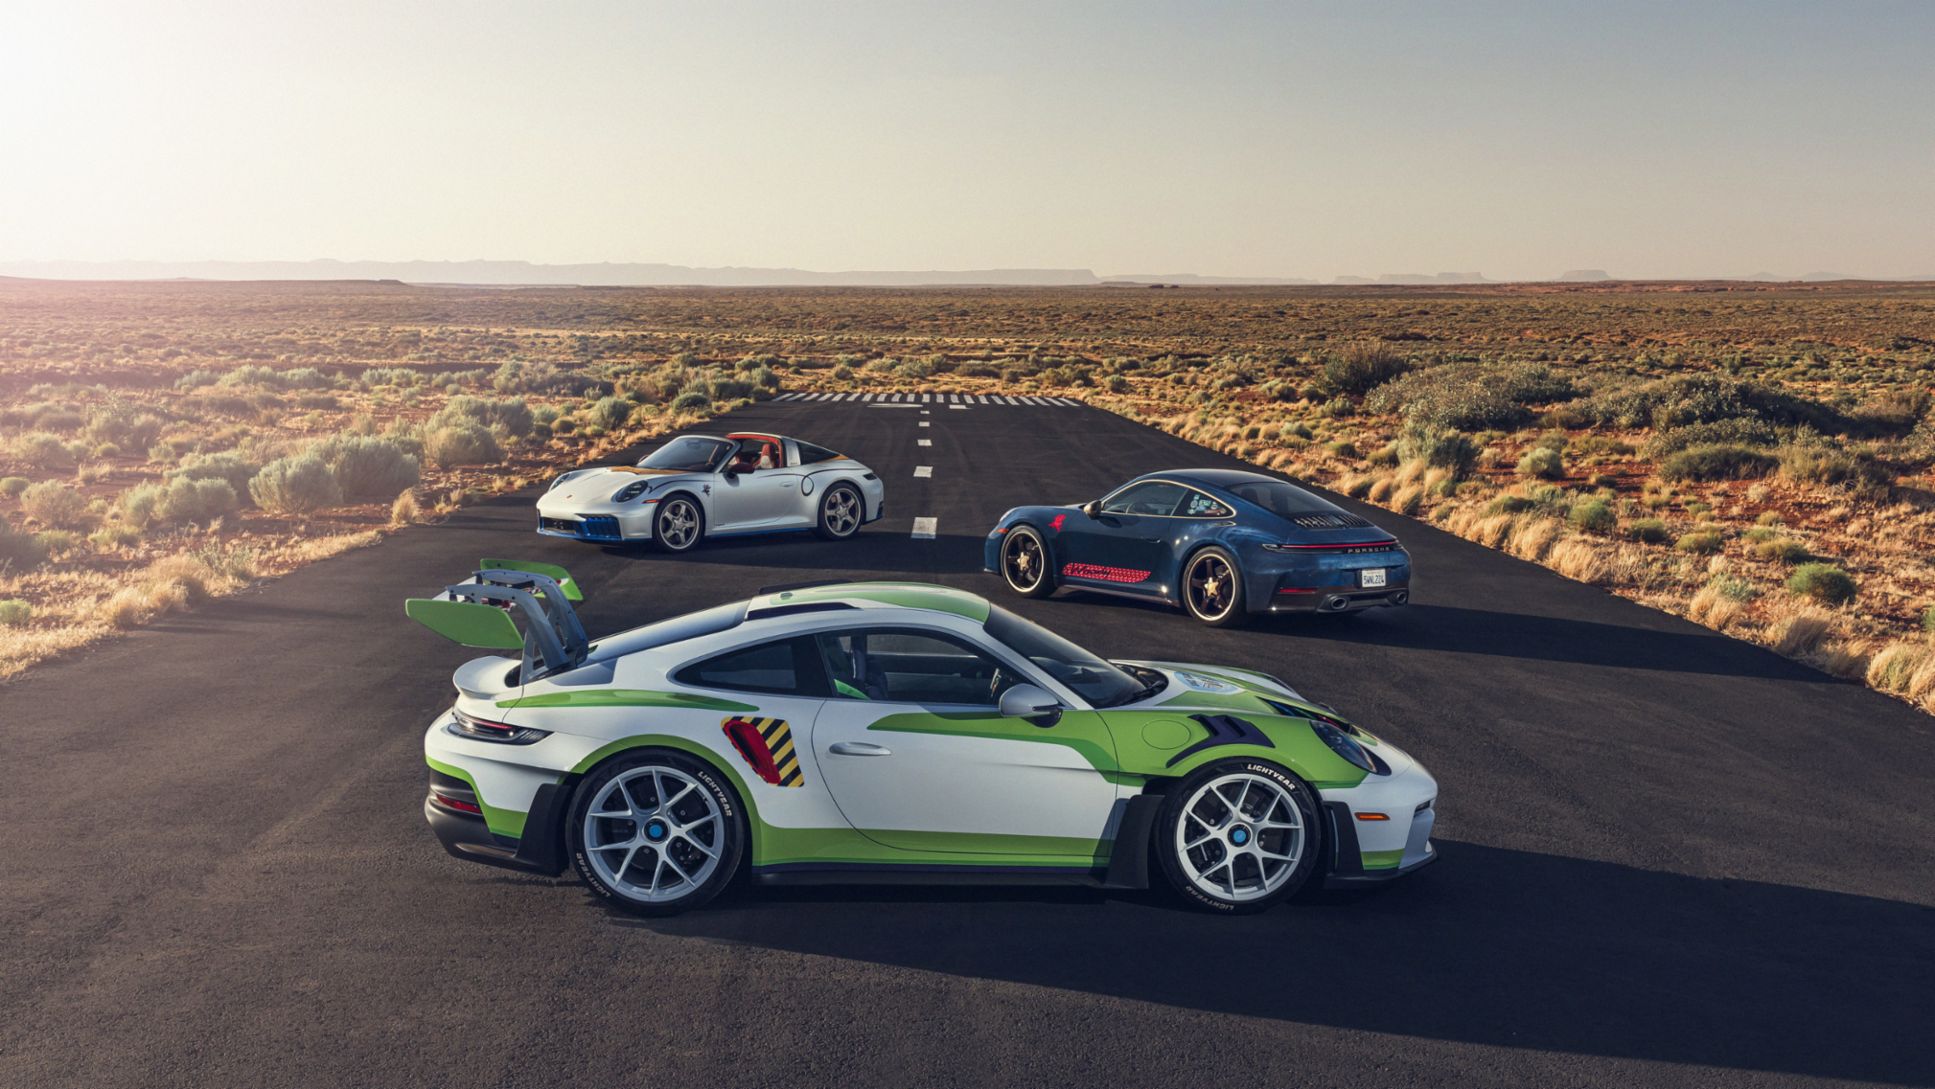
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations
5 min
Reporting season has once again reminded investors that a strong profit does not guarantee a rising share price, and a large loss does not always trigger a sell-off. What matters most is how each result compares with expectations and, increasingly, what management says about the year ahead. During the August 2026 season, companies offering credible turnarounds or unexpectedly strong guidance were rewarded handsomely, while those flagging weaker margins, slowing demand or greater uncertainty were punished.
The following ranking draws on Morningstar’s review of 164 ASX-listed companies and measures each company’s share-price movement on the day it reported. This captures the market’s immediate response to the earnings announcement, before subsequent economic developments, dividends and company-specific news cloud the picture. Here are the five biggest winners, and the five hardest-hit losers, of the season so far.
The five winners
1. Bapcor (ASX:BAP): +41.0%
Bapcor delivered reporting season’s largest relief rally after presenting early evidence that its troubled automotive-parts business was stabilising. Although underlying revenue fell 1.8% to $1.92 billion and underlying NPAT collapsed 85% to $10.8 million, underlying EBITDA of $152.5 million exceeded guidance.
More importantly, working-capital initiatives released $68.5 million in the second half, lifting cash conversion to 109.4% and reducing net debt by 63% to $135 million. The statutory loss was $431.6 million, largely because of non-cash impairments. Investors focused on improving operational momentum, stronger liquidity and management’s expectation of modest FY27 revenue growth.
2. Zip Co (ASX:ZIP): +18.2%
Zip comfortably surpassed its FY26 targets, sending the buy-now-pay-later provider’s shares sharply higher. Transaction volume rose 23% to $16.7 billion, while cash earnings before tax, depreciation and amortisation jumped 58% to a record $268.9 million. Statutory profit climbed 46% to $116.4 million, and the cash operating margin expanded by 4.2 percentage points to 20%.
The strongest signal was guidance for FY27 cash earnings of $340 million—around 26% growth and above analysts’ forecasts. US transaction volume increased 42.5% and now represents three-quarters of group volume, offsetting weaker customer activity in Australia.
3. CSL (ASX:CSL): +17.3%
CSL’s result was hardly spectacular in isolation, but it cleared a market bar that had fallen dramatically following earlier downgrades and restructuring announcements. Underlying NPATA was US$3.1 billion, down 2% in constant-currency terms, while operating cash flow reached US$3.51 billion.
CSL maintained its full-year dividend at US$2.92 per share and completed a A$1 billion buyback. The real catalyst was FY27 guidance for approximately 5% underlying profit growth, compared with market expectations closer to 2%. After an extended period of earnings disappointments, investors interpreted the outlook as evidence that CSL’s core plasma business was approaching a sustainable recovery.
4. Judo Capital (ASX:JDO): +16.9%
Judo Capital demonstrated strong operating leverage as its specialist business-lending franchise expanded. Full-year profit before tax rose 34% to $168.1 million, while pre-provision profit increased 42%. Gross loans and advances grew 18% to $14.7 billion, reaching the top of the bank’s guidance range and comfortably exceeding broader system growth.
Deposits increased 24% to $12.2 billion, return on equity improved by 1.1 percentage points to 6.4%, and earnings per share rose 29% to 9.9 cents. Reaffirmation of the FY27 outlook gave investors confidence that loan growth could continue without sacrificing margins or credit quality.
5. Super Retail Group (ASX:SUL): +15.8%
The owner of Supercheap Auto, rebel, BCF and Macpac reported record sales of $4.2 billion, up 3.2%, despite cautious discretionary spending. Profitability went backwards: normalised profit before tax fell 7% to $306 million and normalised NPAT declined 2.8% to $226 million as transformation spending weighed on margins. Nevertheless, the result exceeded subdued expectations, online sales grew 5.3% and membership across the group’s loyalty programs reached 13.1 million. Investors were also encouraged by positive early FY27 trading, stable gross margins and continued market-share gains. A fully franked 33-cent final dividend added to the appeal.
The five losers
1. Hansen Technologies (ASX:HSN): –21.2%
Hansen’s historic result met expectations, but investors recoiled from its outlook. The utility and communications software provider achieved an underlying EBITDA margin of 31%, exceeding its 30% target, while generating strong cash flow. However, management designated FY27 an “investment and transition year”, signalling a roughly five-percentage-point margin contraction as spending on products, sales capabilities and organisational changes increased.
Revenue had already been broadly flat, leaving investors concerned that the investment program would depress earnings before new growth appeared. Leadership changes, including the chief executive’s departure, added uncertainty. Management expects revenue growth and margins above 30% to return in FY28, but the market was unwilling to wait.
2. Life360 (ASX:360): –19.4%
Life360’s headline growth was impressive: quarterly revenue rose 38% to US$159 million, subscription revenue increased 31%, and adjusted EBITDA climbed 53% to US$31.1 million. Monthly active users reached 102.4 million and paying circles grew 27% to 3.2 million. The sell-off reflected expectations rather than a collapsing business.
Net income fell 18%, the net margin contracted from 6% to 3%, hardware shipments dropped 18%, and full-year EBITDA guidance was merely maintained. After a strong valuation run, investors wanted a larger upgrade and clearer evidence that heavy investment in advertising, international expansion and artificial intelligence would generate additional earnings.
3. PEXA Group (ASX:PXA): –17.0%
PEXA reported a 7% increase in continuing-operations revenue and 12% EBITDA growth to $152 million, accompanied by a two-percentage-point margin expansion. Free cash flow increased 39%, suggesting the core Australian electronic-conveyancing platform remained highly profitable. Investors instead concentrated on management’s warning that property-transfer volumes could decline, alongside regulatory uncertainty surrounding the fees PEXA can charge.
The company is also continuing to invest heavily in its loss-making international expansion. Morningstar considered the market reaction excessive, arguing that structural transfer-volume assumptions had not materially changed, but the combination of softer near-term activity and regulatory risk overwhelmed the respectable headline numbers.
4. SEEK (ASX:SEK): –14.3%
SEEK produced solid FY26 figures, including 10% revenue growth to $1.20 billion, a 15% rise in EBITDA and 28% growth in adjusted earnings per share. It also lifted its fully franked annual dividend by 13% to a record 52 cents. Those achievements were overshadowed by falling paid job-ad volumes and cautious FY27 assumptions.
The statutory accounts included a $201 million loss from the SEEK Growth Fund and $377 million of significant items, making the headline result considerably less attractive. Investors were particularly concerned that economic weakness could limit volumes while the company continued investing in platform integration and artificial-intelligence products.
5. JB Hi-Fi (ASX:JBH): –12.3%
JB Hi-Fi’s full-year result was broadly respectable, with group sales rising 5% to $11.1 billion and underlying earnings per share increasing 6% to $4.48. The damage came from its current-trading update. Australian sales were almost flat during the June quarter and deteriorated further in July, while earnings in the core Australian electronics business fell 3.6%.
Housing-related categories were particularly weak as higher living costs and interest rates constrained household budgets. With JB Hi-Fi entering the season on a demanding valuation, an in-line historic result was not sufficient: the loss of sales momentum prompted investors to rapidly reduce their expectations for FY27.
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations. Bapcor was rewarded for being less troubled than feared, while several fundamentally profitable companies were punished because their outlooks failed to justify elevated valuations.

Two coming 2027 models – the first of the “Neue Klasse” cars coming to the U.S. early next year – have been revealed.
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation