Meet the HENRYS: The Six-Figure Earners Who Don’t Feel Rich
When you’re a HENRY—high earner, not rich yet—a hefty salary isn’t enough to buy freedom from financial pressure

 4 min
Fifteen years ago if you’d told April Little that she’d make $300,000 a year, she would have pictured a life free of financial stress.
“The white picket fence—I have the whole visual in my head,” says Little, 38 years old, a human-resources executive turned career coach in Rochester, N.Y. “I don’t want to sound ungrateful, but when I got to that proverbial mountaintop I realised there’s a lot of expenses. And I still don’t own a home.”
So go the plush-but-not-too-plush lives of the Americans who qualify as HENRY—high earner, not rich yet.
Little makes multiple six figures running her own business but carries $90,000 of college and grad-school debt. Child care and education for her three children would be so costly that she and her husband decided the better option was for him to leave his radio job to parent and home-school full time.
New census data show 14.4% of U.S. households bring in $200,000 or more a year, a near record. Yet the money doesn’t have the buying power those earners wish it did, partly due to the rising prices hammering us all and partly due to the supercharged costs of things like houses and cars. HENRYs describe feeling stuck on a hamster wheel—a nice one that other hamsters envy—but running in place nonetheless.
Oh come on, you’re thinking . You’re asking me to feel sympathy for Audi-driving, Chase Sapphire-loving, Whole Foods-shopping consultant types with kids in private school?
Well…not exactly. But what they’re feeling is a version of what a lot of Americans at every income level face—making more money but not feeling like there’s a surplus. The essence of being a HENRY is feeling a gap between what you have and what you think you need to be comfortable.
What these high earners consider essentials might be termed luxuries (or nonsense) by the rest of us, but it’s also true that it takes more money to feel rich these days. And their great fear is becoming a HENRE: high earner, not rich ever .
Short of expectations
Attorney Joshua Siegel doesn’t expect sympathy as he motors around Los Angeles in his Lexus SUV. He just figured at age 40, having risen to partner and chair of the transactional tax group at Albrecht Law, that he might be driving from a house he owns to a country club where he’s a member.
Instead, his occasional golf outings take him from his rental home to a public course. Raising three kids in one of the country’s most expensive cities has been a reality check, he says. He’s also realised that a lot of people with jobs like his come from wealthy families where trust funds and down-payment assistance give them financial head starts.
The son of an electrician and a dental assistant, Siegel is making his own way in the white-collar world.
“It really just feels like treading water,” he says.
Monique So, a 40-year-old financial consultant, says she and her husband, a software engineer, have a net worth in the mid-seven figures. But she likely won’t breathe easy until, or if, they accumulate an eight-figure net worth. Daycare for their 2-year-old takes a $30,000 bite out of their family budget.
“I have this scarcity mindset that is very common,” she says.
What it takes to feel rich
Caitlin Frederick, director of financial planning at Ullmann Wealth Partners in Jacksonville Beach, Fla., says many of her mid career clients are less affluent than their salaries suggest. She advises a lot of prototypical millennials who racked up student loans in hopes of vaulting into high-paying jobs. They delayed buying houses and starting families while climbing professional ladders.
The first part of their plans worked, she says. The degrees led to hefty incomes. Now that they’re having kids, shopping for real estate and wishing to upgrade their Camrys, they’re discovering that many of life’s major expenses shot up faster than the overall rate of inflation.
Lifestyle creep is a factor too, she says, noting clients who overspend on trips and restaurants.
“It is easy for people to just continue to increase their lifestyle every time they get a promotion,” Frederick says.
Then again, they watched their slightly older co-workers spend freely, and buy lake houses, too. The good life requires more money than it used to, she adds.
In 2009, the median home price was $220,900, according to the Federal Reserve, and a new car cost an average of $23,276, according to the Energy Department. Had prices increased at the rate of the consumer-price index, the average house would cost $322,000 today and a car would cost $34,000. Instead, the Fed reports an average house goes for $412,000 today, and a typical new car is $48,000, according to Kelley Blue Book.
The national going rate for a babysitter 15 years ago was $10.50 an hour, according to Care.com. Now it’s $18.38, 20% more than if the cost had tracked the consumer-price index.
Budget-conscious HENRYs tell me it’s often hard to find mid tier options in, well, anything, as companies push luxury versions of everything from high-end water bottles to $1,000-a-night hotel rooms .
Another big-ticket item
Another financial curveball comes up frequently in my conversations with high earners: school costs.
Nearly half of American private schools increased enrolment in the last academic year, according to the Cato Institute. Parents who originally planned to send their children to public school tell me they’ve gone private for reasons that include pandemic learning disruptions, public schools’ difficulty retaining good teachers and budget problems . Some say they’re convinced private schools are the only places their kids will thrive, though more than 80% of American kids attend public school.
Brad Gyger and his wife shuttle their three children around in a 2014 GMC Yukon with 130,000 miles—not exactly the late-model, luxury ride he expected to own as a three-time chief revenue officer in the tech sector. Then again, he didn’t anticipate annual private-school tuition payments roughly equivalent to the price of a new, fully loaded Cadillac Escalade.
Gyger, now an independent sales consultant in California, says he didn’t consider private education until a few years ago, when he and his wife concluded their oldest child would thrive in a more academically challenging environment. The school could also accommodate their second child’s learning needs. And how could they leave out the youngest?
Gyger, 46, says his family is fortunate to even have education options. The trade-off is living more modestly than his résumé might suggest.
He gave up gym and tennis-club memberships, opting to stay fit on the cheap by cycling and lifting dumbbells in his garage. And forget about upgrading from the home the couple bought in 2015.
“We’re probably never moving,” says Gyger. He hopes they’ll remodel the kitchen. Someday.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
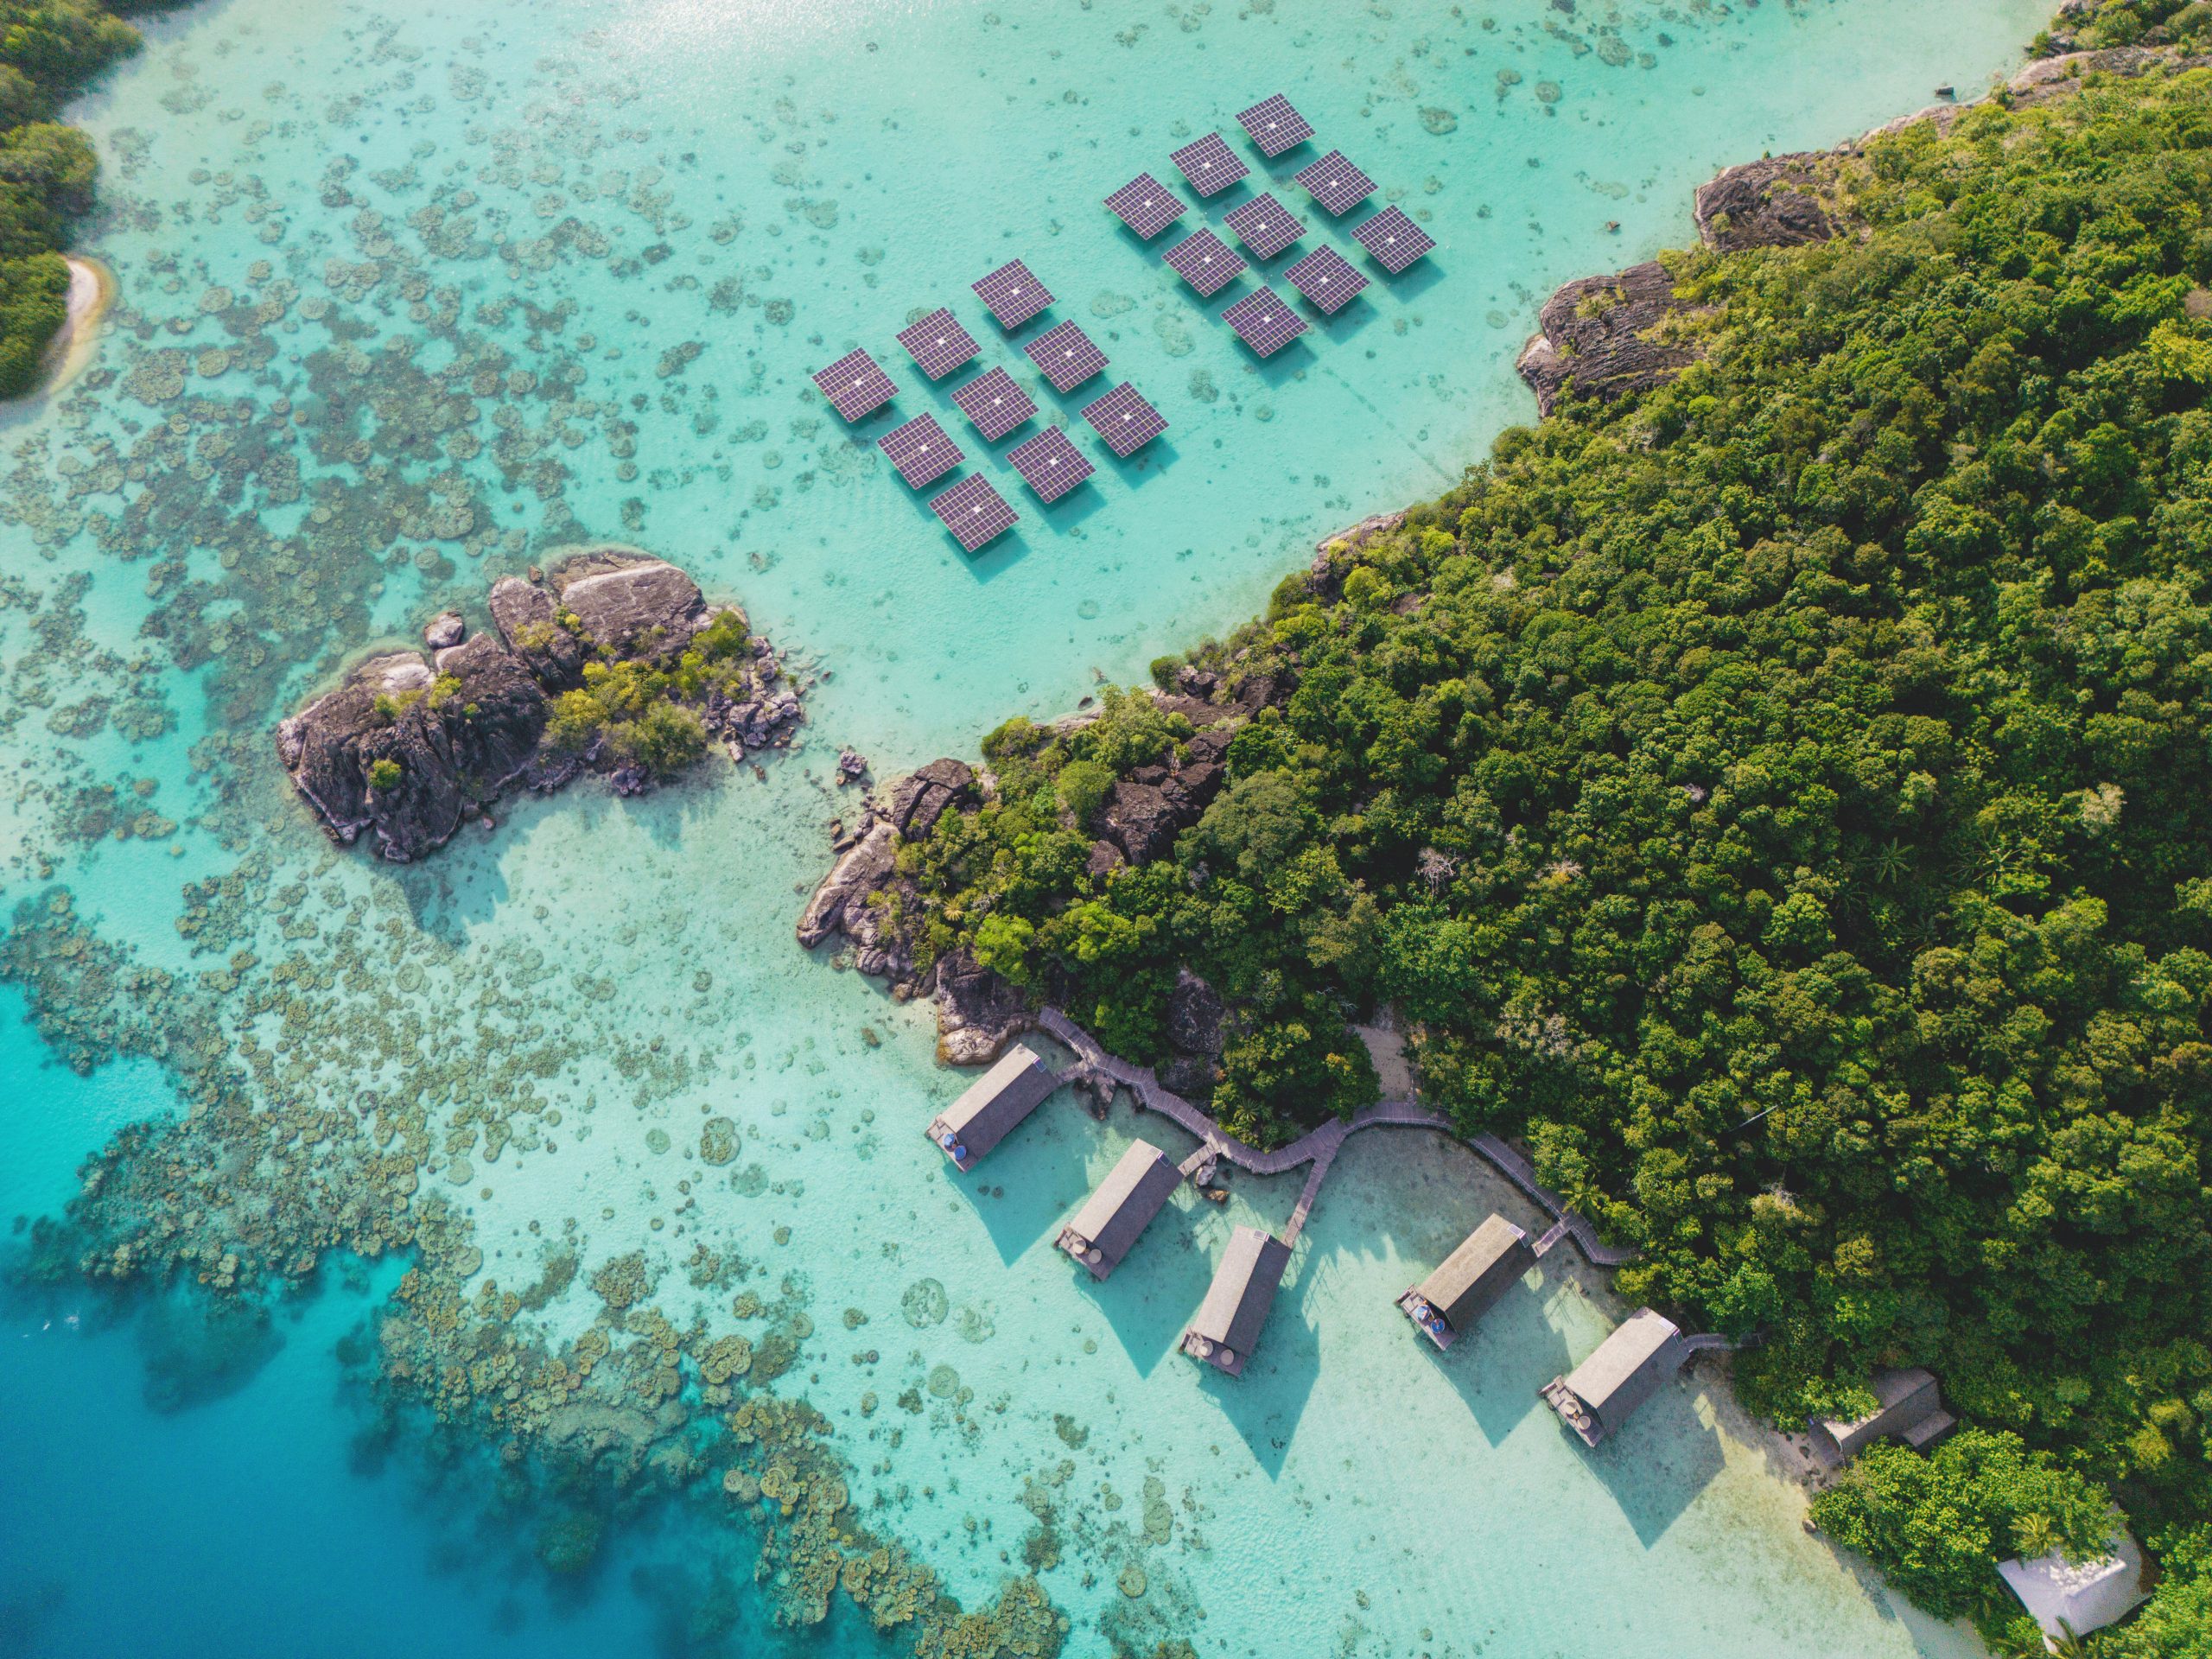
In the remote waters of Indonesia’s Anambas Islands, Bawah Reserve is redefining what it means to blend barefoot luxury with environmental stewardship.
Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”