

Saudi Arabia Sees a Spike to $180 Oil if Energy Shock Persists Past April
Prices at such a level could trigger a recession or consumer changes that crush demand.

 4 min

Saudi Arabia’s oil officials are working frantically to project how high oil prices might go if the Iran war and its disruption of energy supplies doesn’t end soon—and they don’t like what they are seeing.
The base case, several oil officials in the Gulf’s biggest producer said, is that prices could soar past $180 a barrel if the disruptions persist until late April.
While that would sound like a bonanza for a kingdom still heavily leveraged to oil revenue, it is deeply concerning. Prices that high could push consumers into habits that slash their oil use—potentially for the long term—or trigger a recession that also hurts demand. They also would risk casting Saudi Arabia in the role of profiteer in a war it didn’t start.
“Saudi Arabia generally does not like too-rapid increases in oil, because that then creates long-term market instability,” said Umer Karim, an analyst of Saudi foreign policy and geopolitics with the King Faisal Center for Research and Islamic Studies. “For Saudis, the ideal equation is a relatively modest increase in prices while their market share remains stable.”
Saudi Aramco, the country’s national oil company, which handles production, sales and pricing, declined to comment.
This week’s strikes targeting energy facilities have pushed oil prices higher . In retaliation for an Israeli strike Wednesday on Iran’s South Pars gas field , Tehran hit facilities in Qatar’s Ras Laffan energy hub and attacked other Gulf infrastructure including Saudi facilities at Yanbu, the Red Sea end of a pipeline that can take crude around the chokepoint in the Strait of Hormuz .
Iran also continued to hit ships in the Gulf, extending a string of attacks that have all but shut the strait, the narrow conduit for 20% of the world’s oil shipments.
Attacks sent benchmark Brent futures as high as $119 a barrel before easing back Thursday. The contract’s all-time high, reached in July 2008, was $146.08.
“$200 a barrel is not outside the realms of possibility in 2026,” analysts at energy consulting firm Wood Mackenzie said.
Gulf futures tied to Oman crude, which are less liquid but which quickly reflect local supply disruptions, shot past $166 a barrel. Oman is a benchmark for much of the oil sold by Middle East producers such as Saudi Arabia, with tankers of physical crude priced at a fixed spread to the benchmark, which floats up and down each day with the market.
Some Saudi customers are balking at using the benchmark given its volatility, the oil officials said. Aramco, however, is insisting it is a true reflection of supply in the market, they said.
The war has already removed millions of barrels of oil from global supply. Prices are up by around 50% since the conflict began Feb. 28.
Modellers at Saudi Aramco need to assess the direction of the market in time to release the official selling prices for their crude by April 2. They pull in a number of inputs, including soundings on customer demand from staff who handle oil sales.
Saudi Arabian light crude is already being sold to Asian buyers via its Red Sea port for around $125 a barrel. As extra oil in storage—some of which was shipped out of the Gulf ahead of the war—is used up, physical shortages will bite more deeply next week, causing prices to close in on $138 to $140, the officials said.
By the second week of April, with no easing of the supply disruptions and the Strait of Hormuz remaining closed, the Saudi officials said they expected prices could hit $150 before stepping up to $165 and $180 in the weeks ahead.
Oil traders are also putting bets on much higher prices, though many remain far lower than Aramco’s most dire scenario. Wagers that Brent futures will hit $130, $140 or $150 a barrel next month were among the most popular positions in the options market on Wednesday, according to Intercontinental Exchange data. A smaller but growing number of traders are betting prices could shoot up even further.
“The market isn’t acting like this is an end-of-March thing any more,” said Rebecca Babin, a senior energy trader for CIBC Private Wealth, referring to an ending for the war. “I don’t think $150 is out of the question in another month…You start talking about June, I’ll give you $180.”
Many variables could keep prices from going that high, among them an end to the fighting or freed-up barrels from sanctioned producers such as Russia contributing to global supply. Demand could also fall, which would bring prices back down but potentially only in tandem with a recession.
Energy producers are scrambling to figure out how high prices can go before buyers start cutting back, a phenomenon called demand destruction.
“Generally, $150 Brent is where people will really start to put their pencils down and do the math,” Babin said.
At that price, analysts say, Americans might start taking the bus, working from home or rethinking their summer vacations. Manufacturers could slow down rather than operate uneconomically.
The more relevant price for most consumers is at the pump. Gasoline demand tends to start declining once prices exceed $3.50 a gallon, according to James West of Melius Research.
For many, prices are already there. Americans’ average retail prices for gasoline jumped to $3.88 a gallon Thursday, according to AAA, up from $2.93 a month ago. Drivers in Arizona, New Mexico and Colorado have faced the starkest sticker shock.
Diesel’s even more rapid price surge, to $5.10 a gallon, is already hitting companies that rely on the fuel to move everything from produce to semiconductors to steel nationwide.
“Higher fuel costs act like a tax on consumers and businesses, forcing households to spend more on energy and less elsewhere,” said Philip Blancato, chief executive at Ladenburg Asset Management.
Another big risk to demand comes from industrial users curtailing consumption and from the broad economic contraction that can accompany oil shocks, according to Wood Mackenzie.
That pullback in demand would likely initially hit energy-poor countries in Asia and Europe, where prices for jet fuel, diesel and more already are skyrocketing.
An adviser working with Saudi Aramco said the company is weighing a scenario in which the rapidly rising cost of oil imports in Europe, Japan and Korea puts downward pressure on their currencies, raising their effective cost of energy, driving inflation and interest rates up, and eventually slowing their economies and demand.
Analysts warn that a continued run-up in U.S. prices could eventually hit the U.S. , the world’s largest oil producer.
Federal Reserve Chair Jerome Powell said Wednesday that persistently higher energy costs would buoy price pressures and ding growth.
While the U.S. has become a major energy exporter in recent years, Powell said, “The net of the oil shock will still be some downward pressure on spending and employment and upward pressure on inflation.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


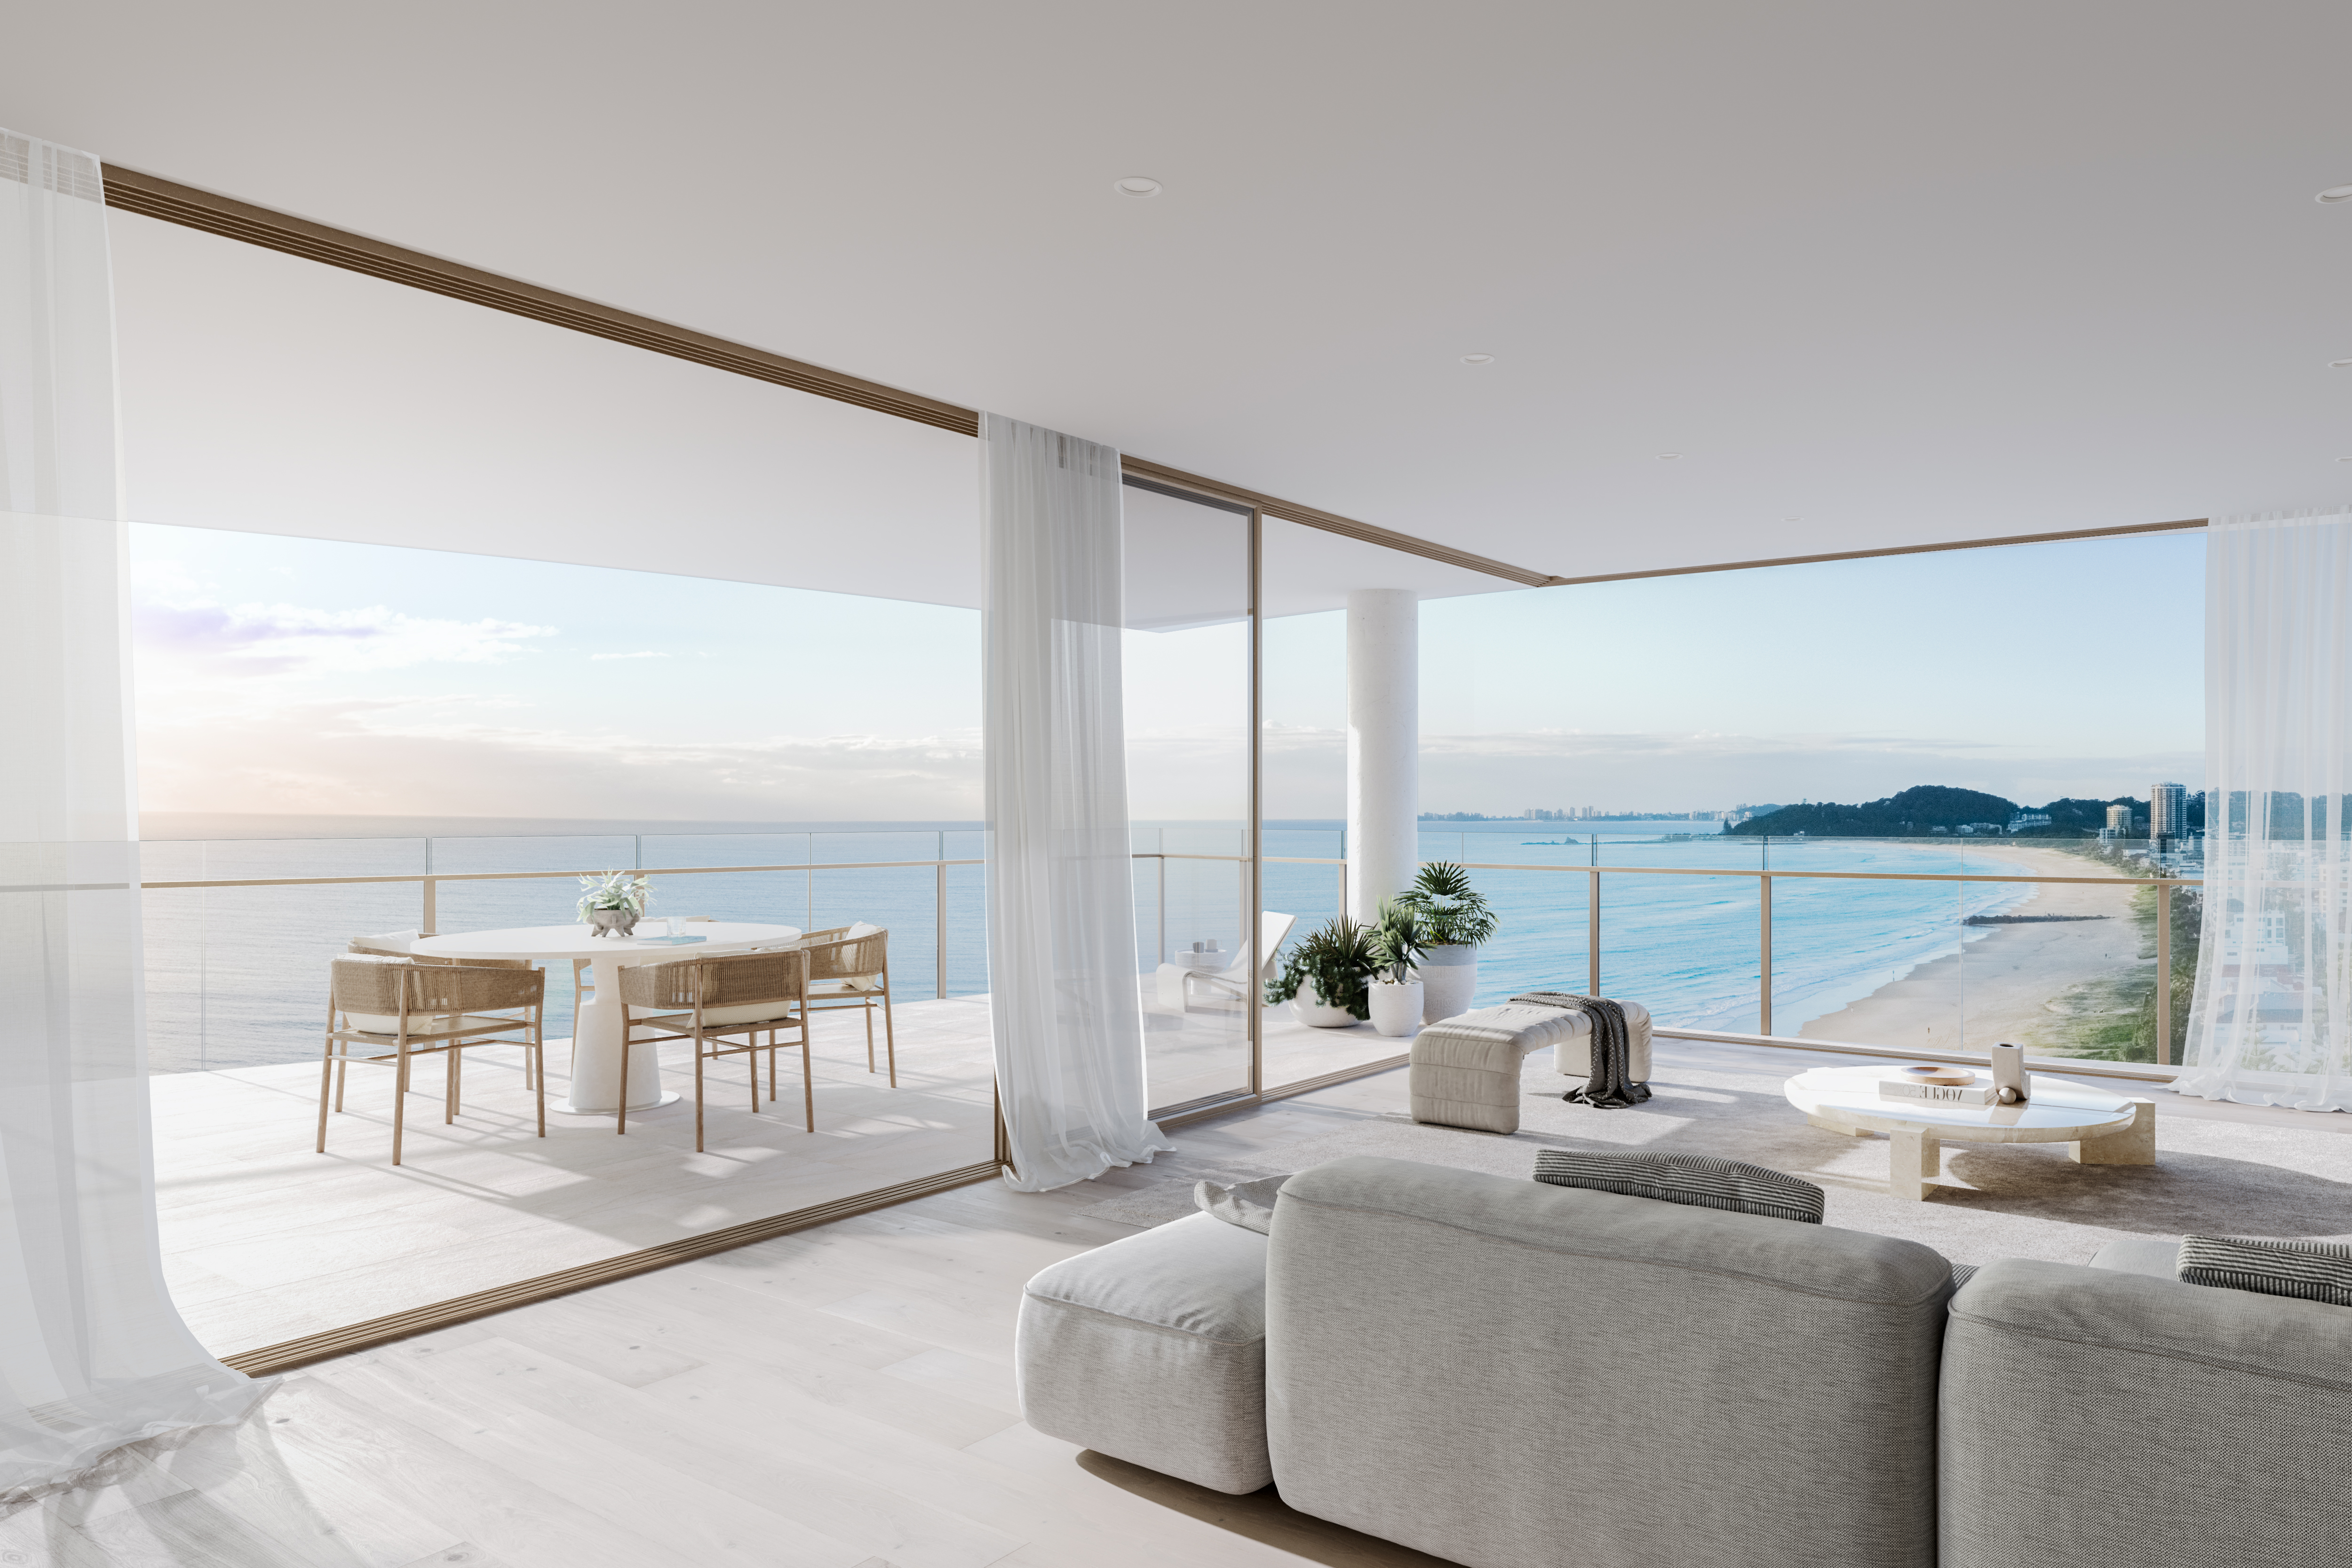
A Sydney couple has paid $15.5 million for the Grand Penthouse at Marquee’s $285 million La Belle Residences beachfront development which is nearing completion at Palm Beach, eclipsing the record for an off-the-plan apartment sale on the southern Gold Coast. The sprawling single level 640 sqm beachfront residence, with sweeping views of the Gold Coast …
Continue reading “$15.5m La Belle Penthouse eclipses southern Gold Coast record”
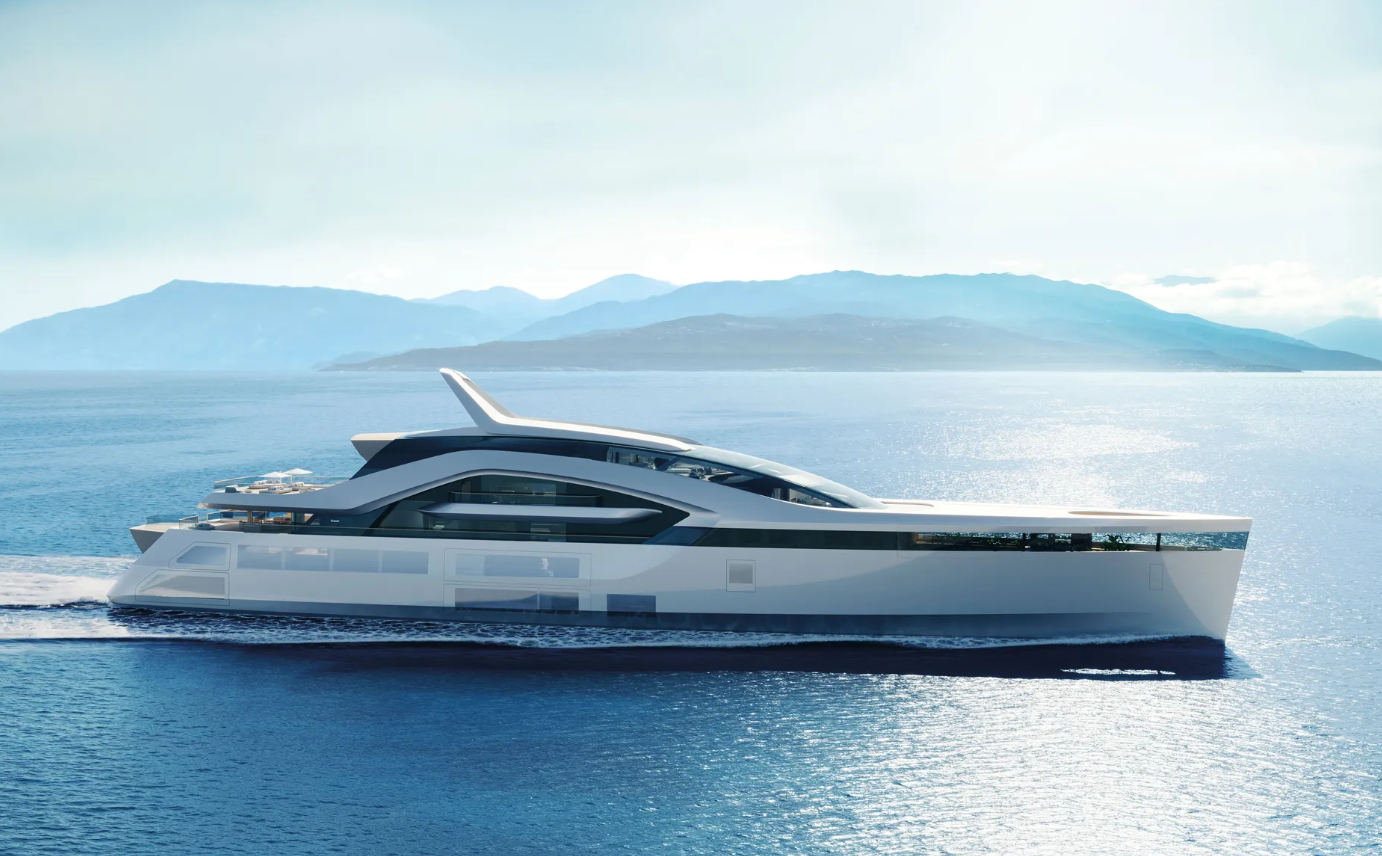
On the owner’s deck, a 20-metre swimming pool incorporates Feadship’s patented ContraWave technology and extends indoors as a suspended, glass-bottomed infinity pool.
The ASX 200 rose 1.28 per cent in the week ending 30 October as miners rallied, consumer stocks fell and rate-rise expectations climbed
6 min
The Australian sharemarket rose during four of five sessions in the week ending 30 October, but the headline gain concealed a sharp divide between recovering miners, rate-sensitive property stocks and retailers hit by inflation and weaker trading updates.
The Australian sharemarket finished October with a positive week, although the route higher was anything but uniform.
The S&P/ASX 200 closed Friday 30 October at 8,908.1, gaining 112.9 points, or 1.28 per cent, from the previous Friday’s close of 8,795.2.
The All Ordinaries advanced 1.34 per cent to 9,025, while the more concentrated S&P/ASX 20 gained 1.11 per cent.
The benchmark rose during four of the week’s five sessions. It added 0.17 per cent on Monday and 0.46 per cent on Tuesday, before slipping 0.03 per cent on Wednesday. It recovered 0.50 per cent on Thursday and gained another 0.18 per cent on Friday.
The index briefly reached 8,933.3 but again failed to establish itself above the psychologically important 9,000-point mark.
The week’s central tension was between a resources recovery and a less forgiving domestic interest-rate outlook.
Materials gained 4.06 per cent, reclaiming part of the previous week’s heavy fall. Australian real estate investment trusts rose 3.77 per cent, financials gained 1.05 per cent and energy advanced 1.39 per cent.
At the other end of the market, consumer staples fell 5.13 per cent and consumer discretionary shares lost 2.35 per cent. Utilities declined 0.73 per cent and communication services eased 0.68 per cent.
Inflation changes the conversation
Australia’s September inflation data was the week’s pivotal domestic release.
Annual inflation of 4.3 per cent pushed market pricing towards another possible Reserve Bank increase and disrupted Wednesday’s early sharemarket rally.
By Thursday’s close, one widely followed market measure placed the probability of an increase in the cash rate to 4.85 per cent at approximately 80 per cent.
That pricing does not make an increase certain. It does, however, change the framework through which investors assess Australian businesses.
Companies dependent on discretionary household spending face renewed pressure on sales and margins. Property trusts, banks, developers and highly leveraged companies must be considered against the prospect of higher funding costs.
Banks present a more complicated equation. Higher rates can support margins, but they may also slow credit growth and increase arrears.
Miners recover
BHP gained 4.56 per cent across the week to close at $57.56, making a substantial contribution to the benchmark’s rise.
The recovery followed an 8.3 per cent fall during the previous week and helped lift the broader materials sector.
Northern Star Resources added 4.59 per cent, while Goodman Group advanced 6.85 per cent to become the strongest performer in the ASX 20.
The commodities picture was mixed. Gold fell approximately 3.12 per cent on the cited weekly measure, while Brent crude added around 0.68 per cent.
The Australian dollar was little changed at approximately US70.35 cents at the reference point.
Supermarkets and consumer shares retreat
The consumer-staples story was markedly weaker.
Coles fell 11.77 per cent after its first-quarter update, making it one of the largest significant-company declines of the week.
Woolworths lost 3.66 per cent and Wesfarmers fell 4.48 per cent to $76.69 as investors processed company trading commentary against the prospect of another squeeze on household demand.
The moves illustrate how quickly expectations can change when an apparently defensive company disappoints.
Supermarkets still benefit from the recurring need for groceries, but customers can trade down, shift between chains and reduce spending on higher-margin discretionary lines.
Wesfarmers carries exposure to several consumer categories through businesses including Bunnings, Kmart and Officeworks. A renewed rate increase would place more pressure on households already confronting higher prices.
The wider market’s biggest movements
Among companies outside the ASX 20, Mesoblast surged 27.32 per cent, SiteMinder gained 22.74 per cent and Zip rose 22.60 per cent.
The sharpest weekly falls included 4DMedical, down 33.51 per cent; Tuas, down 29.95 per cent; Catalyst Metals, down 17.47 per cent; and Champion Iron, down 13.35 per cent.
Those percentages require context.
The movements in BHP, Commonwealth Bank and other very large companies had substantially more influence on the index than similarly dramatic changes among smaller companies.
A 20 per cent move in a relatively small stock may attract more attention than a two per cent rise in a major bank, but the bank can have the greater effect on the market.
How the ASX 20 moved
The following list uses the S&P/ASX 20 constituents and five-session movements reported at the 30 October close.
Where the component feed did not publish a valid five-day comparison, no figure has been estimated.
BHP Group: Up 4.56 per cent
Commonwealth Bank: Up 1.66 per cent
Rio Tinto: Down 2.20 per cent
National Australia Bank: Up 0.48 per cent
Westpac: Up 0.08 per cent
ANZ Group: Up 1.92 per cent
CSL: Up 2.05 per cent
Macquarie Group: Up 2.19 per cent
Wesfarmers: Down 4.48 per cent
Woodside Energy: Up 1.43 per cent
Goodman Group: Up 6.85 per cent
Telstra: Five-day comparison unavailable from the cited component feed
Woolworths: Down 3.66 per cent
Fortescue: Five-day comparison unavailable from the cited component feed
Transurban: Down 2.40 per cent
QBE Insurance: Down 1.21 per cent
Aristocrat Leisure: Up 0.63 per cent
Northern Star Resources: Up 4.59 per cent
Sigma Healthcare: Down 0.36 per cent
Brambles: Down 1.20 per cent
The companies dominating the conversation
Coles was the week’s standout media-facing company for the wrong reason.
Its trading update produced an outsized repricing and drew attention across the grocery and retail sectors. Woolworths and Wesfarmers were also scrutinised as investors considered how stubborn inflation and another possible rate rise could affect sales volumes.
Bank of Queensland offered a more positive corporate signal.
The bank reported that its FY26 net interest margin had risen six basis points to 1.70 per cent, ahead of the 1.68 per cent expected by the market according to contemporaneous reporting.
Bank of Queensland shares rose 5.8 per cent on Thursday, while the major banks also rallied.
Endeavour Group finished Friday at $3.39, up 4.31 per cent on the day, and released the results of its annual general meeting.
The movement was notable during a week in which investors were highly sensitive to consumer-facing companies. The AGM result should not, however, be presented as the sole cause of the share-price increase without further supporting company guidance.
Mesoblast’s 23.4 per cent Thursday rise and 27.32 per cent weekly gain returned the biotechnology company to the centre of market attention.
For editors, it is important to separate the size of that percentage movement from its influence on the index. Mesoblast was an eye-catching performer, but it did not drive the ASX 200 in the way BHP or Commonwealth Bank did.
Qantas remained part of the broader market conversation as investors watched travel demand and company updates.
However, the primary-source review did not locate a fresh Qantas announcement that justified attributing a major weekly market movement to new company information. The airline should therefore remain on the monitoring list rather than being forced into the week’s causal narrative.
Is Australia’s IPO market reopening?
The official ASX new-listings pipeline remains active but selective.
ASX’s upcoming-floats page included formal applications with offer timetables extending through October and at least one anticipated listing on 30 November.
The exchange notes that its page covers companies for which a formal listing application has been received. It does not represent every company privately exploring a float.
The wider debate concerns whether Australia’s public market is sufficiently competitive when high-growth businesses can pursue capital in the United States or remain privately funded for longer.
ASX has previously raised possible reforms designed to improve the attractiveness of the local market. These include debate about reducing minimum free-float requirements and streamlining aspects of the admissions process.
An enhanced fast-track pathway for qualifying applicants can shorten the review process, reducing the execution risk created when market conditions change during a long IPO timetable.
That does not remove the more fundamental challenge.
New floats still require credible earnings or a convincing growth pathway, sensible pricing and enough genuine free float to support trading after listing.
Investors can already obtain diversified exposure through low-cost exchange-traded funds or buy established, liquid businesses. A float must therefore offer more than novelty.
The current pipeline suggests that the IPO window is open, but it is not indiscriminate.
What investors will watch next
The Reserve Bank’s next decision now sits at the centre of the domestic outlook.
Any change in cash-rate expectations will flow rapidly through banks, retailers, property trusts, listed developers and companies carrying substantial debt.
Investors will also watch whether the materials recovery can continue, whether BHP can hold its rebound and whether consumer companies provide further evidence of slowing demand.
Overseas, technology-sector volatility, commodity prices and the United States interest-rate outlook will continue to shape Australian trading.
The week’s 1.28 per cent headline gain was encouraging, but it was not a broad declaration of confidence.
It was a rotation towards miners, selected financials and property securities—and away from consumer businesses facing a more difficult inflation and interest-rate equation.
Market dashboard
S&P/ASX 200: 8,908.1, up 1.28 per cent for the week
All Ordinaries: 9,025, up 1.34 per cent
S&P/ASX 20: 5,214.7, up 1.11 per cent over five sessions
Best sector: Materials, up 4.06 per cent
Next-best sector: A-REITs, up 3.77 per cent
Weakest sector: Consumer staples, down 5.13 per cent
Major large-cap winner: Goodman Group, up 6.85 per cent
Major large-cap loser: Coles, down 11.77 per cent
AUD/USD: Approximately US70.35 cents at the weekly reference point
Gold: Approximately US$3,885 an ounce, down 3.12 per cent on the cited weekly measure
Brent crude: Approximately US$117.70 a barrel, up 0.68 per cent on the cited weekly measure
Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”
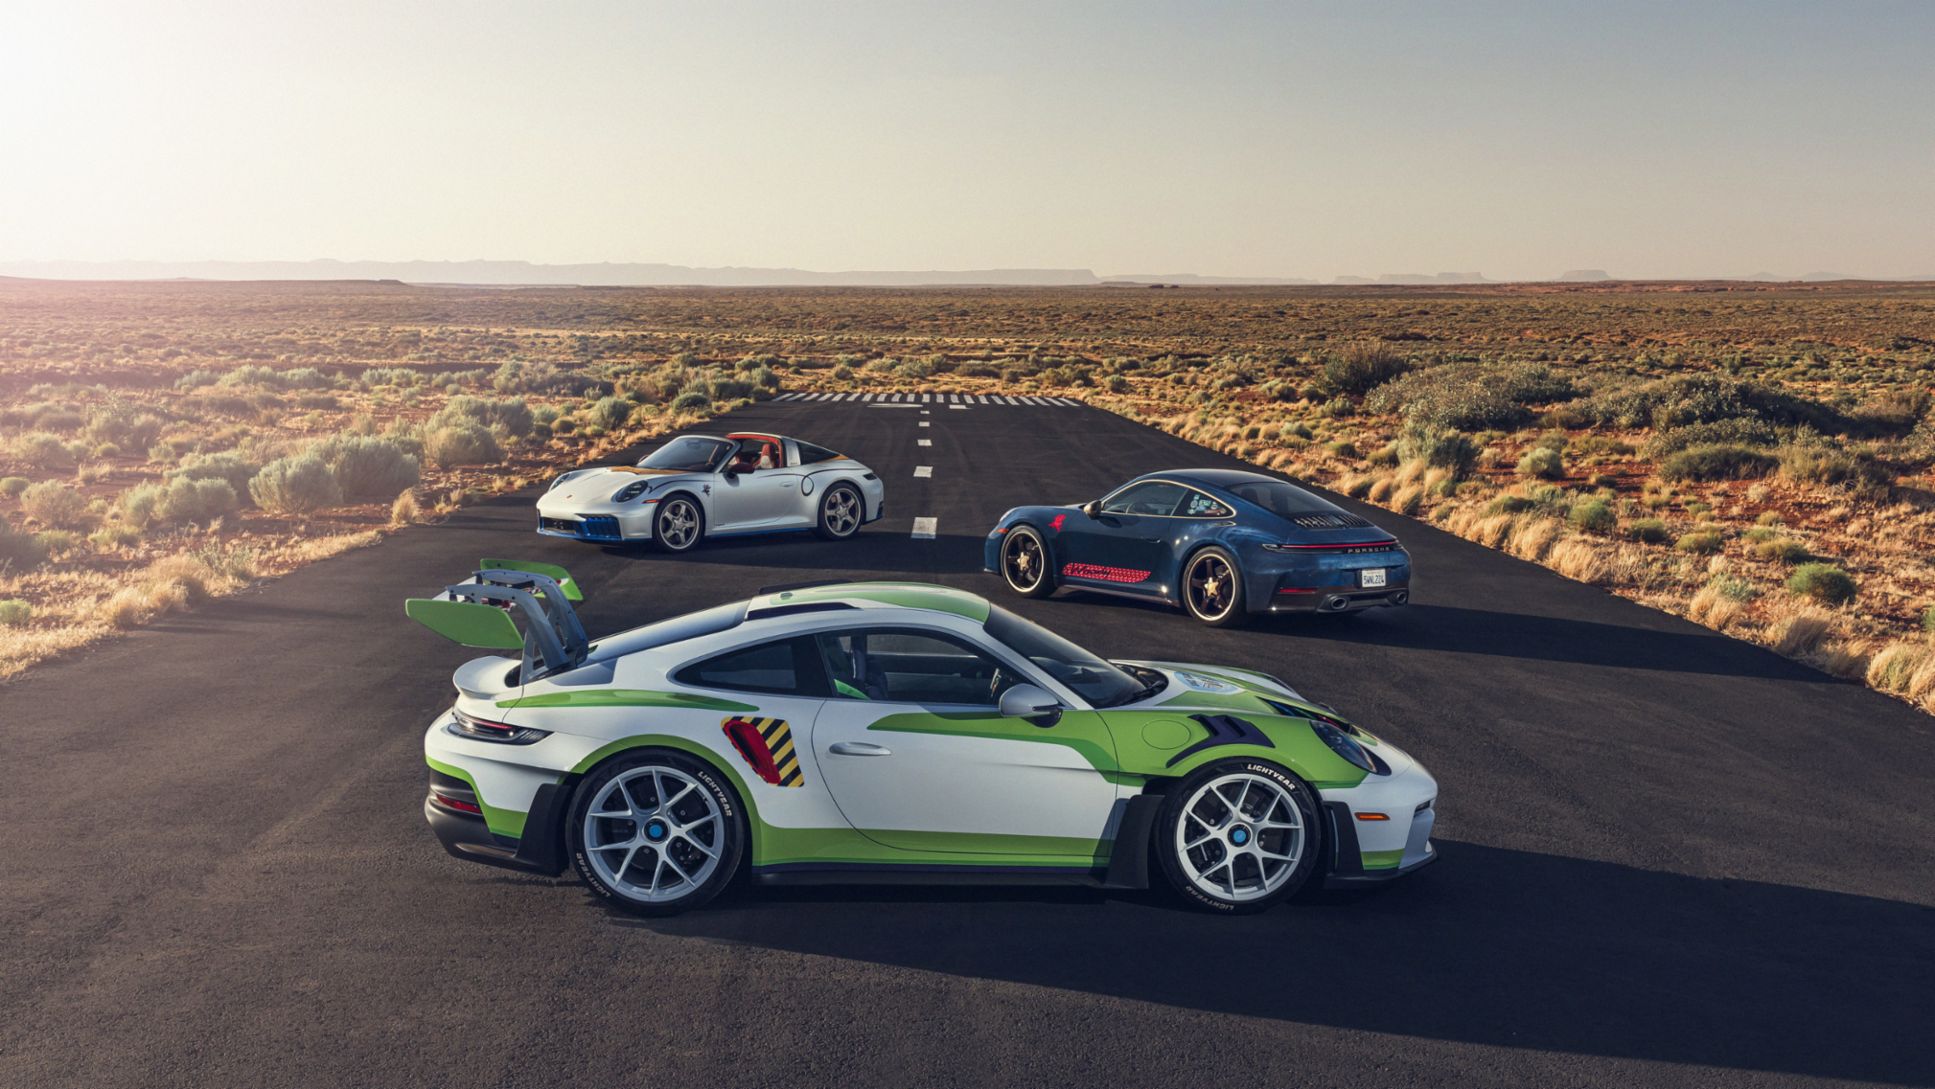
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation