Meet the Woman Taking the ‘Blood Sport’ out of Buying a Coveted Hermès Birkin Bag

 4 min
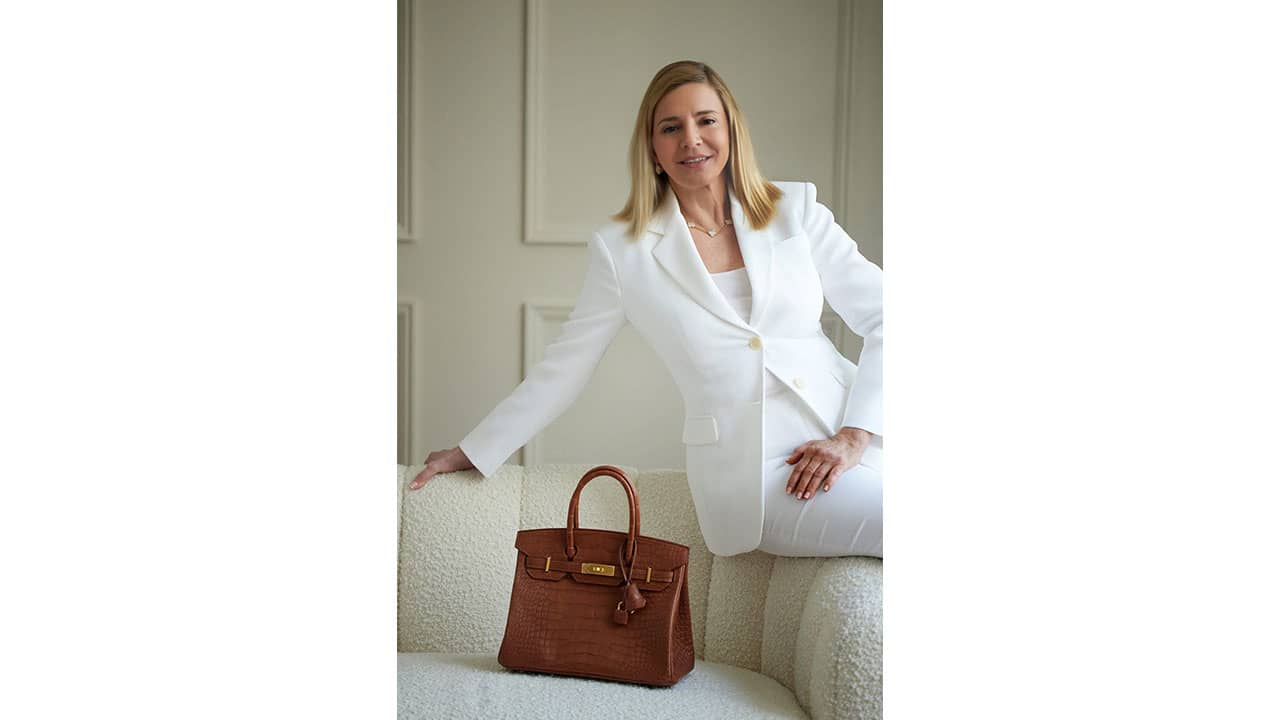
The impetus for Judy Taylor to start her luxury handbag and jewellery resale company Madison Avenue Couture dates back to her career in investment banking more than two decades ago. At the time, she was an avid shopper for high-end clothing and had built a sizeable collection of corporate wear from designer labels.
Taylor eventually took an extended break from banking to travel the world and decided to sell the clothing on eBay.
“I was surprised at the money I netted by selling these used items and realised the potential of the online resale market,” Taylor says. “Not being someone to let an opportunity pass, I began to buy and sell new and almost new luxury clothing, shoes and handbags and saw how much they were in demand.”
Courtesy of Madison Avenue Couture
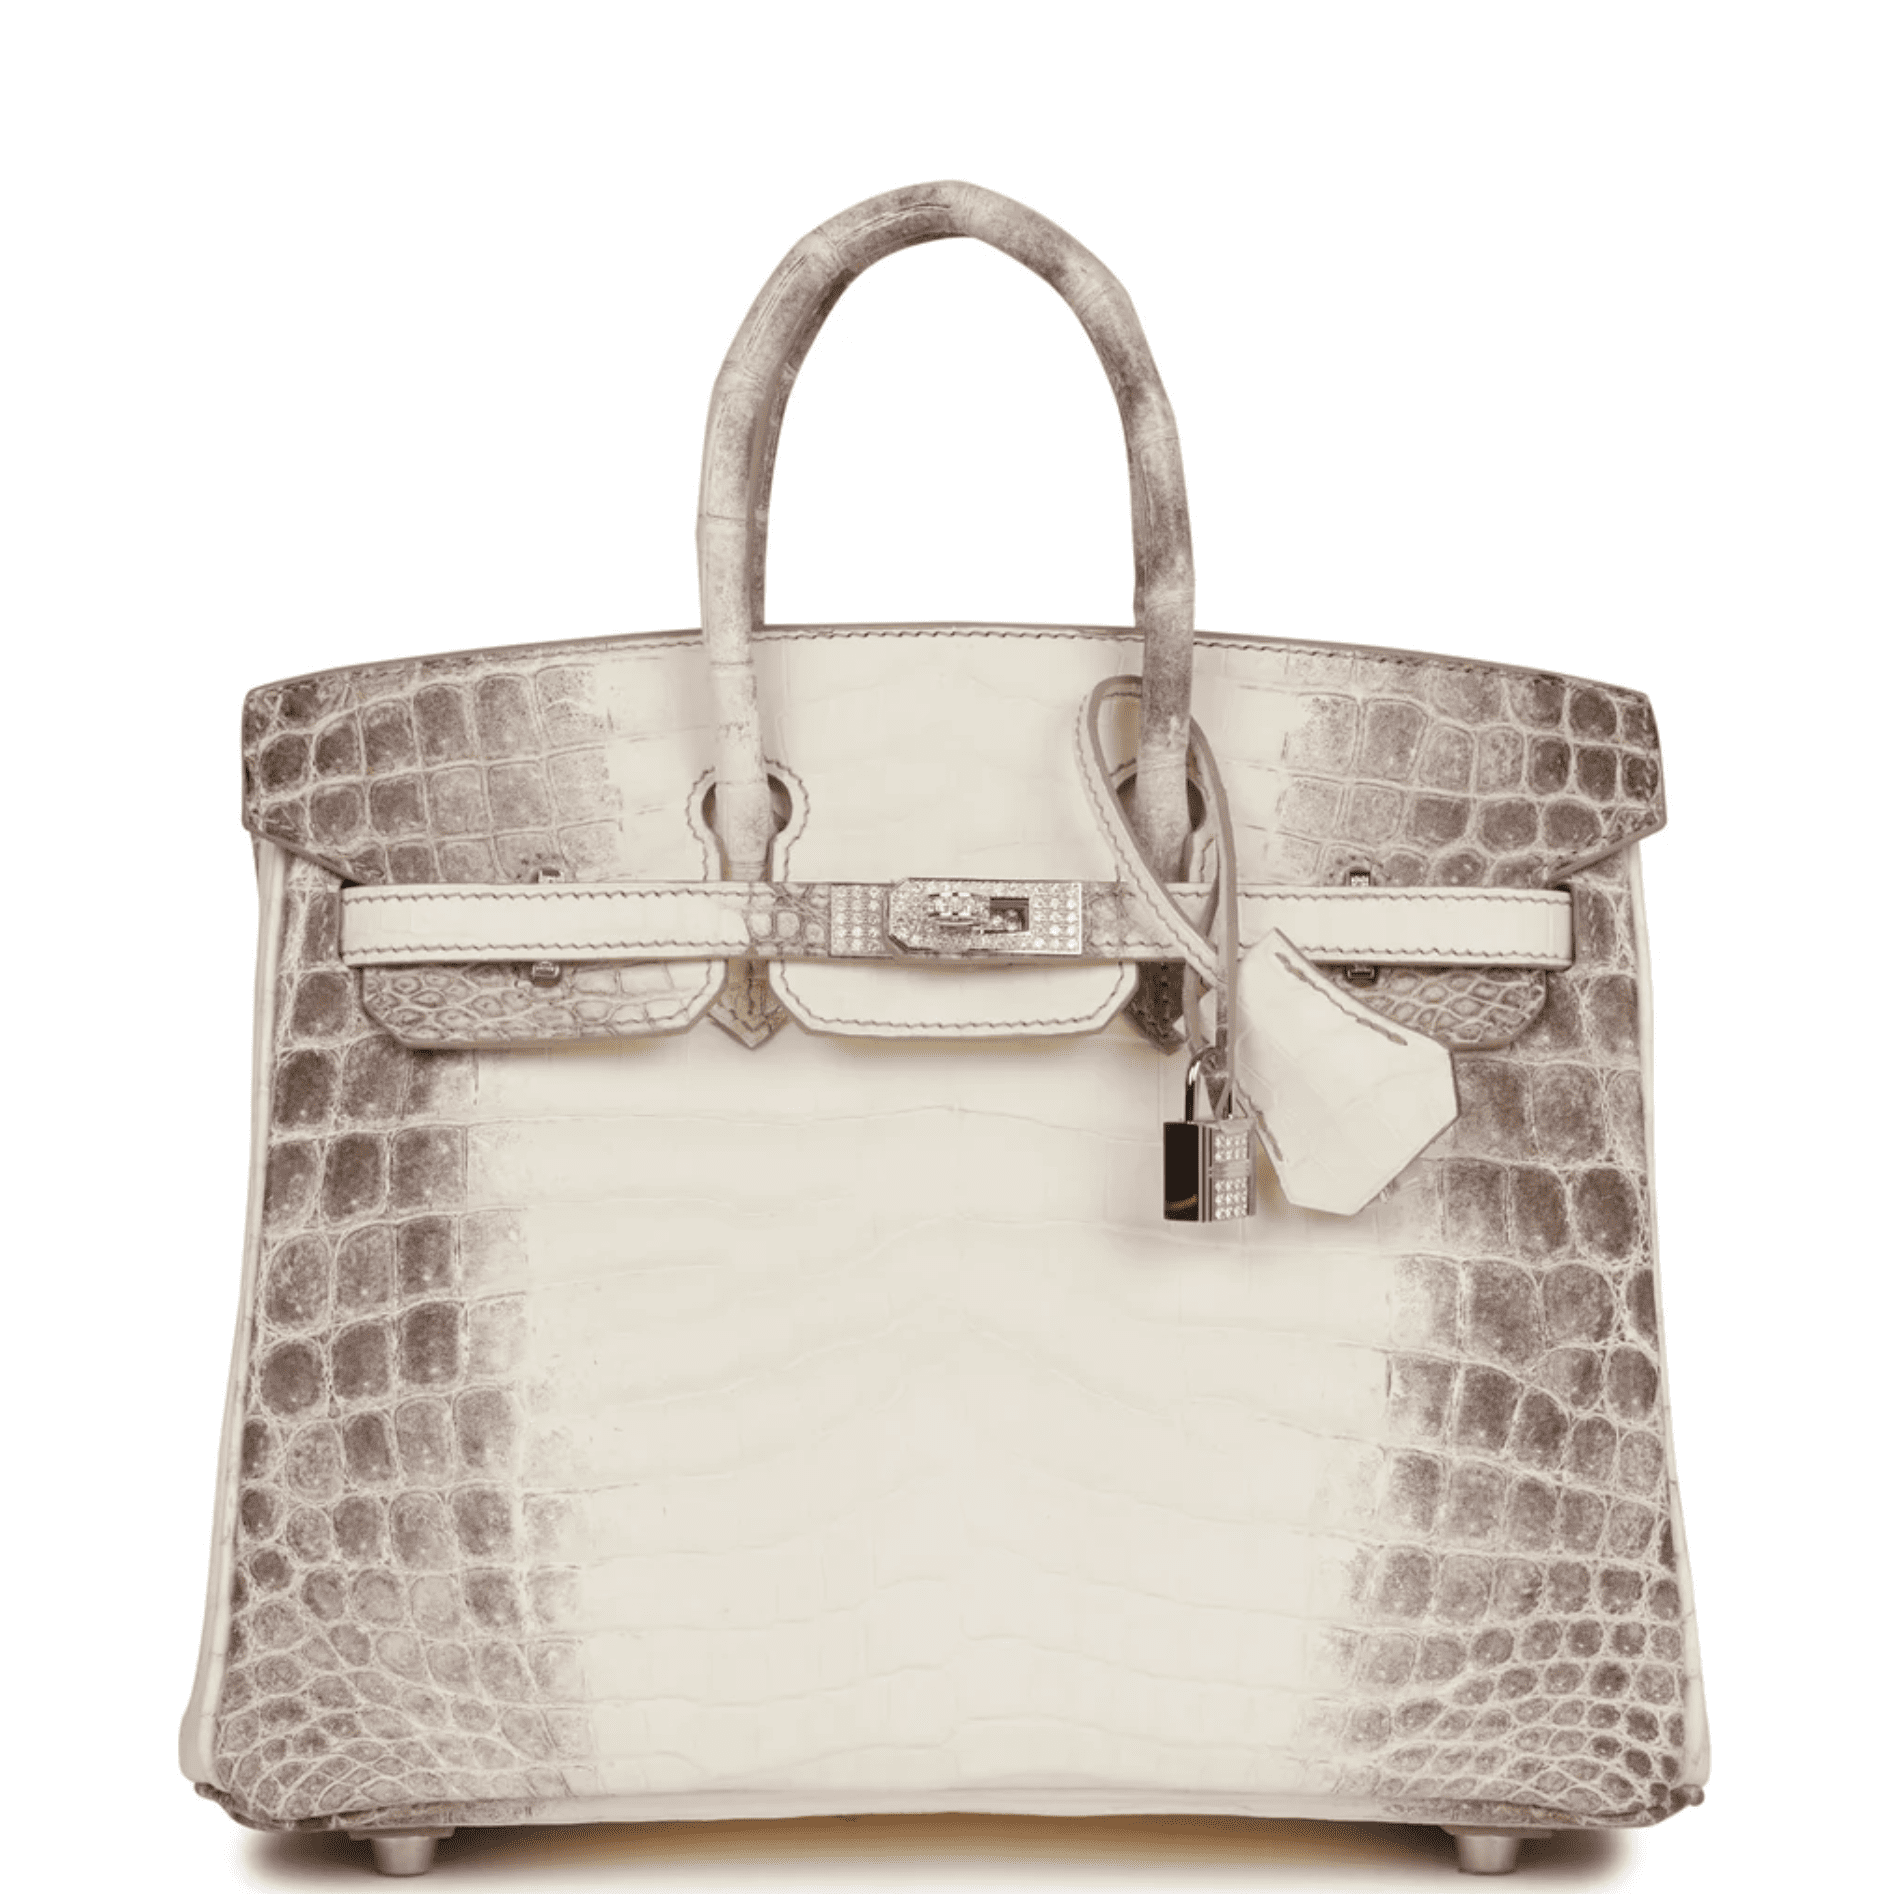
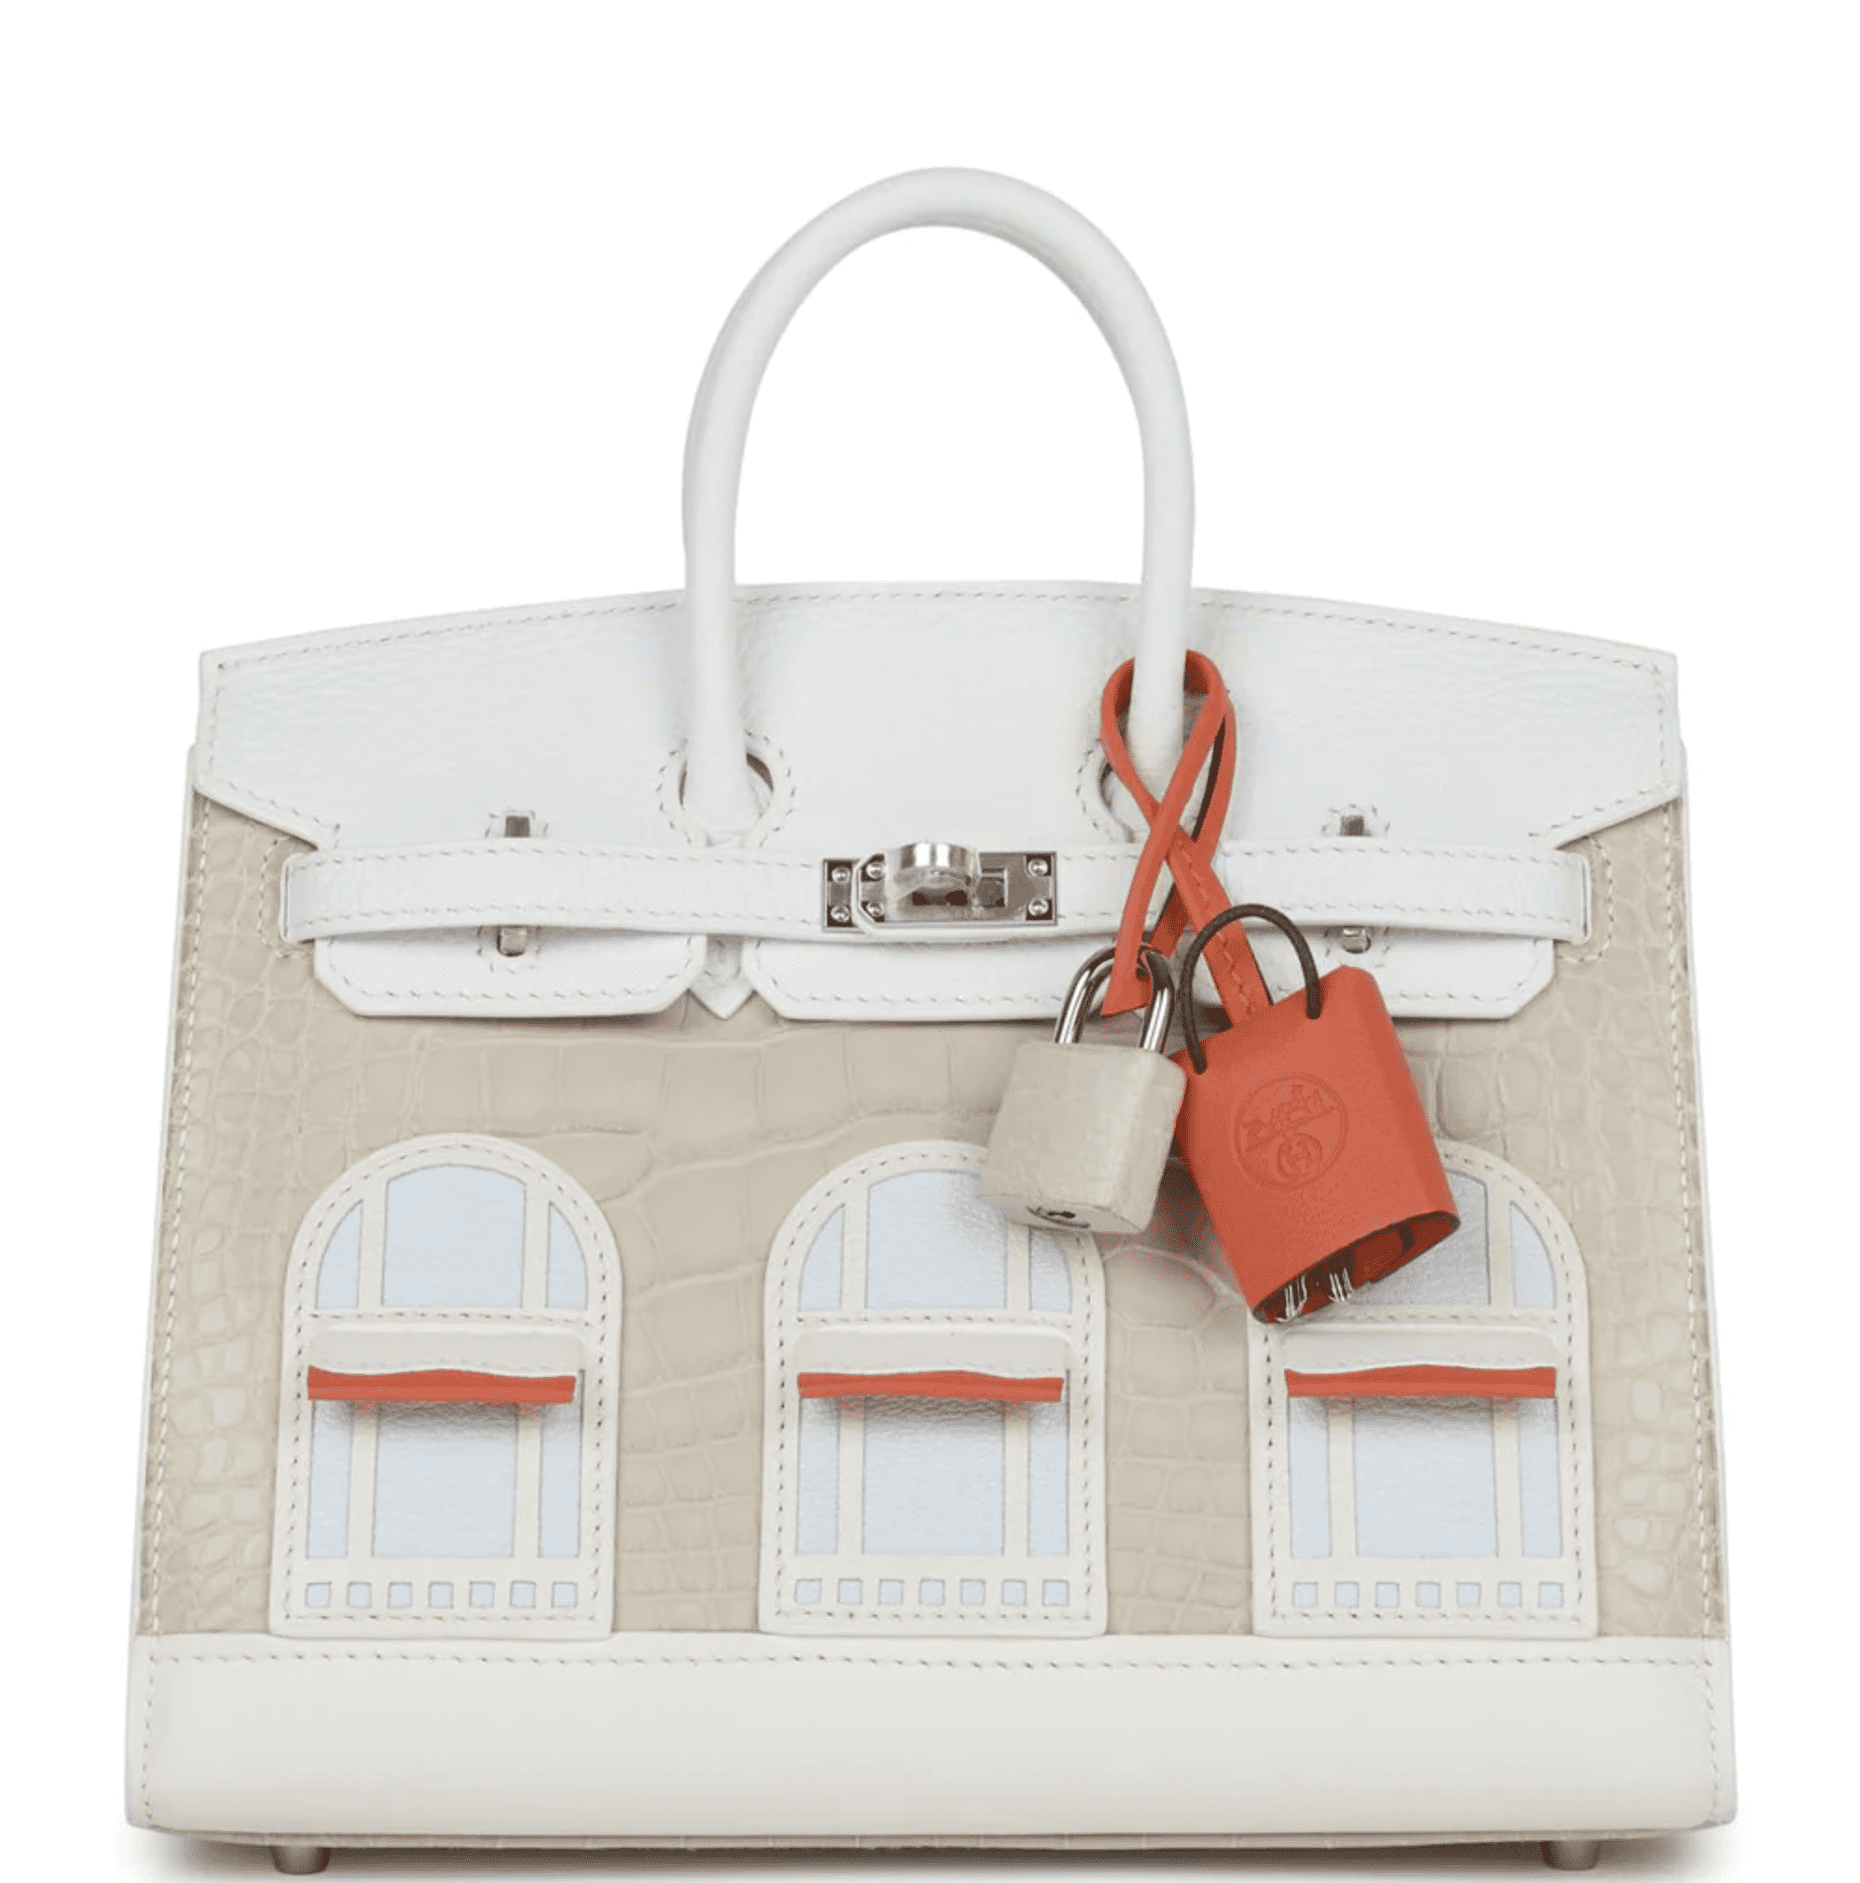
Her homespun venture quickly grew into a full-fledged profitable business, and in 2010, she established Madison Avenue Couture. Today, the brand bills itself to be the largest online independent reseller of new and never-worn Hermès holy grail bags, primarily Birkins and Kellys that are nearly impossible to find. It also sells a selection of pre-owned collectible and vintage Hermès, Chanel, Goyard, and Louis Vuitton bags, Hermès and Chanel jewellery, and accessories and sought-after fine jewellery.
Taylor says that her company enables any consumer with the means to buy highly in-demand goods.
“You can’t just go into Hermès and buy a Birkin because there usually aren’t any available, and if they are, customers are limited to buying two bags a year,” she says. “Chanel has also limited purchases since Covid, and other brands have imposed restrictions.”
According to Taylor, these tactics have increased market demand and have enabled luxury labels to increase their prices. However, since supply cannot meet demand, consumers are increasingly reaching out to the resale market, including her company, for these items.
“Our business continues to grow, and we have an extensive network to source handbags and jewelry,” Taylor says. “Unlike much of the traditional resale market, our items are primarily new and never used and carry a premium over [the] retail price.”
Taylor, 59, speaks with Penta about her company and the luxury resale market overall.
Can you talk about how the luxury resale market for handbags and jewellery has evolved in recent years, especially since the pandemic?
About three weeks into the pandemic, we started getting orders. They were slow at first but then accelerated.
With retail stores closed and travel restricted, people turned online to shop. The only place to purchase new Hermès and Chanel handbags was online and from dealers on the secondary market. They became comfortable with buying these brands online. Sales increased by 60% in 2020 and doubled in 2021, compared to the prior years. Even after the brand boutiques opened and travel resumed, online sales continued their momentum. Our sales quadrupled from 2019 to 2023.23.
Who are your customers, and have they changed over the years?
Our clients are primarily those who have disposable income and love to spend it on beautiful things. Partners of hedge funds, investment bankers and law firms, self-made entrepreneurs, physicians and dentists, celebrities and socialites represent the bulk. But we always have the aspiring—those for whom buying a Birkin or Kelly is a bit of a financial stretch.
What are the advantages of buying a resale bag or piece of jewellery?
Hermès and Chanel do not offer their handbags online. While Hermès.com may offer one or a few small bags on occasion, they are sold out in seconds. The same goes for branded jewellery, notably Van Cleef & Arpels. Try purchasing a popular VC&A Alhambra piece online or in one of their stores to take home immediately—it is almost impossible.
Madison Avenue Couture
The second is ease of purchase. Hermès has made getting a holy grail bag almost a “blood sport.” The machinations that someone goes through to get a Birkin or Kelly are anxiety-producing for most. First, you need to find a friendly sales associate. Then, a profile must be built, which involves spending on Hermès goods that are not leather handbags. The more the spend, the greater the chance of getting a handbag. Expensive furniture, fine jewellery, and watches have the greatest sway. Scarves or a pair of shoes won’t bat an eyelash. The amount needed to be spent is unknown, but we’ve heard it could be significantly more than the price of the bag. Plus, there is no guarantee that it will result in getting the bag of your dreams.
In the secondary market, you can pick the bag of your dreams without the hassle and stress of building a profile.
How do you source your items, and how are you able to guarantee their authenticity?
We purchase from individuals and other handbag dealers primarily. We usually get the original store receipt or a copy of it for most bags we purchase, which establishes provenance. Regardless of having the receipt or not, every bag goes through in-house and third-party authentication. We chose who we believe to be the best independent authenticators of Hermès and Chanel, which is where we find the most counterfeits.
What are some of the most in-demand brands and items for buyers who can afford them?
Hermès and Chanel handbags are generally in demand by professional and affluent women and men who give them as gifts. Goyard is popular because it evokes quiet luxury. In jewellery, we see the greatest demand is for Van Cleef & Arpels pieces, particularly the Alhambra series.
What advice do you have for people who want to find a specific piece from a source outside of the brand itself?
We recommend that people purchase only from dealers who guarantee authenticity and have a history of selling only authentic bags.
Furthermore, rely on a reseller that has its inventory on hand like us. We have already checked the condition, verified authenticity, and confirmed availability. Marketplaces, which aggregate different vendors, cannot know for certain if an item is available, in the stated condition or authentic. (Some authenticate after the item is sold, which delays getting the item.) Resellers that do not have an item in stock will source it, which can take weeks and may not be in the condition described.
This interview has been edited for length and clarity.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Mirzaian is a senior director within CBRE’s Development NSW business, operating across the company’s Western Sydney and North Sydney offices
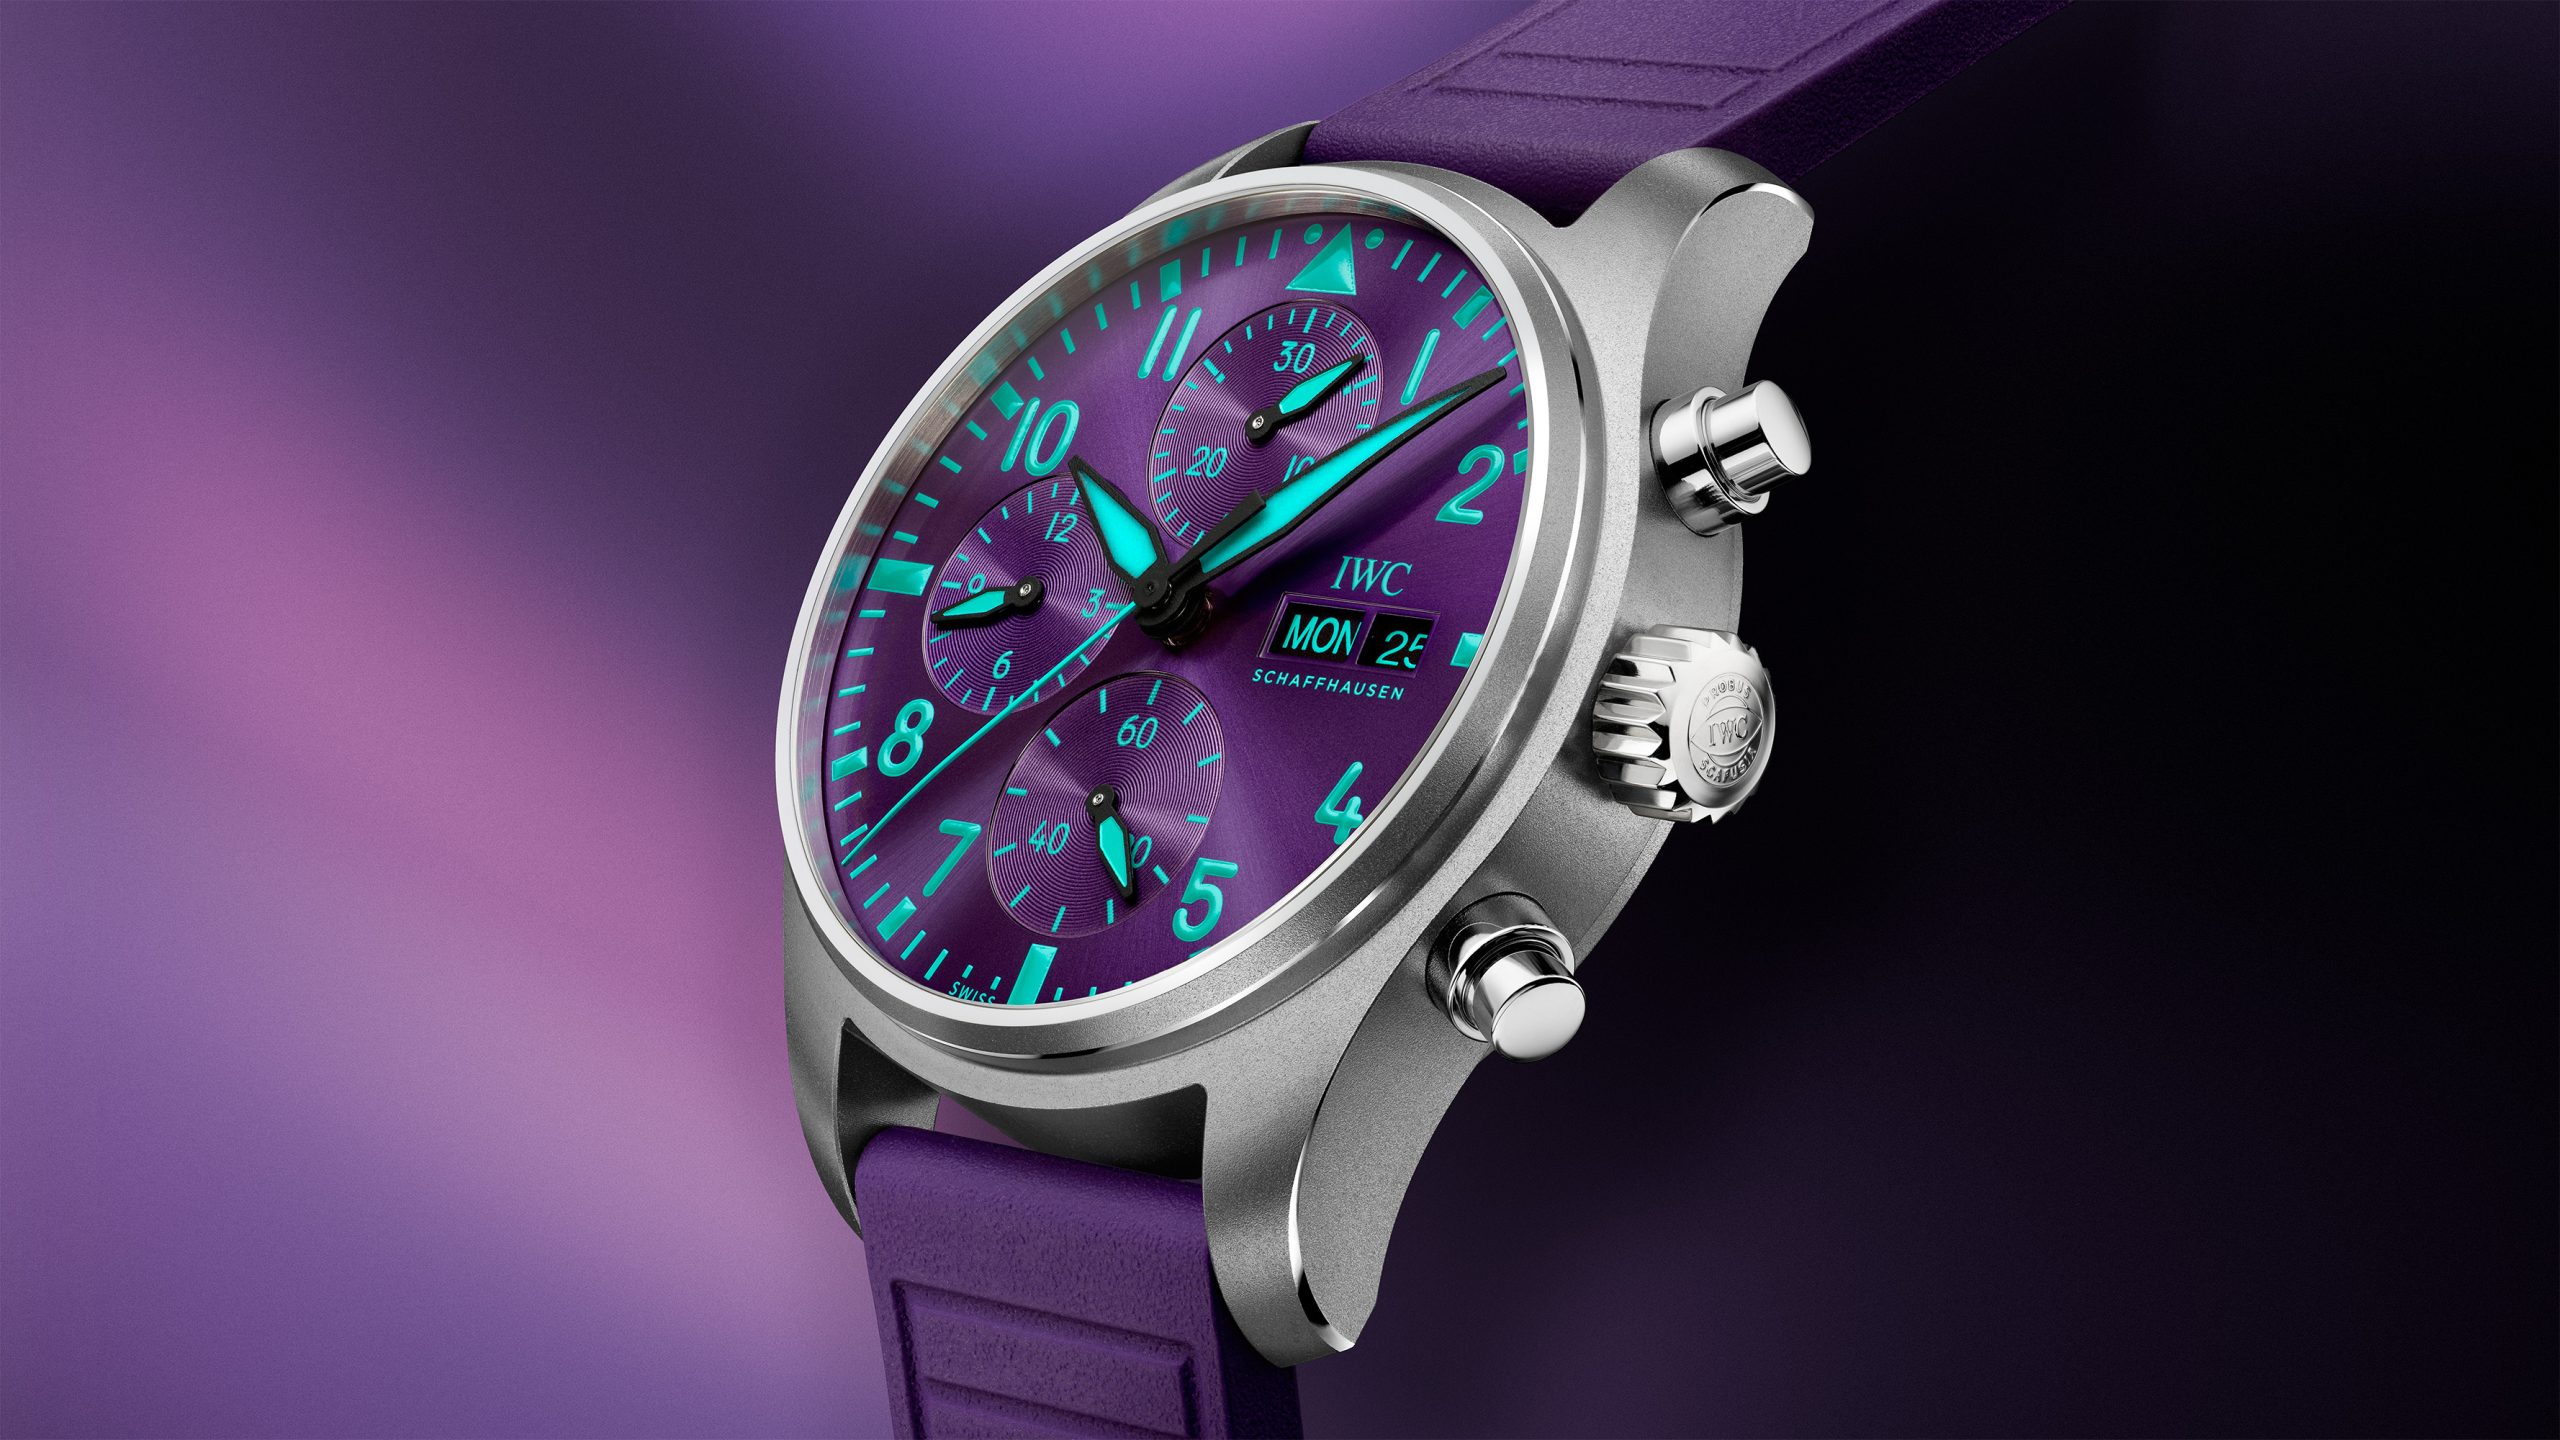
Singapore’s Formula 1 weekend has always looked different. Held beneath floodlights on the Marina Bay Street Circuit, the race transforms the city into a nocturnal spectacle of speed, heat and saturated colour. It is this distinctive atmosphere — and one of Singapore’s most important natural symbols — that has shaped IWC Schaffhausen’s latest motorsport-inspired watch. …
Continue reading “IWC’s purple Formula 1 chronograph pays tribute to Singapore after dark”
Wall Street’s hottest momentum trade has reversed sharply, as former winners tumble and heavily shorted stocks surge.
3 min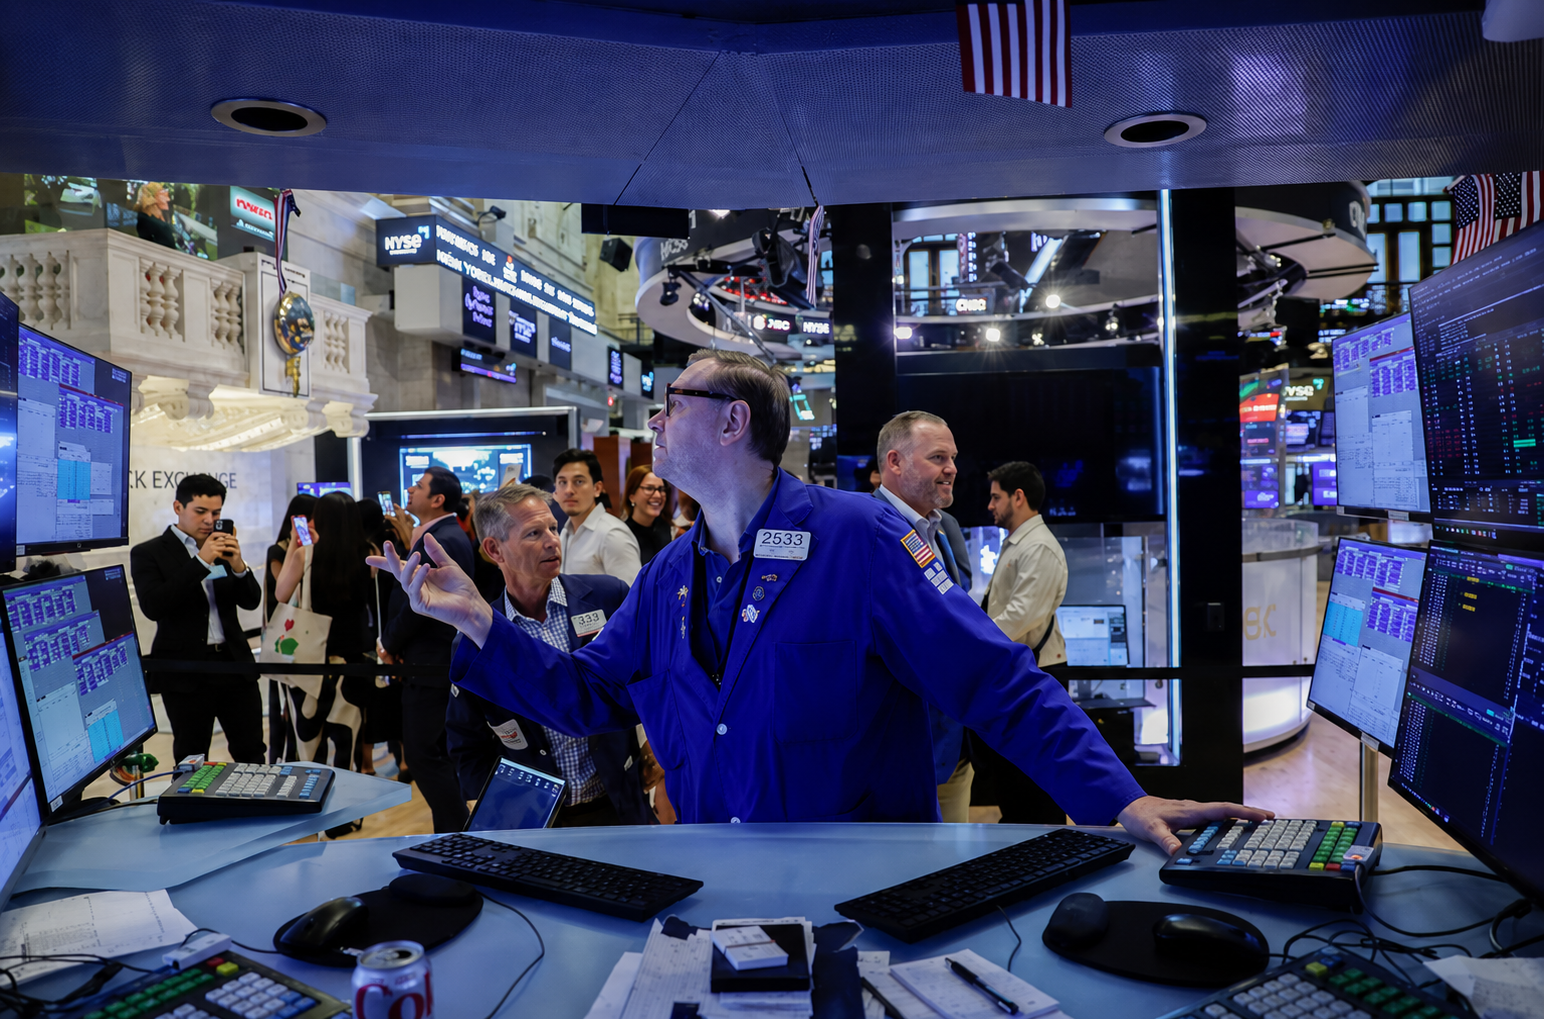
Wall Street’s hottest trade has gone ice cold.
For years, it paid off to buy stocks that were rising in price—and bet against struggling shares. The momentum trade was especially profitable this year, as investors piled into hot stocks including Micron Technology, Nvidia, Advanced Micro Devices and other artificial-intelligence darlings while wagering against those likely to be hurt by the embrace of AI.
The S&P 500 Momentum Index soared 44% in the second quarter, its best quarterly performance on record, and it surged 133% over the past five years, nearly double the broad market’s performance.
Mega funds and rookie investors alike piled into the trade, some using leverage and options contracts in an effort to amplify their returns, propelling the underlying shares higher.
“It is a self-fulfilling prophecy,” said Matthew Tym, managing director at Cantor Fitzgerald, of the trade.
Suddenly, the trade is a loser. The momentum index has tumbled more than 9% since July 1, lagging behind the S&P 500’s 2.8% gain. The index—which tracks stocks in the S&P 500 based on a “momentum score”—is on track for the biggest quarterly underperformance in 25 years. July was the second-worst month for the momentum trade in around 40 years, according to Bank of America estimates; the only month worse was April 2009, in the teeth of the global financial crisis.
Hedge funds that bought momentum shares while shorting low-momentum stocks suffered even more. At the same time, a basket of the most popular stocks held by hedge funds tracked by Goldman Sachs recorded its biggest one-month underperformance in July relative to the S&P 500 in more than 20 years, according to the bank’s analysts.
Momentum trading is based on a rather simple observation: Investments that go up tend to keep outperforming; those that underperform often remain laggards. This kind of trading might seem too simple a stock-picking strategy to work. Yet it often has.
“For decades, it didn’t take a lot of sophistication to run a momentum strategy and make a decent living at it,” says Agustin Lebron, senior researcher at EquiLibre, a trading firm.
Part of the reason: It takes a while for corporate and other information to spread to various investors, so they slowly build positions, producing buying momentum.
“A huge pension fund can’t flip around its positions in a day,” says Lebron. “Behavioral biases also account for some of the effect, as well—people tend to sell their winners too early and hold losers too long.”
Fans of the strategy point to the human tendency to extrapolate from past results—and chase investment returns—noting that momentum patterns have been evident in markets for decades, even centuries. They also say that some of the worst months for momentum strategies are during longer periods of outperformance.
Some have been doing the trade by buying the strongest investments in a sector while shorting the weakest; others lean in to rising markets or asset classes. Still others use a quantitative approach or turn to banks or others who sell ways to make distinct wagers on momentum as a “tradable factor” or a “thematic basket.”
The fans remain believers. “Any strategy has disappointing periods,” says Antti Ilmanen, global co-head of the portfolio solutions group at AQR Capital Management.
The surge in Moderna and other biotech stocks helped crush the momentum trade. These shares were among the most heavily shorted in recent years, but positive news on a cancer vaccine from Moderna and Merck sent those stocks flying, crushing some quant and other hedge funds. Moderna is up around 150% so far this month.
These traders had an especially rough day on Aug. 19, which Goldman Sachs told its clients was the worst day for “systematic long-short managers” in more than two years. About half of the losses were because of momentum trades, the bank said.
Some traders have begun to short, or bet against, the very stocks that propelled the momentum trade earlier this year. Net short positions in futures tied to the Nasdaq-100 index among speculators recently climbed to some of the highest levels of the past two decades, according to data from the Commodity Futures Trading Commission.
The about-face is a sign of how markets have become more treacherous for investors, even as indexes keep climbing. Part of the issue: the recent meltdown of Situational Awareness, a hedge fund that had piled into some of the most popular momentum shares, including chip stocks. After a period of market tumult, Nvidia shares rocketed almost 9% after its earnings, showing how quickly sentiment can shift.
Some investors say the run-up in share prices driving tech stocks higher reminds them at times of the dot-com frenzy decades ago.
Mike Ogborne, the founder of San Francisco-based Ogborne Capital Management, said he has grown more cautious on technology stocks and is keeping more of his portfolio in cash than he typically does.
And he is nervous about the surge in spending by technology giants and quarterly capital expenditures that keep rising.
“It is a little bit like Cinderella and the clock striking midnight. You don’t know when midnight is going to come around,” Ogborne said. “They don’t send a memo around telling you when the capex cycle is over.”

A long-standing cultural cruise and a new expedition-style offering will soon operate side by side in French Polynesia.
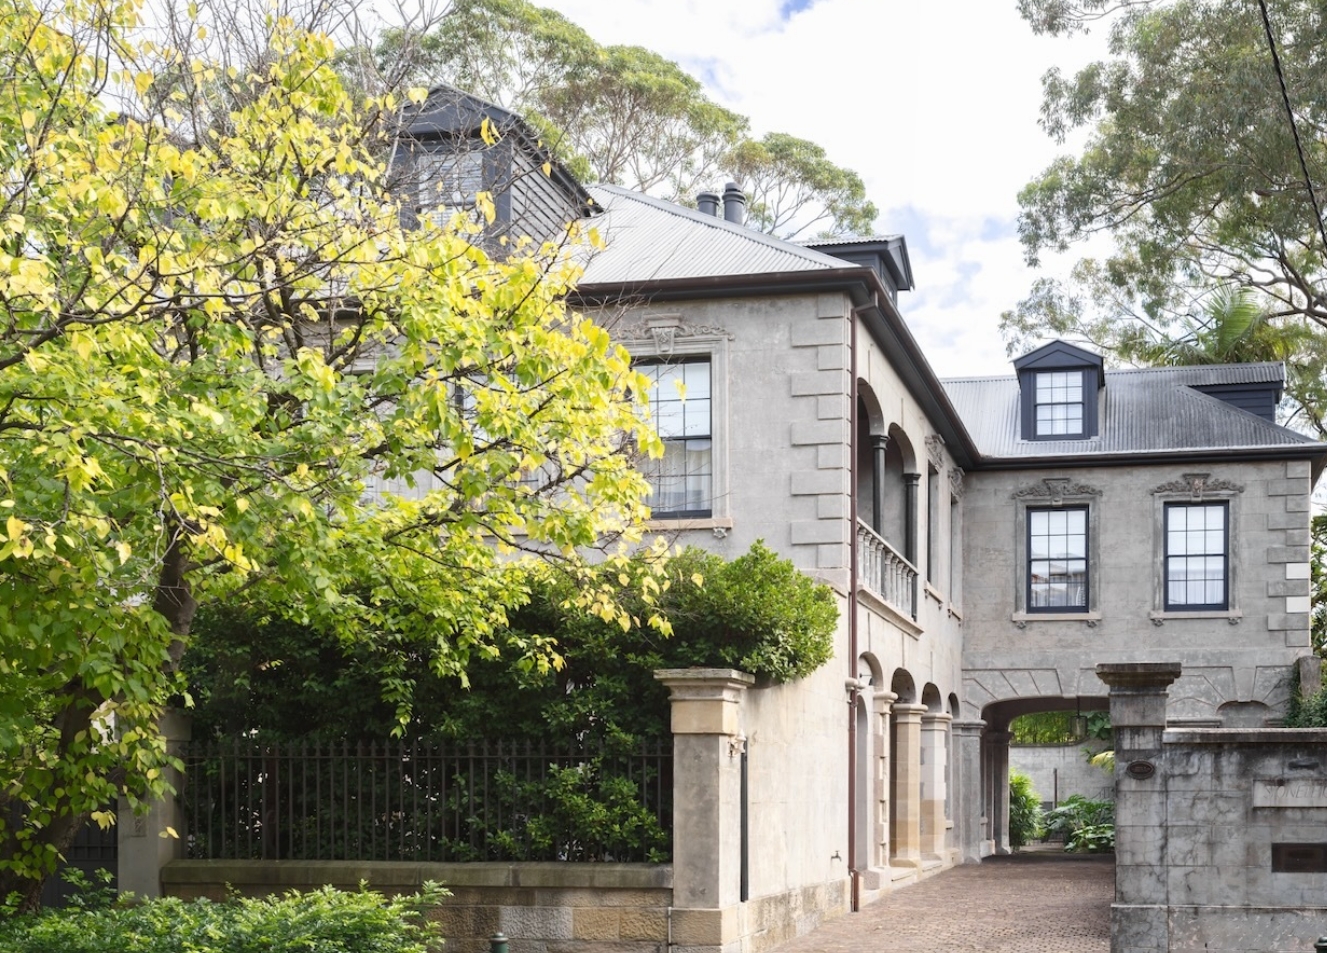
The 1860s Darlinghurst mansion Stoneleigh could become Sydney’s most expensive home ever sold under the hammer when it goes to auction. Clint Ballard is giving buyers a $28 million guide for the heritage-listed mansion on Darley Street, opposite Iona, the former home of Hollywood royalty Baz Luhrmann. Stoneleigh is being offered for sale for the …