Nike Reverses Course as Innovation Stalls and Rivals Gain Ground
Shoe giant stumbled as CEO John Donahoe pulled away from retailers and relied on old hits. Now it says it’s refocusing on cutting-edge footwear for athletes.

 10 min
In late February, Nike boss John Donahoe led a virtual all-hands meeting where he delivered a message to his staff: The company wasn’t performing at its best and he held himself accountable.
Two weeks earlier, Nike had announced it would lay off more than 1,600 employees .
Now, as the CEO spoke at the meeting, critical comments started to fill the chat window on the Zoom call while more than 20,000 employees watched.
“Accountability: I do not think that word means what you think it means,” an employee wrote. “If this is cost cutting, how about a CEO salary cut?” another wrote. Soon a cascade of laughing emojis filled the screen.
Some colleagues warned others that their posts weren’t anonymous and the chat might be monitored. The attacks went on for several minutes. “I hope Phil is watching and reading this,” an employee wrote, referencing the retired Nike co-founder Phil Knight .
The virtual protest illustrated the depths of the dissatisfaction within the sneaker giant and concern for its strategy. “How did we actually get here?” wrote one product manager.
Since the pandemic, Nike has lost ground in its critical running category while it focused on pumping out old hits and preparing for an e-commerce revolution that never came. The moves, current and former employees say, have eroded a culture of innovation and edginess that made Nike one of the world’s best-known brands.
Donahoe had told The Wall Street Journal in 2020 that his No. 1 priority when taking over the company was “don’t screw it up.” Four years later, the company is unwinding key elements of the CEO’s strategy that have backfired as a growing number of upstarts nip at its heels.
Among the reversals: As Covid raged and more shopping moved online, Nike cut ties with longtime retail partners such as DSW and Urban Outfitters and tried selling more merchandise directly to consumers. It is now asking some of those stores for help clearing out its overstuffed shelves and warehouses.
“I would say we got some things right and some things wrong,” Donahoe said Thursday, in an interview at Nike’s Beaverton, Ore., headquarters.
Losing its roots
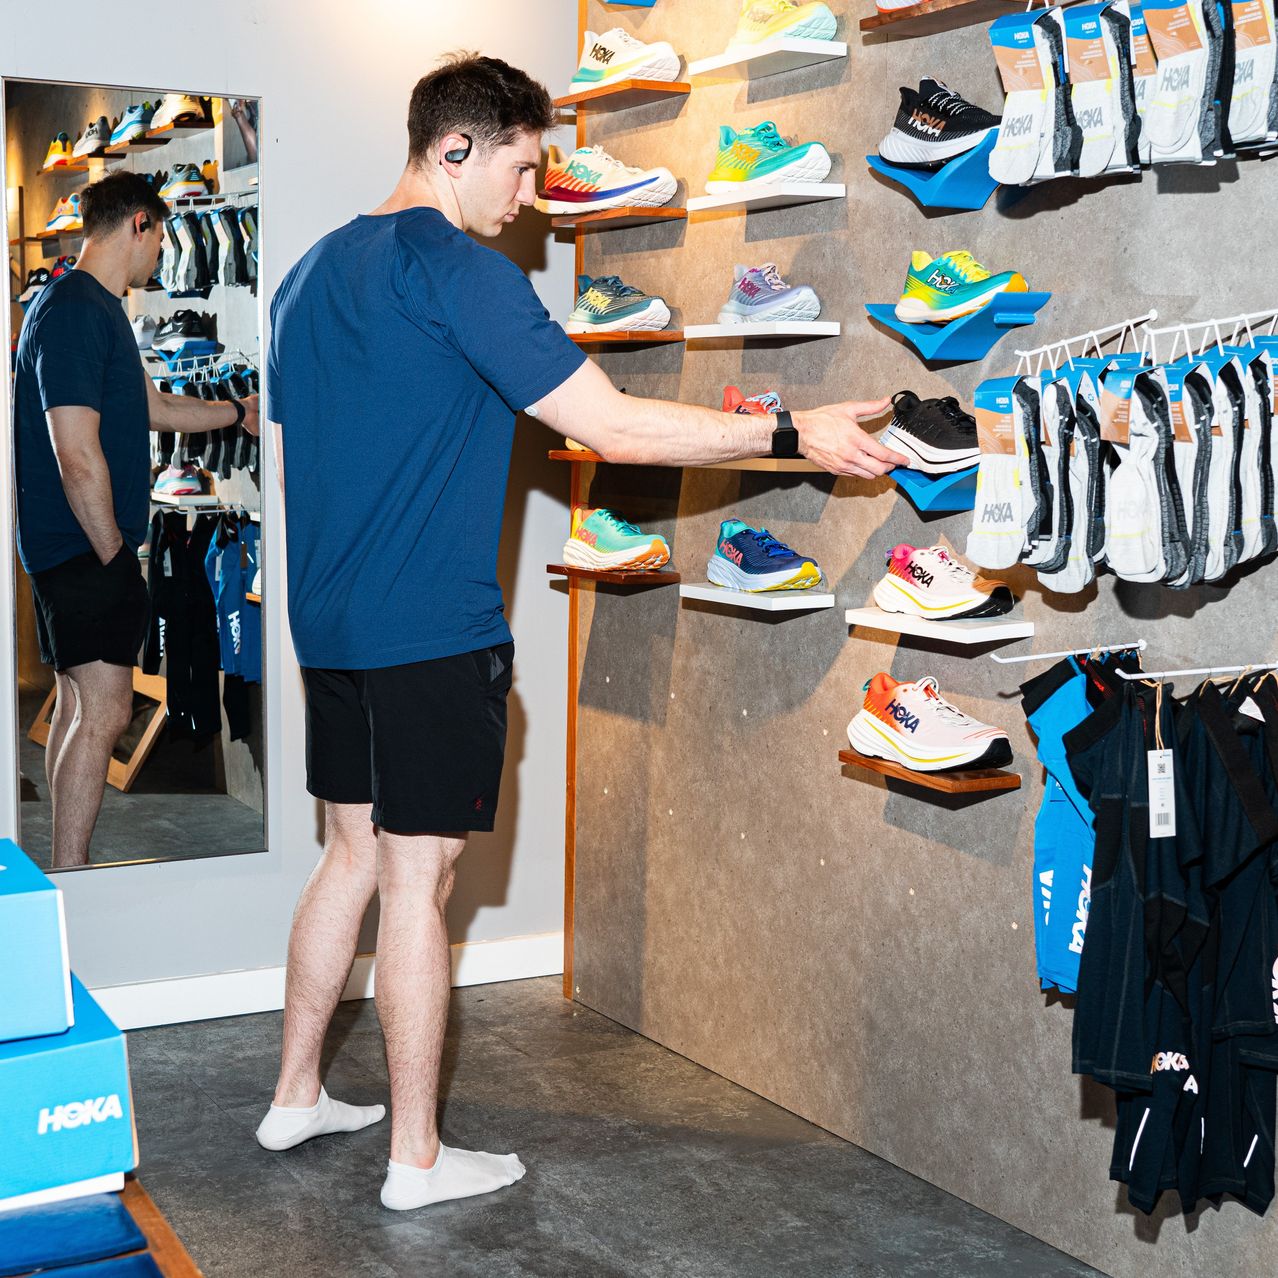
The strategic missteps have animated a debate inside the company about its identity. In its zeal to boost digital sales, some current and former employees say, Nike veered from its roots as a maker of cutting-edge footwear for serious athletes. It has opened itself to competition from newcomers such as On and Hoka, which have borrowed from the playbook that fuelled Nike’s rise—including focusing on sport over lifestyle, and taking risks on innovation.
Nike’s once torrid growth has stalled . Sales for the quarter ended Feb. 29 were flat compared with a year earlier, and shares in the company have declined 24% over the past year, compared with a 19% gain in the S&P 500.

Donahoe in the interview acknowledged the brand lost its “sharp edge” in sports and needed to boost its “disruptive innovation pipeline.” The CEO said the brand’s marketing got fragmented and that with people going back to bricks-and-mortar stores, it was clear Nike needed to invest in its retail partners.
Nike executives said in interviews that the company became too cautious after the pandemic and overly reliant on older products that were reliable sellers. They said the company has made significant changes in recent months to refocus it on putting out cutting-edge footwear.
“We were serving consumers what they know and love,” said John Hoke , Nike’s recently named chief innovation officer. “The job is to of course do that but also to show them something new, take them someplace new.”
Donahoe said Nike is going through a period of adversity and layoffs that has created uncertainty, but that the company will get through it. “Our employees have been through a lot,” he said. “Nike is actually at its best, like a great sports team, when our backs are against the wall.”
Knight, who is chairman emeritus of the board and the company’s largest shareholder, said in a statement that Donahoe has his “unwavering support.”
Donahoe said employees’ responses to the all-hands meeting reflected one of Nike’s biggest strengths: how much its staff cares about the company. “We welcome and encourage that,” Donahoe said.
Shift into digital
Donahoe took over Nike just before the pandemic, at a delicate time. Though he inherited a market leader and one of the world’s best-known brands, Nike was seeking a refresh after it dealt with complaints about its workplace culture that led to a management shake-up .
The Evanston, Ill., native had been CEO of eBay , where he doubled the e-commerce platform’s revenue during a seven-year stint that ended in 2015. After a sabbatical—during which he says he had a life-altering experience at a 10-day Buddhist silent meditation retreat—Donahoe went on to run cloud-computing company ServiceNow .
When he took the helm of Nike in early 2020, his marching orders from Mark Parker , his predecessor and current executive chairman, and Knight were clear. He was to turn the world’s biggest shoe maker into a tech company more directly connected to consumers through its own apps, which in turn collect valuable data from shoppers.
Parker said when he stepped down that Donahoe was the right candidate to lead Nike’s digital transformation.
Donahoe was just the fourth CEO in the company’s more than 50-year history. The only other outsider to get the job said he was ousted in 2006 after a short stint because he focused too much on the numbers .
Donahoe started out with a 100-day global listening tour that was cut short after a month when the pandemic hit.
Covid lockdowns fuelled a surge in online shopping. Digital channels accounted for 30% of Nike’s sales in May 2020, about three years ahead of schedule.
Donahoe saw it as an acceleration of an inevitable shift and adjusted Nike’s plans accordingly. A few months in, he redoubled the company’s bet that it could make more money by selling products directly to consumers through its stores and digital channels. He said he believed digital sales would reach 50% of the business, and Nike should transform faster to define the marketplace of the future. It was time to act.
By late 2020, Nike dropped about a third of its sales partners and sold less merchandise to clients such as Foot Locker , DSW and Macy’s . There had been a plan to phase out wholesale clients since 2017, but with digital sales growing quickly, Donahoe said there was a need for urgency.
Executives were divided over whether Nike’s own stores, which include both factory outlets and specialty shops selling higher-priced new releases, could fill the sales void left by the retailers the company was cutting out.
In meetings, finance chief Matt Friend and Nike president Heidi O’Neill supported the aggressive exit from retail that Donahoe was pushing, while others favored a slower transition, people familiar with the matter said.
Some executives felt the specialty stores in particular worked better as marketing tools and that cutting off so many retailers so fast would backfire, the people said. Donahoe and his allies prevailed.
Nike teams were tasked to come up with a new global supply-chain process. Selling directly to consumers increased the company’s liabilities, including by shifting storage and shipping costs from wholesalers to Nike. The company would also absorb the losses from discounts if the merchandise didn’t sell quickly and inventory piled up.
One of the casualties of Donahoe’s 2020 transformation was a multibillion-dollar operation dedicated to developing footwear sold for under $100. The company deprioritised more-affordable footwear that usually sold to the sales partners that Nike was leaving behind. The move left Nike skewed toward higher-priced shoes.
The first evidence of cracks in Nike’s new approach appeared early last year when Foot Locker Chief Executive Mary Dillon said during an earnings call the brand had reversed course and was sending the retailer a wider assortment of Nike products. By the summer, Macy’s and DSW were saying the same thing.
The message was clear: Nike needed help selling merchandise.

Nike veterans said cutting off wholesale clients was one of the biggest mistakes the company has ever made. After digital sales hit the 30% of the total mark early in the pandemic, they dropped back, and haven’t reached that level since—let alone the 50% target Donahoe had foreseen.
Donahoe said in the interview the goal at the time was to lean more on specific partners, such as Dick’s Sporting Goods and JD Sports , which he considers to be more aligned with Nike, rather than make a dramatic shift in strategy. Nike deprioritised making lower-priced shoes because of supply-chain disruptions during the pandemic, but it is now making more of those products, he said.
“I don’t see it as a reversal of the strategy,” Donahoe said of the return to more retail chains. “I see it as an adjustment.”
Rising competition
Competitors have been using the sneaker giant’s playbook at its expense. Smaller brands like On, Hoka and New Balance have captured significant pieces of the market for both hard-core and everyday runners—and their popularity is spreading to the mainstream.
Often quoting Knight, the Nike co-founder, former employees said the principle always was to first capture the market for hard-core athletes with innovative performance gear, and the casual consumer would follow.
In early February, Hoka owner Deckers Outdoor tapped Nike alums to take over both the parent company and the shoe brand. Hoka had $1.4 billion in sales for the year through March 2023, compared with about $352 million three years earlier.
Hoka didn’t respond to requests for comment.
“When you’re the biggest, there’s always going to be people coming after you,” Donahoe said. Competitors give Nike an incentive to try to understand what consumers want and to figure out how to come up with something bold and different, he said.
Nike still dwarfs its competition . During Donahoe’s tenure, Nike sales have grown 31% to $51 billion in 2023. That is more than double the results of Adidas, its closest competitor by far. New Balance reported sales reached $6.5 billion last year, and upstart On almost hit the $2 billion mark.
The race to hit revenue targets came at a cost for Nike. Executives turned to the brand’s lucrative franchises, including Air Jordan and Dunk, and ramped up the releases. The strategy diluted the exclusivity prized by die-hard Nike sneaker shoppers.
Donahoe said in the interview that Nike ramped up production to meet demand on its SNKRS app, which fans use to buy the latest limited releases. In early 2021, Nike was meeting less than 5% of the demand for some releases on the app and consumers were frustrated, Donahoe said, adding the goal is to meet something closer to 20% of demand for the exclusive styles.
Now, sneaker resellers say they have seen release after release of Nike’s limited-edition kicks that don’t sell out on the SNKRS app, and that in the secondary market—a space that the brand closely monitors —prices are tanking.
Nike executives in March said they would pull back on franchise releases.
Donahoe said “franchise management has always been something Nike has done.”
Nike’s digital sales, a figure that includes direct and partner e-commerce sales, declined for the quarter ended Feb. 29. Friend, the finance chief, told analysts in March that Nike expects total sales to decline at least until the end of this year.
Struggle for innovation
The pursuit of sales growth from limited-edition sneaker releases led Nike to neglect its running category, long considered the core product of the company, former employees said.
This month in Paris, Nike unveiled its new product line for the Olympics, including running shoes with a new cushioning system that uses the company’s Air technology.
In interviews at the event, executives said the company had become somewhat risk-averse during the pandemic, when working remotely stifled creativity. Martin Lotti, chief design officer, said the company had spent too much time looking to its past.

“If you drive a car just by looking in the rear view mirror, that’s not a good thing,” Lotti said. “The bigger opportunity is the windshield.”
Current and former Nike executives believe the future of the company is in its app ecosystem , like the Nike Training and Running Club or its SNKRS app, and the data it can harness from them to help design and sell products. Inside the company, leaders have long tried to draw comparisons to Apple when talking about Nike’s innovation and design culture.
The sneaker giant has been acquiring smaller data analytics startups for at least a decade. Two years ago, it also bet on the NFT craze .
One of Nike’s biggest tech investments is a multibillion-dollar process to migrate multiple software programs into one single system. The new platform, known as S/4HANA, is still not operational and is three years behind schedule. The software is designed to help day-to-day operations, such as procurement and inventory management, and speed up digital sales.
As part of its accelerated focus on digital sales, Nike hired about 3,500 people to join what the company calls its global technology group, which includes consumer insights and data analytics. Executives at the time said they were investing in “demand sensing,” “insight gathering” and a new inventory system.
Former Nike employees with knowledge of the consumer insights strategy said executives misinterpreted the data in ways that overestimated demand for retro franchises.
During February’s round of layoffs executives trimmed layers of management across the company’s insights and analytics teams. A large technology innovation team, tasked with developing software to implement Apple’s new Vision Pro augmented reality system in day-to-day design tasks, and a separate artificial intelligence team were also eliminated.
Executives at Nike say it is entering a “supercycle” of innovation and that the new Air line of products enhances athlete performance.
At the Olympics preview event this month, the company took over the historic Palais Brongniart in central Paris with a three-day event to unveil its new Air line. Guests wandered through a museum-like, conveyor-belt installation highlighting Nike’s product evolutions and research and development programs. Athletes including runners Sha’Carri Richardson and Eliud Kipchoge modeled the new gear. Retired tennis great Serena Williams narrated the company’s lavish introduction video before appearing on stage.
Outside, 30-foot orange statues of Nike-sponsored athletes including LeBron James, Kylian Mbappé and Victor Wembanyama stood guard.
Donahoe’s relationship with Knight goes back to the early 1990s, when he was a Bain consultant on Nike projects. He joined the Nike board in 2014 and is one of the directors of an entity Knight created called Swoosh LLC, which holds roughly $22 billion worth of Nike shares and controls a majority of Nike’s board seats. Donahoe calls Knight his “greatest hero in business.”
The current CEO said he meets with his predecessor, Parker, every week.
Donahoe said that he and Parker share an approach to management he calls “servant leadership” that was embodied by some of his sports heroes, including basketball coaches Phil Jackson, John Thompson, Mike Krzyzewski and Tara VanDerveer.
“It’s never been about me. It’s about your players. And are you doing everything you can to allow your players to make the adjustments to win? And when you have a win it’s about the players and when you have a loss you say it’s on me, right?,” he said. “And that’s what I’ve always tried to embody, including during this period of time.”
This week, Donahoe is facing another test: the company is notifying several hundred more workers whose jobs are being cut.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


On the owner’s deck, a 20-metre swimming pool incorporates Feadship’s patented ContraWave technology and extends indoors as a suspended, glass-bottomed infinity pool.
Automobili Lamborghini is turning its attention to something considerably more difficult to define: what makes Italian excellence uniquely Italian?


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 min
A sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
From bushland greens to valley reds, the country’s most awarded designers are proving that the best colour palette was never on a swatch card; it was outside the window all along.

Wealthy Aussies are swapping large family homes for high-end apartments, with sales of prestige units tripling over the past decade.