Step Aside, Banks. Tesla and Netflix Earnings Are the Real Tests

 2 min
Forget banks—third-quarter earnings season doesn’t start until Wednesday, when Netflix and Tesla report.
Since Alcoa’s (ticker: AA) abdication, the kickoff of earnings season has been assigned to the U.S.’s big banks, including JPMorgan Chase (JPM) and Citigroup (C), which reported earnings on Friday. This despite the fact that some large, prominent companies, including PepsiCo (PEP) and Delta Air Lines (DAL), disclosed their results earlier in the week.
Don’t expect the overall market to care too much about how the banks do. The S&P 500 financials sector, which includes banks and insurers but also Visa (V) and Mastercard (MA), totals 12.7% of the index’s market value. Its earnings contribution is expected to be larger, at 17.4% of third-quarter earnings, according to data from Refinitiv. But these days, the banks are less a reflection of the U.S. economy than they are of monetary and regulatory policy, which take up a good portion of their earnings calls.
No, earnings season doesn’t really get started until Wednesday, when the first of the large technology-oriented stocks that have driven the S&P 500 this year are set to report. That would be Tesla (TSLA) and Netflix (NFLX), followed by Alphabet (GOOGL), Microsoft (MSFT), Meta Platforms (META), Amazon.com (AMZN) next week, and then Apple (AAPL) on Nov. 2. Nvidia’s (NVDA) fiscal third quarter doesn’t end until Oct. 31, and it will report in late November.
The Magnificent Eight punch well above their fundamental weight, thanks to premium valuation multiples. The group makes up roughly 30% of the S&P 500’s market capitalisation but is expected to contribute just 10% of the index’s third-quarter sales and 16% of earnings, according to Refinitiv. Hits and misses from their results will prompt outsize moves in the index.
Take Meta, which Wall Street analysts expect to report $8.0 billion in earnings for the third quarter, up 120% from the same period last year. That’s nearly a full percentage-point contribution to the S&P 500’s overall expected earnings growth in the quarter.
Nvidia is responsible for another 1.5 percentage point of expected growth, Amazon for 0.6 point, and Alphabet and Microsoft for 0.5 point each. With growth rates like those, how well the biggest companies on the market do could meaningfully swing overall S&P 500’s earnings growth one way or another.
There’s a slim margin for error: Analysts are predicting 1.3% year-over-year earnings growth from the S&P 500 in the third quarter, per Refinitiv. The biggest expected individual detractors from the index’s year-over-year earnings growth are Exxon Mobil (XOM)—a 1.9-percentage-point drag—and Pfizer (PFE), a 1.5-point drag.
That’s before considering the potential impact to investor sentiment from Big Tech’s results. In a year dominated by macro themes, the enthusiasm around artificial intelligence has been one of the greatest bullish drivers of the stock market. Nvidia’s results are showing the benefit already, while other companies are more likely to be merely talking up the technology’s transformative potential.
Hype can only go so far—eventually even Microsoft, Meta, and Alphabet will need to show that their AI investments are yielding a positive return. The third quarter of 2023 is still early innings in the AI revolution, but signs of progress will be cheered by investors, and may be necessary to justify many of the Magnificent Eight’s huge rallies this year.
Third-quarter earnings season may have officially kicked off, but the real action has yet to begin.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


The Swiss watchmaker’s first collaboration with Atlassian Williams F1 Team produces two sporting Laureato models inspired by the team’s 2026 racing car.
Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”
From early financial mistakes to hard-earned habits, five high-performing leaders share how they spend, invest and think about wealth.
9 min
Five minutes doesn’t sound like much. But it’s enough time to tell whether someone really understands money or just talks about it. Because once the gloss is stripped away, what’s left is instinct. The early mistakes. The bad calls. The quiet pivots that no one brags about but shape everything that follows. Making money is one thing. Living with it, and not mishandling it, is another. Here, five executives talk about what they got wrong, what they’ve learned, and how they now actually spend, invest and think about wealth.
Andrew Raso: Founder, Online Marketing Gurus
Self-made millionaire Andrew Raso grew up in an ethnic household with a father in construction. Investing was not a priority, he recalls.
The co-founder and CEO of Online Marketing Gurus, a digital marketing platform that generated more than $30 million in revenue in the 204/25 financial year, admits he’s had to learn about handling money as his wealth has grown.
“If I had my time again, I would change my spending habits and would probably be a lot more wealthy as a result,” the Sydneysider tells Kanebridge Quarterly.
Raso, in his mid-30s, says that his biggest lessons have come from his losses.
Buying the wrong property and copping the losses upon sale. Feeling FOMO when buying crypto and making a purchase that lost money.
“I’ve learned a lot from the errors that I’ve made,” he says.
Raso admits that he gets more of a thrill out of working than watching money hit his bank account.
“I’ve had the cars, I’ve had the property, I’ve had the watches. Once you’ve had them, they’re not that exciting, but the process of earning money is pretty cool.”
What he won’t forget is being $45 million in property debt a few years ago.
“I’d never want to be in that position again,” he says.
“My investing strategy is a lot safer these days. I’m very cautious. I’d prefer to invest in things that don’t take as long to be realised so my family can be financially secure.
“Once you have a house paid off and a few investments, it then becomes about enjoying your money, rather than hoarding it. Giving back gives me a much bigger kick than spending these days.”
Daniel Wessels: CEO, Jacaranda Finance
Fintech founder Daniel Wessels knows only too well that money remains a taboo topic in Australia with many people.
He points to consumer surveys that reveal people are more likely to talk about their sex life with friends than their finances.
It’s a major concern for the man who founded Jacaranda Finance in 2013, which has helped countless people lift their credit scores and get their finances back on track.
“If people aren’t learning money habits at school and they aren’t discussing it with their friends, learning new strategies and better habits is difficult,” says Wessels, who is based in Brisbane.
He wants to see more people take the time to proactively understand where and why they are spending money.
“Everyone needs to have a financial strategy and a plan to measure if it’s working,” he says.
The father of two young children admits his week can be pretty fast-paced. Pomodoro clocks, sleep optimisation techniques and saying ‘no’ keep him on task during the week.
“I used to think I was fairly decent at managing time, but the whole game changed when we had kids,” he says.
“Now, I’ve got to get out of the house at a certain time and leave the office at a certain time for daycare pickup. I’ve got to be really specific about my tasks to maximise my week.”
Before he had a family, he loved heading out to one of the trendy new restaurants popping up in Brisbane.
But that happens less these days. He’s saving to build his forever home but admits that price rises have resulted in rising costs.
“It’s such a big project with so many variables that change quickly,” he says.
These days, Wessels likes to optimise his professional and personal life. “With only a finite amount of money, time and energy, you’ve got to be really good at deciding what you want to be good at,” he says.
He calls this ruthless prioritisation. He has a very specific focus on activities that prioritise health and wealth, adding experiences into the mix more recently. This has meant the addition of micro-holidays to his annual calendar.
Wessels works with a couple of financial advisers. That said, he also does his own due diligence before agreeing to investments.
“One likes private equity investments that pay cash every month and another prefers to focus on the NASDAQ Stock Exchange for buying shares because he’s bullish about that.” he says. “They’re each experts and really good at what they do.”
Jim Penman: CEO, Jim’s Group
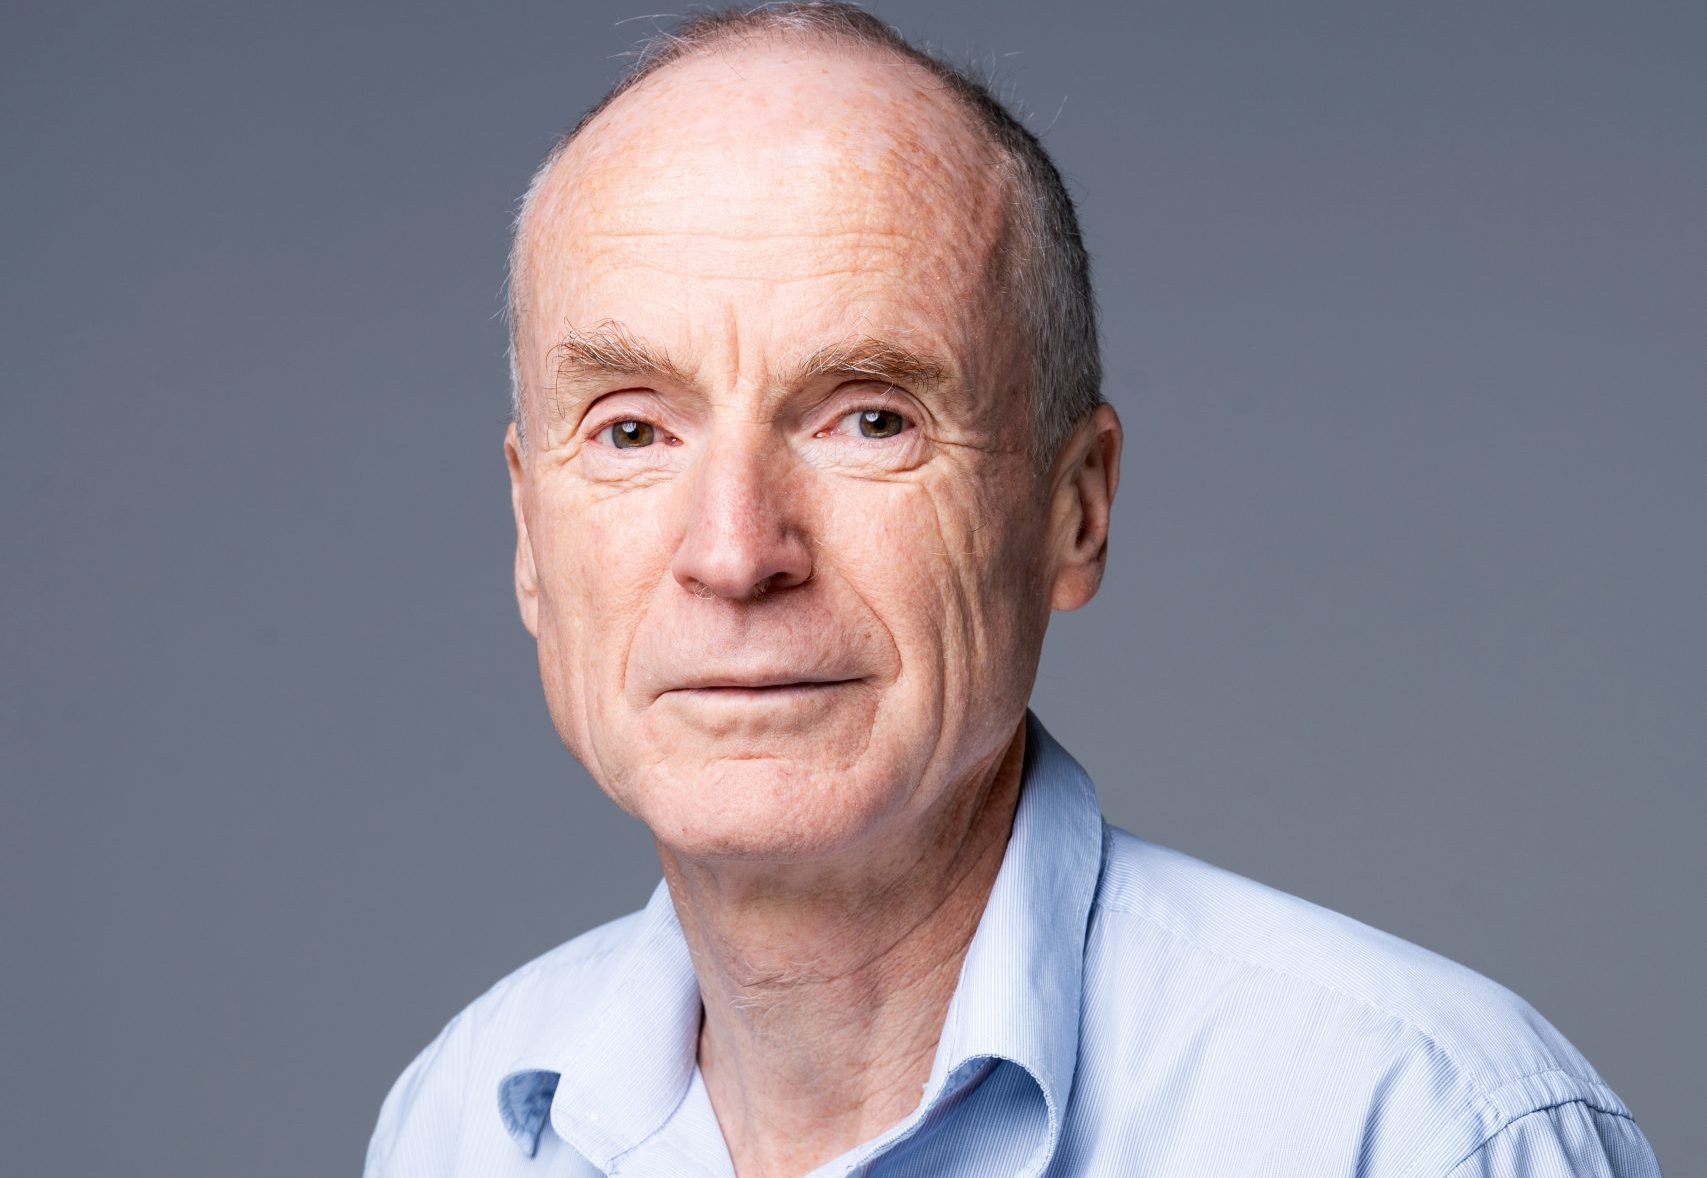
He may have invested a lifetime building a franchise juggernaut that is reportedly a $1 billion a year empire, but Jim Penman insists he’s a frugal guy who prefers to spend time planting a tree in his garden than contemplating his wealth.
What started out as Jim’s Mowing back in 1989 became Jim’s Group. Today, there are 5,700 franchisees across Australia and New Zealand in the business that has become ubiquitous for being the local handyman company that households could rely on.
He may have built a successful business empire, but the Melburnian insists he’s stingy when it comes to money.
“I wear my clothes even today until they wear out. I’ve always had a very lean and mean attitude. I live a simple life. My personal needs are very modest and my finances are simple,” he says. Jim reveals he’s usually in his garden these days and rarely eats out or takes holidays.
He is also running for state politics in the November Victorian election.
“I’m not particularly money focused. I could tweak the franchise contract to put more fees in and double my profitability, but that’s not my goal or my aim. To be honest, I often make decisions that go against my financial self-interest,” he says.
Jim purchased his first brand new car three years ago, opting for an electric Volvo.
“Being rich is not my aim and it never has been. People think I’m a lot richer than I am. They think I’m a billionaire, which is kind of ridiculous,” he says.
In fact, he insists he carries debt, which is common for anyone in business. “If I wanted, I could pay it off in 18 months.”
While his competitors were spending on fancy office space, Penman was running his franchise from his basement, keeping business costs low. “When I started out, I didn’t have any concept of how big this business could be. But there has never been a plan to grow franchisee numbers.
“Our attrition rate is far more important, and how to reduce complaint rates and drive more enquiries through new software.”
He believes people these days worry too much about impressing others, which leads to spending on superficial things.
“I would rather than offer people advice on how to be happy, rather than how to become rich. It’s important to have a good income so you can support yourself. But life is more about purpose.”
Jim doesn’t bother with stocks or bonds. He only invests in his own business. “My rate of return on my business is substantial. I could buy back a regional franchise when they come on the market and get a 20-25 per cent annual rate of return, plus capital gains. There’s nothing like that available in the investment space.”
Nicola Beswick: Founder, White Rabbit Advisory
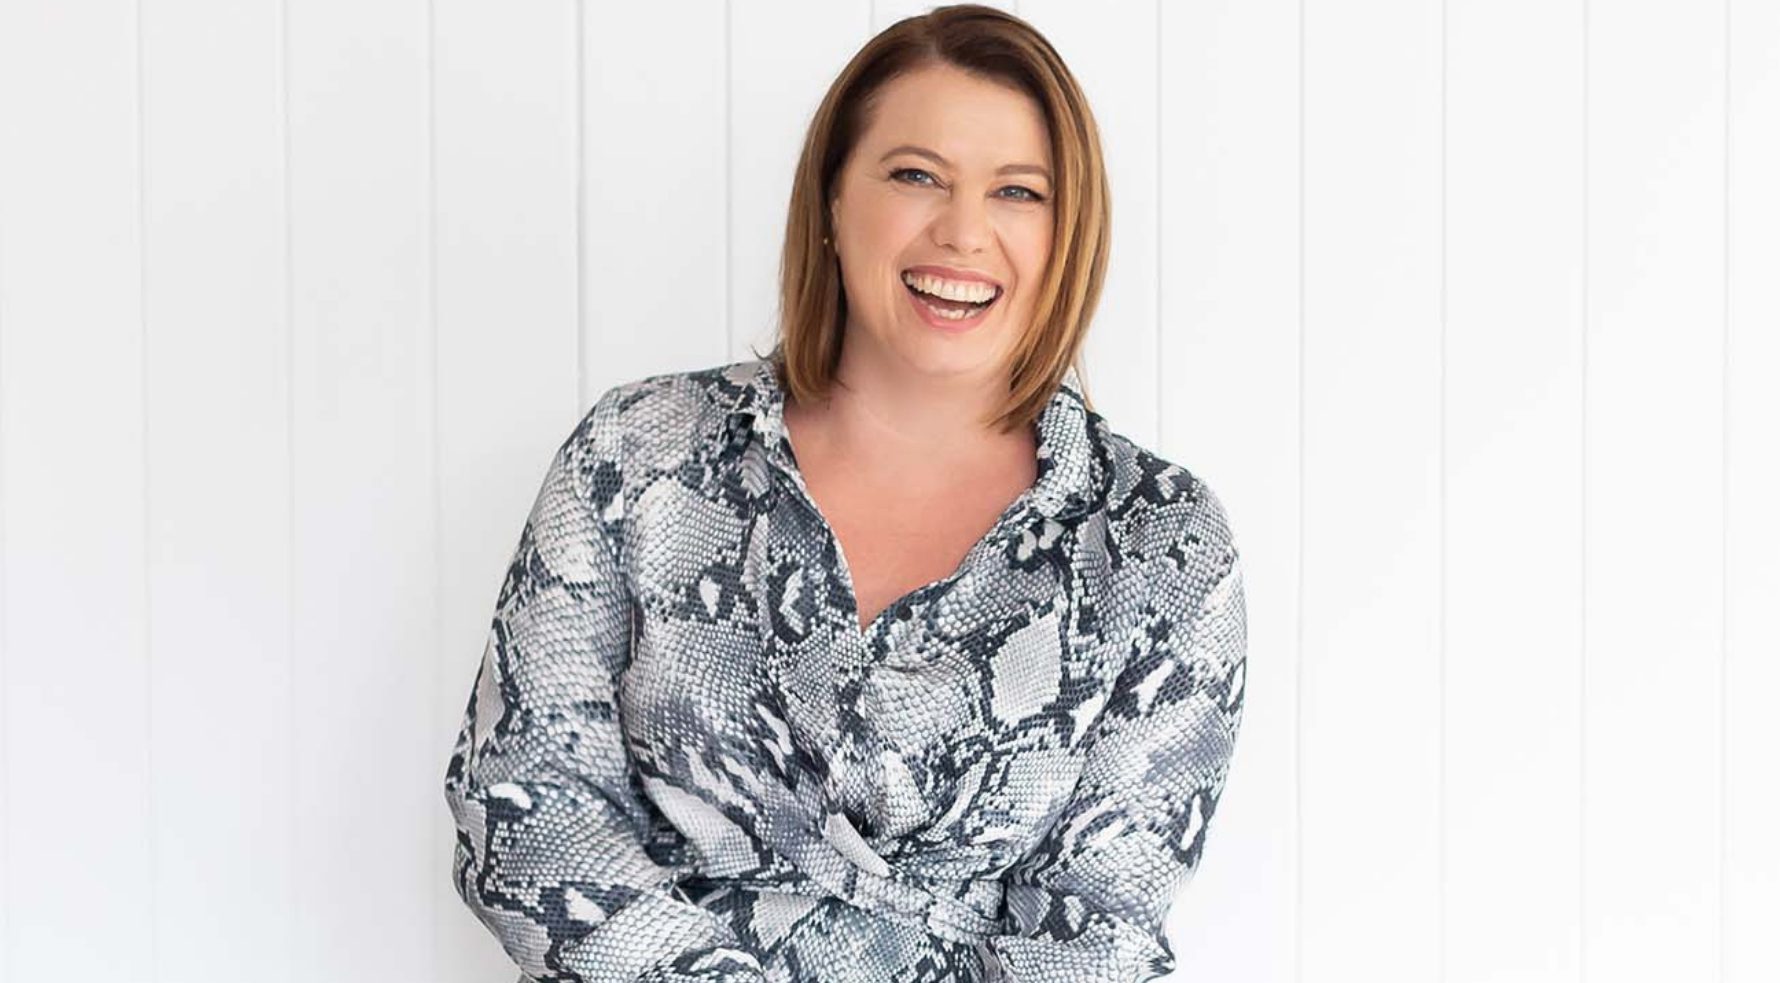
Rabbit Advisory founder.
A clothing allowance provided by her parents and then a part-time job during high school was the first taste of financial freedom for Nicola Beswick.
She quickly became a spender rather than saver, but she’s changed her tune over the years.
The founder of financial advice firm White Rabbit Advisory left behind a successful career in intellectual property law a year ago to become a financial adviser because she realised the potential that financial education could have on someone’s life.
Her journey began after coming across the book Rich Dad Poor Dad some years ago, which opened her eyes to the power that money could have on her life. This marked a time when she became serious about her finances.
“Financial education and investing over time can have a huge impact on a person, and that book got me thinking about money and financial education in the first place,” she says.
Nicola says years ago, her father was diagnosed with multiple sclerosis. When dealing with the devastating news and an uncertain future, her father discovered he was eligible to receive an income protection payout.
“This was the stone that rippled his pond and mine. A new complex world of finance opened up and I discovered my calling – helping people plan for a financially secure future.”
She hasn’t looked back. “Commercial law was very transactional. I don’t regret quitting at all. I’m much happier now helping people get their finances in order. Financial planning helps people change their lives. That was a really big driver for me.”
The Melburnian admits she’s learned plenty of lessons along the way as she embarks on the process of building wealth. She uses superannuation as an investment vehicle, favouring its tax advantages.
“I also built a nest egg outside of super, because you never know when the rules will change,” she says.
She prefers to set a financial goal and save up for something specific over time than rush out and make a purchase.
“It’s a really powerful thing to wait before making a purchase,” she says.
Her current financial goals involve renovating her heritage-listed home. “We will keep the façade and gut it to rebuild. That’s a major expense for us on the horizon.”
While holidays are rare, she will spend on overseas trips on occasion. “I’m terrible at taking time off. I’m always working.”
Sam Riley: CEO, Drova
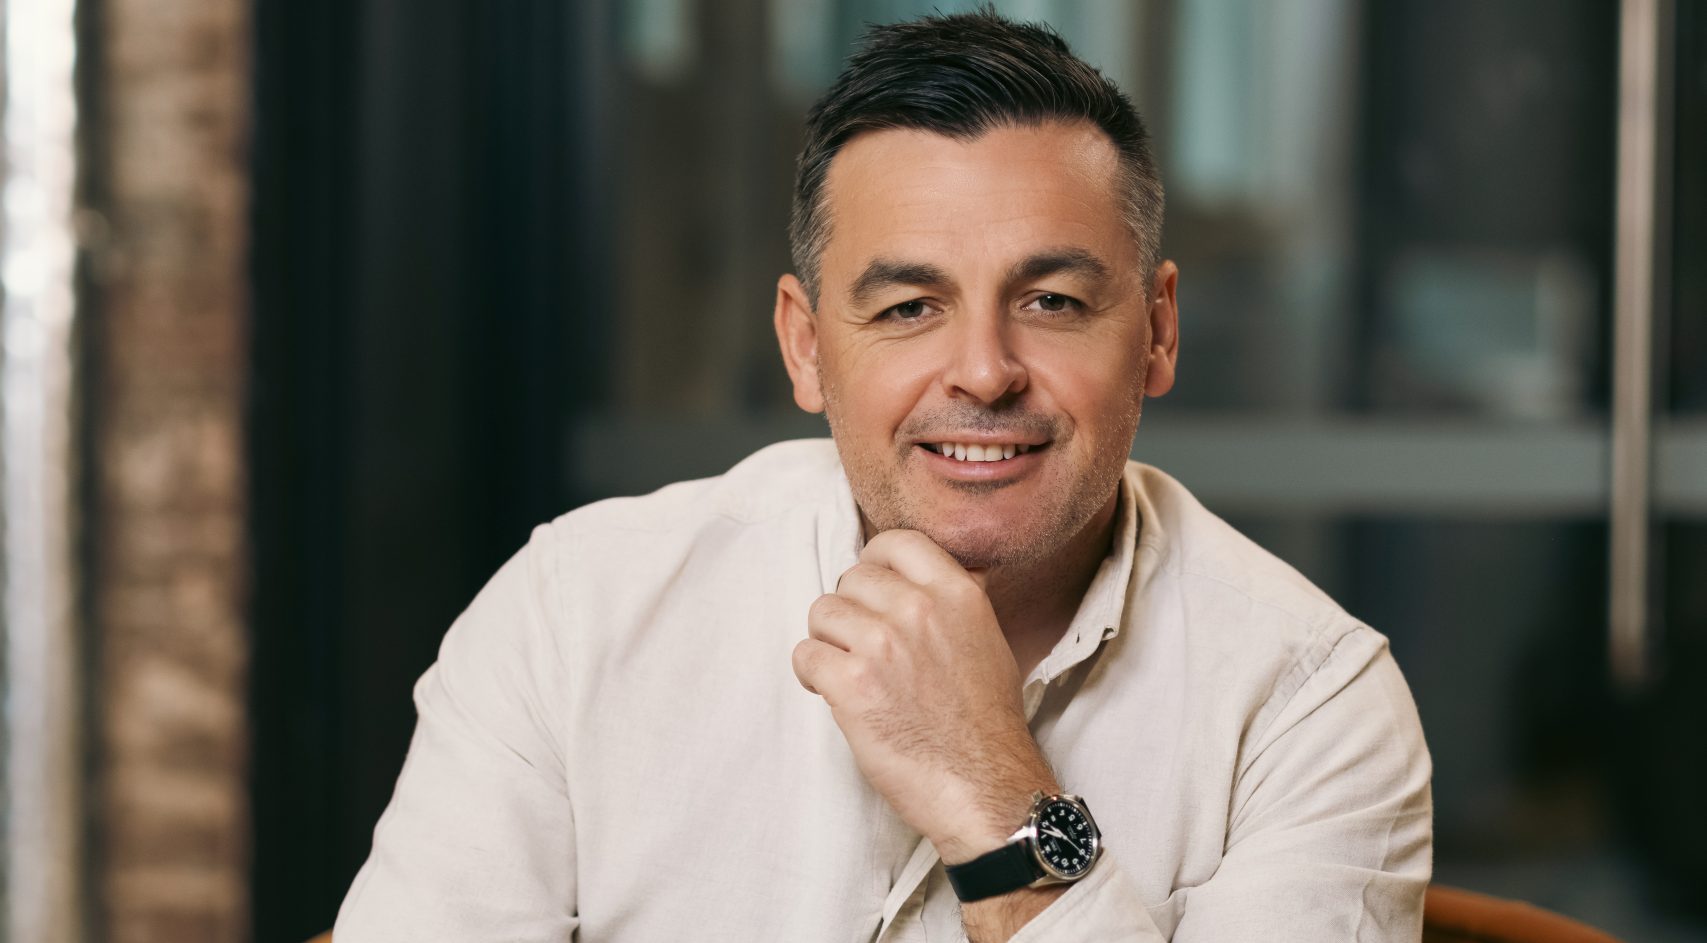
Sam Riley was in his 20s when he set out to amass enough money to be able to retire by the age of 40 if he wanted to.
“The goal was always to be doing something by 40 that kept me engaged enough that I didn’t actually want to retire because I was happy,” he says.
An entrepreneur at heart, Sam started a juice and espresso bar when he was 21, which didn’t work out. His next venture was a technology business, Ansarada, an ASX-listed company he ultimately sold nearly two years ago for $250 million.
The sale set him up for life, but he’s not one to rest on his laurels, launching into the complex world of artificial ntelligence with his next technology play, a company called Drova.
The technology startup simplifies risk, compliance and resilience for small businesses. Sam believes it’s got potential to become a tech juggernaut in time.
Having early financial success has meant he has the luxury of slow mornings and working in short bursts throughout the day, problem solving, experimenting with what works and figuring out how to harness AI.
“I favour a more sustainable approach to working these days. More frequent breaks. Making sure not to deteriorate my capacity,” he says.
It was a hard slog. He admits he touched the fringes of serious burnout when he was younger, which he works hard to avoid these days.
“Every business venture has exposed a gap in my skills that I’ve worked to close. Whether that’s marketing or managing people, closing those gaps along the way is how you get more effective at generating wealth,” he says.
The secret to his success has been finding ways to bolster value in the corporate world, finding ways to bring more to the table. Sam admits he spends too much money on travel, food and niche vinyl audio equipment, like turntables. He prefers to invest in experiences rather than things.
But it can get expensive. Like a recent trip to Antarctica to stay in a lodge for a week. “The thing is I didn’t like having these experiences on my own, so I have to bring family or other people and then pay for them.”
Sam describes his investment portfolio as balanced. While he continues to invest in entrepreneurial ventures, he admits he has a safe foundational platform to his investment approach.
“Over the years, I’ve added a lot more dividend stocks and protective assets like gold and silver, and some index funds.
“When I was younger, I didn’t appreciate the value of being safe and boring in the investment world.”
He says a lot of his investments used to be leading edge and visionary. “Some of them work, and some of them don’t. I didn’t really have much balance in my portfolio. I still invest in entrepreneurial things, but am much more conscious of taking a more even-handed approach,” he says.
This article appeared in the Winter 26 issue of Kanebridge Quarterly, which you can buy here.

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.
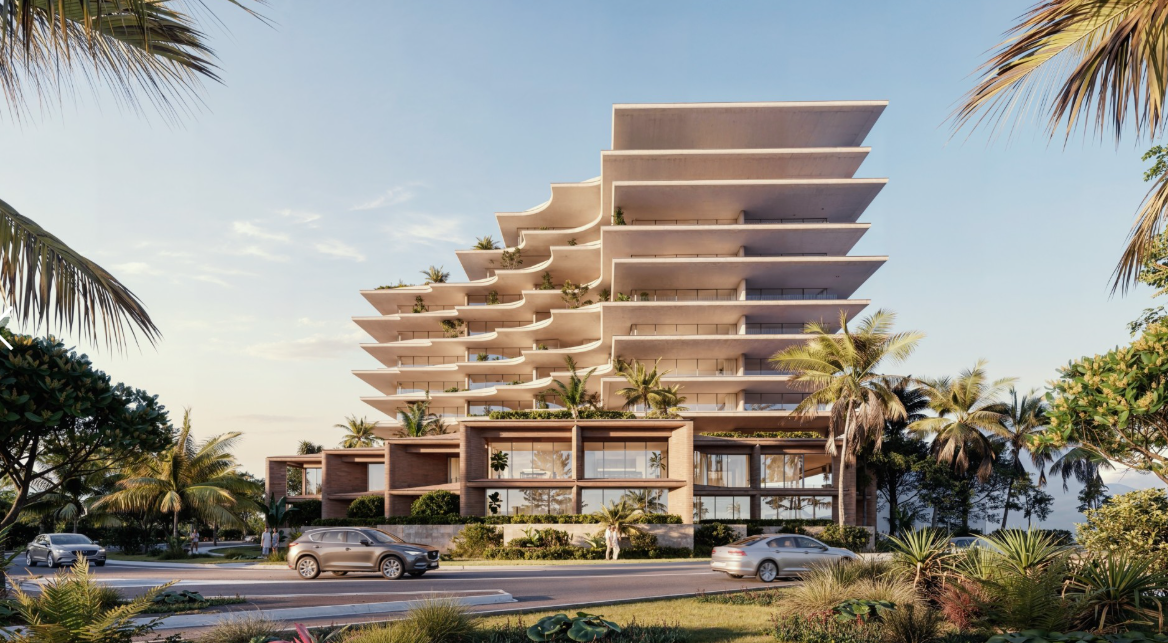
Queensland-based builder-developer MAYD has unveiled an exclusive first look at its anticipated ultra-luxury North Kirra mixed-use project as it lodges a minor amendment with the City of Gold Coast Council. The project sits across a 4,742sqm amalgamated landholding spanning seven parcels at 2–6 Pacific Parade and 27–33 Golden Four Drive, Bilinga, which MAYD secured in …
Continue reading “MAYD”s North Kirra Plans Unveiled Ahead of Early 2027 Launch”