Tariffs Are on the Table for U.S. Importers, Whatever the Election Outcome
U.S. companies are pulling away from China as Democrats and Republicans increasingly impose duties on Beijing

 4 min
Until a few years ago, Chinese factories supplied the world with Sharpie retractable pens and Oster blenders.
No more.
Consumer giant Newell Brands now makes those products, and more, at its own plants in the U.S. and Mexico. Many of its other products are made in factories in Vietnam, Indonesia and Thailand.
Chris Peterson , Newell’s chief executive, said the company’s shift reduces its dependence on China at a time when both the Democratic and Republican parties “are getting more protectionist in terms of trade policy.”
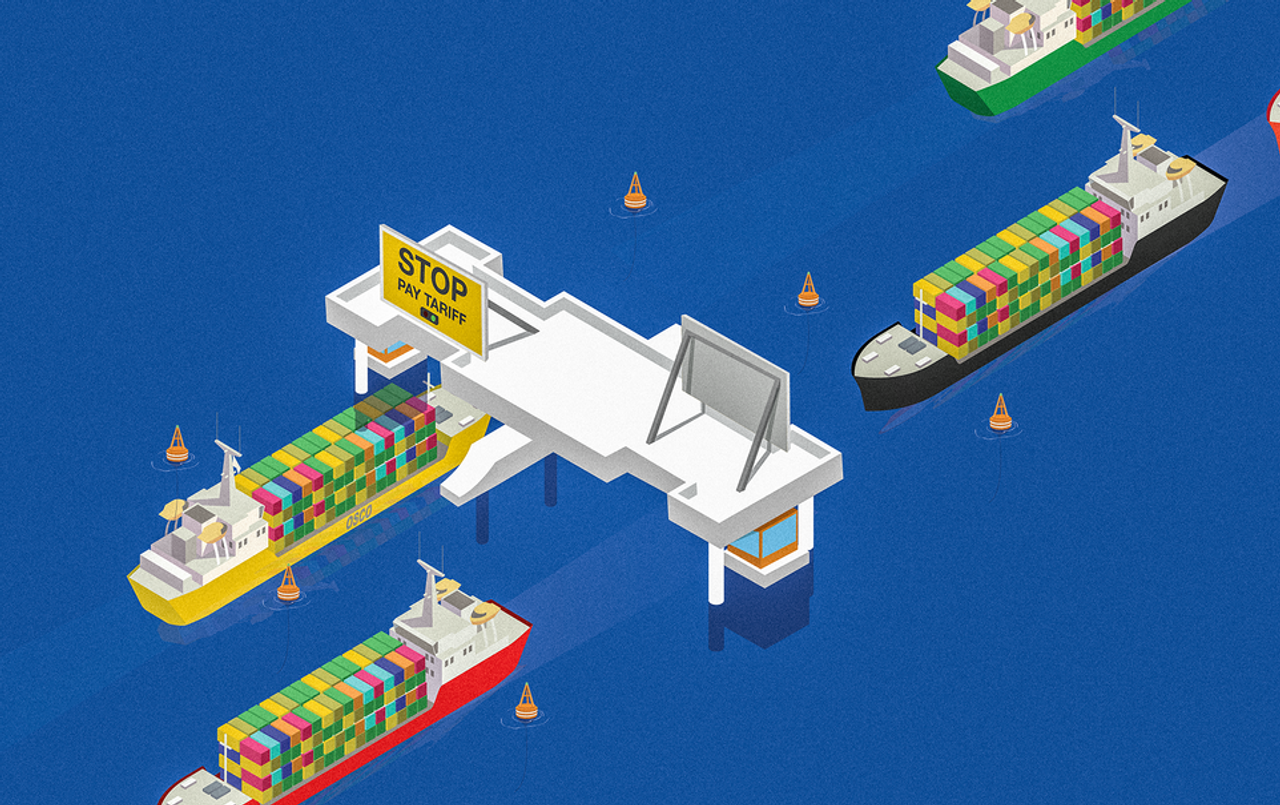
Tariffs are becoming an entrenched tool tying together geopolitics and trade , and they are playing a bigger role in long-term manufacturing and sourcing decisions. Nowhere are they hitting harder than in China, where importers and exporters are navigating an increasingly complicated regime of levies on goods ranging from semiconductors to mattresses.
“Tariffs have always existed and they’ve always been regarded as a cost of doing business,” said Simon Geale, executive vice president of procurement at supply-chain consulting firm Proxima. “But they’ve been getting much more teeth in the last five or six years.”
The new era of tariffs kicked off under the Trump administration with duties on imports from a swath of countries and a focus on Chinese products ranging from truck chassis to consumer goods.
The Biden administration kept most of the tariffs in place, and then added further duties on Chinese steel, semiconductors and electric vehicles, citing national security concerns and an industrial policy aimed at reviving American manufacturing .
The two candidates in this year’s presidential election look set to continue the trend, as trade, manufacturing and the tools to tie them together take a prominent role in the campaign.
Former president Donald Trump , the Republican nominee, has said he would roll out new tariffs with a potential 10% across-the-board duty on imported goods and a 60% tariff on goods from China.
Vice President Kamala Harris , the Democratic nominee, so far hasn’t indicated a desire to deviate much from President Biden’s trade policies.
Before becoming vice president, Harris diverged from Biden on Trump’s revised North American Free Trade Agreement, known as the United States-Mexico-Canada-Agreement. As a senator, Harris joined some Democratic lawmakers, saying it didn’t do enough to address climate change, suggesting Harris may have more of a focus on social justice issues when considering trade pacts.
Harris has been in lockstep with the president in the Biden administration.
At an electronics factory in Wisconsin last summer, Harris said she and Biden want to bring manufacturing jobs back to America. At a campaign event in North Carolina on July 18, she said Trump’s proposed universal 10% tariff “would increase the cost of everyday expenses for families.” She didn’t criticise current tariffs on Chinese goods .
Both Trump and Harris opposed the Trans-Pacific Partnership, the expansive multination trade deal that was designed to expand alternatives to trading with China. Trump withdrew the U.S. from the agreement immediately on taking office in 2017.
The trade policies pose a conundrum for companies. Do they continue sourcing from China and risk the potential impact of escalating tariffs? Or do they look outside China, where costs are higher, but duties and other geopolitical risks are lower?
Trump’s threat of universal tariffs has even spooked supporters. Tesla Chief Executive Elon Musk , who has endorsed Trump, said he would delay a decision on a new plant in Mexico until after the election because “it doesn’t make sense” if Trump wins and puts “heavy tariffs” on vehicles produced there.
Shifting supply chains to other countries is complex. Companies must find new suppliers of raw materials and finished goods. Suppliers and sub-suppliers must be vetted to make sure they don’t violate increasingly stringent U.S. rules on issues such as forced labor.
Anne van de Heetkamp , a vice president of product management at supply chain and logistics technology company Descartes , said when trade tensions started ratcheting up five years ago companies weren’t in a hurry to shift supply chains. Now that the duties appear more permanent, Descartes’s customers are mapping out new global supply networks.
Surging exports out of Southeast Asia, India and Mexico suggest Newell isn’t alone in its desire to reduce reliance on China. The shifts are fuelling new logistics investments in factories, warehousing and transportation operations around the world.
DHL Express U.S., a parcel unit of German logistics giant Deutsche Post , added a new direct flight between Vietnam and the U.S. in 2022 to cater to rising exports that used to reach the U.S. via Hong Kong. CEO Greg Hewitt said the unit is also looking at expanding its networks along the U.S. -Mexico border to serve surging demand there.
Hewitt cautioned that China remains the world’s top supplier of manufactured goods and will likely hold that position because of its streamlined supply chains and low costs for raw materials and labour.
Retail industry trade groups and some executives warn some items can’t be produced anywhere else in the world and that escalating tariffs will simply raise consumer prices and fuel inflation. Analysts at Goldman Sachs estimate that every percentage point increase in the overall U.S. tariff rate would increase core consumer prices by just over 0.1%.
“The problem is the best place to make shoes is China,” said Ronnie Robinson, chief supply chain officer at Designer Brands , parent company of footwear retailer DSW.
Robinson said for every dollar the government adds in tariffs, consumers pay an extra $2 to $4 at the checkout. “The reality is that you and I are paying for the tariffs as part of the ticket price when you go into the store and buy,” he said.
Robinson said Designer Brands sources about 70% of its footwear from China, down from 90% several years ago. He said the company aims to reduce its reliance further to about 50%, but China will remain the company’s largest single source of shoes.
Peterson said just 15% of Newell’s goods rely on products made in China today, down from more than 30% several years ago. He expects that by the end of next year the share will fall below 10%.
He said that when the company is searching for new Chinese suppliers one of its first questions is whether they have capacity or plan to add capacity outside the country.
“If a supplier doesn’t have manufacturing capability outside of China, we will not select them as a vendor for us,” he said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

The PG rating has become the king of the box office. The entertainment business now relies on kids dragging their parents to theatres.

Rugged coastal drives and fireside drams define a slow, indulgent journey through Scotland’s far north.