The Big Work Lie: Being Indispensable Will Save Your Job
Becoming the only staffer with certain skills might feel like insurance. To some bosses, it’s a red flag.

 4 min
It’s career advice we’ve all heard: Make yourself indispensable. Many who thought they’d accomplished that goal have been burned in recent white-collar layoffs .
Jilted workers and others who’ve witnessed job cuts say there’s no such thing as an irreplaceable employee. Some contend striving to be untouchable at work can backfire or invite exploitation. You can naively do more than what’s required, thinking effort means job security, then get axed anyway.
That disillusionment is fuelling debate over the wisdom of pursuing indispensability, often along generational lines. Older workers recount times when they survived rounds of job cuts by being too skilful or versatile to let go, while their younger counterparts tend to share examples of great performances that yielded no protection.
Beth McLaughlin McDonald , 52, is a recent convert to the more cynical side.
Though she’d endured three layoffs over the years, she still believed it was possible to become bulletproof when she took a recruiting job in 2022. Working remotely in Savannah, Ga., she was promoted quickly and felt she made her team at a healthcare-technology startup better by shouldering tasks that used to bog down others.
“I truly thought I was indispensable,” McLaughlin McDonald says.
She discovered she wasn’t when the company downsized last year. In less than an hour her department was slashed from 13 employees to three, she says. Each affected person was given notice in a five-minute video call. McLaughlin McDonald now thinks nobody is ever safe, so she works several part-time jobs, believing it’s wise to have multiple income streams in case one dries up.
It isn’t that the labor market is in a rout. The national unemployment rate remains at 3.9% and hiring exceeded economists’ predictions in the latest jobs report. Instead, two other factors drive workers’ pessimism: the march of artificial intelligence and the way cuts are handled .
I hear constantly from people who worry that AI-powered tools threaten positions that seemed secure a short time ago. Now that pink slips are frequently doled out virtually, in emails or on Zoom, many workers question whether they were truly valued in the first place.
Managers counter that workers’ job hopping in recent years, though slowing , means savvy leadership includes minimising a business’s dependence on individuals.
Some bosses say they strategically prevent employees from becoming irreplaceable. It isn’t sabotage, they insist. Rather, being overly reliant on their best team members is risky.
So if you sense a higher-up is trying to limit your importance, your gut might be right.
Too indispensable for anyone’s good
The veterinary technician was good at her job. Debbie Boone fired her anyway.
Boone managed veterinary clinics in the Carolinas for two decades before becoming an independent consultant and says she sometimes dismissed talented employees who hoarded knowledge to make themselves more valuable. She recalls this particular tech went further, stashing equipment manuals and implements in a private drawer.
“It was enhancing her status, but it was diminishing us as a whole,” she says.
Employees shouldn’t try to be indispensable, in Boone’s view. Being the only person with certain skills or information might feel like insurance. But it can lead to selfishness—and a surprise ouster by a boss who prefers team players.
Avin Kline , chief executive of the cannabis marketing agency Lucyd in Florida, says he expects most of his 55 employees to spend two to five years with the company. Understanding that turnover is inevitable, and perhaps imminent, he guards against individuals becoming essential.
Each client account has a point person, but those employees are required to share notes and reports with colleagues so that someone else can step in if needed. The idea: No account manager should be so important that a client would take its business elsewhere if the primary contact left the agency.
“When we have to replace someone, I want to feel that we’re losing somebody that’s providing a lot of value,” Kline says. “But I don’t want my business or myself to freak out.”
From irreplaceable to obsolete
Shannon Howard argues indispensability remains an ideal worth pursuing. The content-marketing director at a software company made that case recently to a group of college students near her home in North Carolina, urging them to resist the “ act your wage ” sentiment that drives many young workers, and others, to withhold extra effort.
At 31, Howard says she gets it. At-will employees can go above and beyond and get canned anyway, so why bother?
Still, “I’ve seen times when being the person who does their best, with a good attitude, saves someone’s neck,” she says. “At minimum, it builds a positive reputation and can help get another job.”
Jim Moechnig , laid off by a data-storage company in November, is still waiting for 17 years of service and good karma to be reciprocated.
He devoted nearly his entire tenure to a single software line, building unsurpassed institutional knowledge. Rather than irreplaceable, he says he came to be seen as one-dimensional.
When sales of his software slowed, his role was eliminated and job prospects for his narrow specialty were limited. Moechnig, 46, is working toward additional tech certifications that he hopes will yield new opportunities remotely or locally in Minnesota.
With several months to process his job loss, he takes a coolly objective view of the situation. His team was full of smart, hardworking people, but the business needed to cut costs. Ability provided no protection.
“If they were going to cut somebody, they were going to cut somebody good,” he says.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
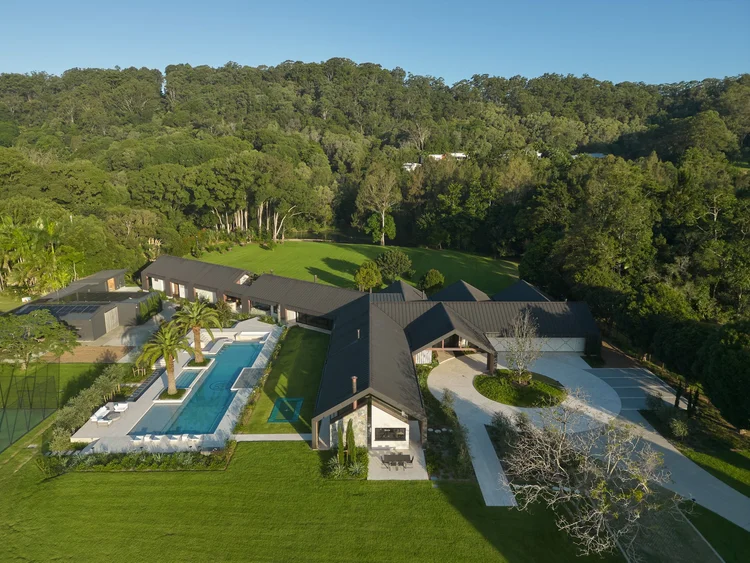
Margot Robbie may have travelled from a Queensland farm to the highest reaches of Hollywood, but a reported $28 million property deal suggests the Gold Coast has never lost its hold on her. The Australian actor and producer is believed to be the mystery buyer of Redwood, a seven-acre Currumbin Valley estate transformed into the …
Continue reading “Margot Robbie Reportedly Behind $28 Million Currumbin Valley Homecoming”
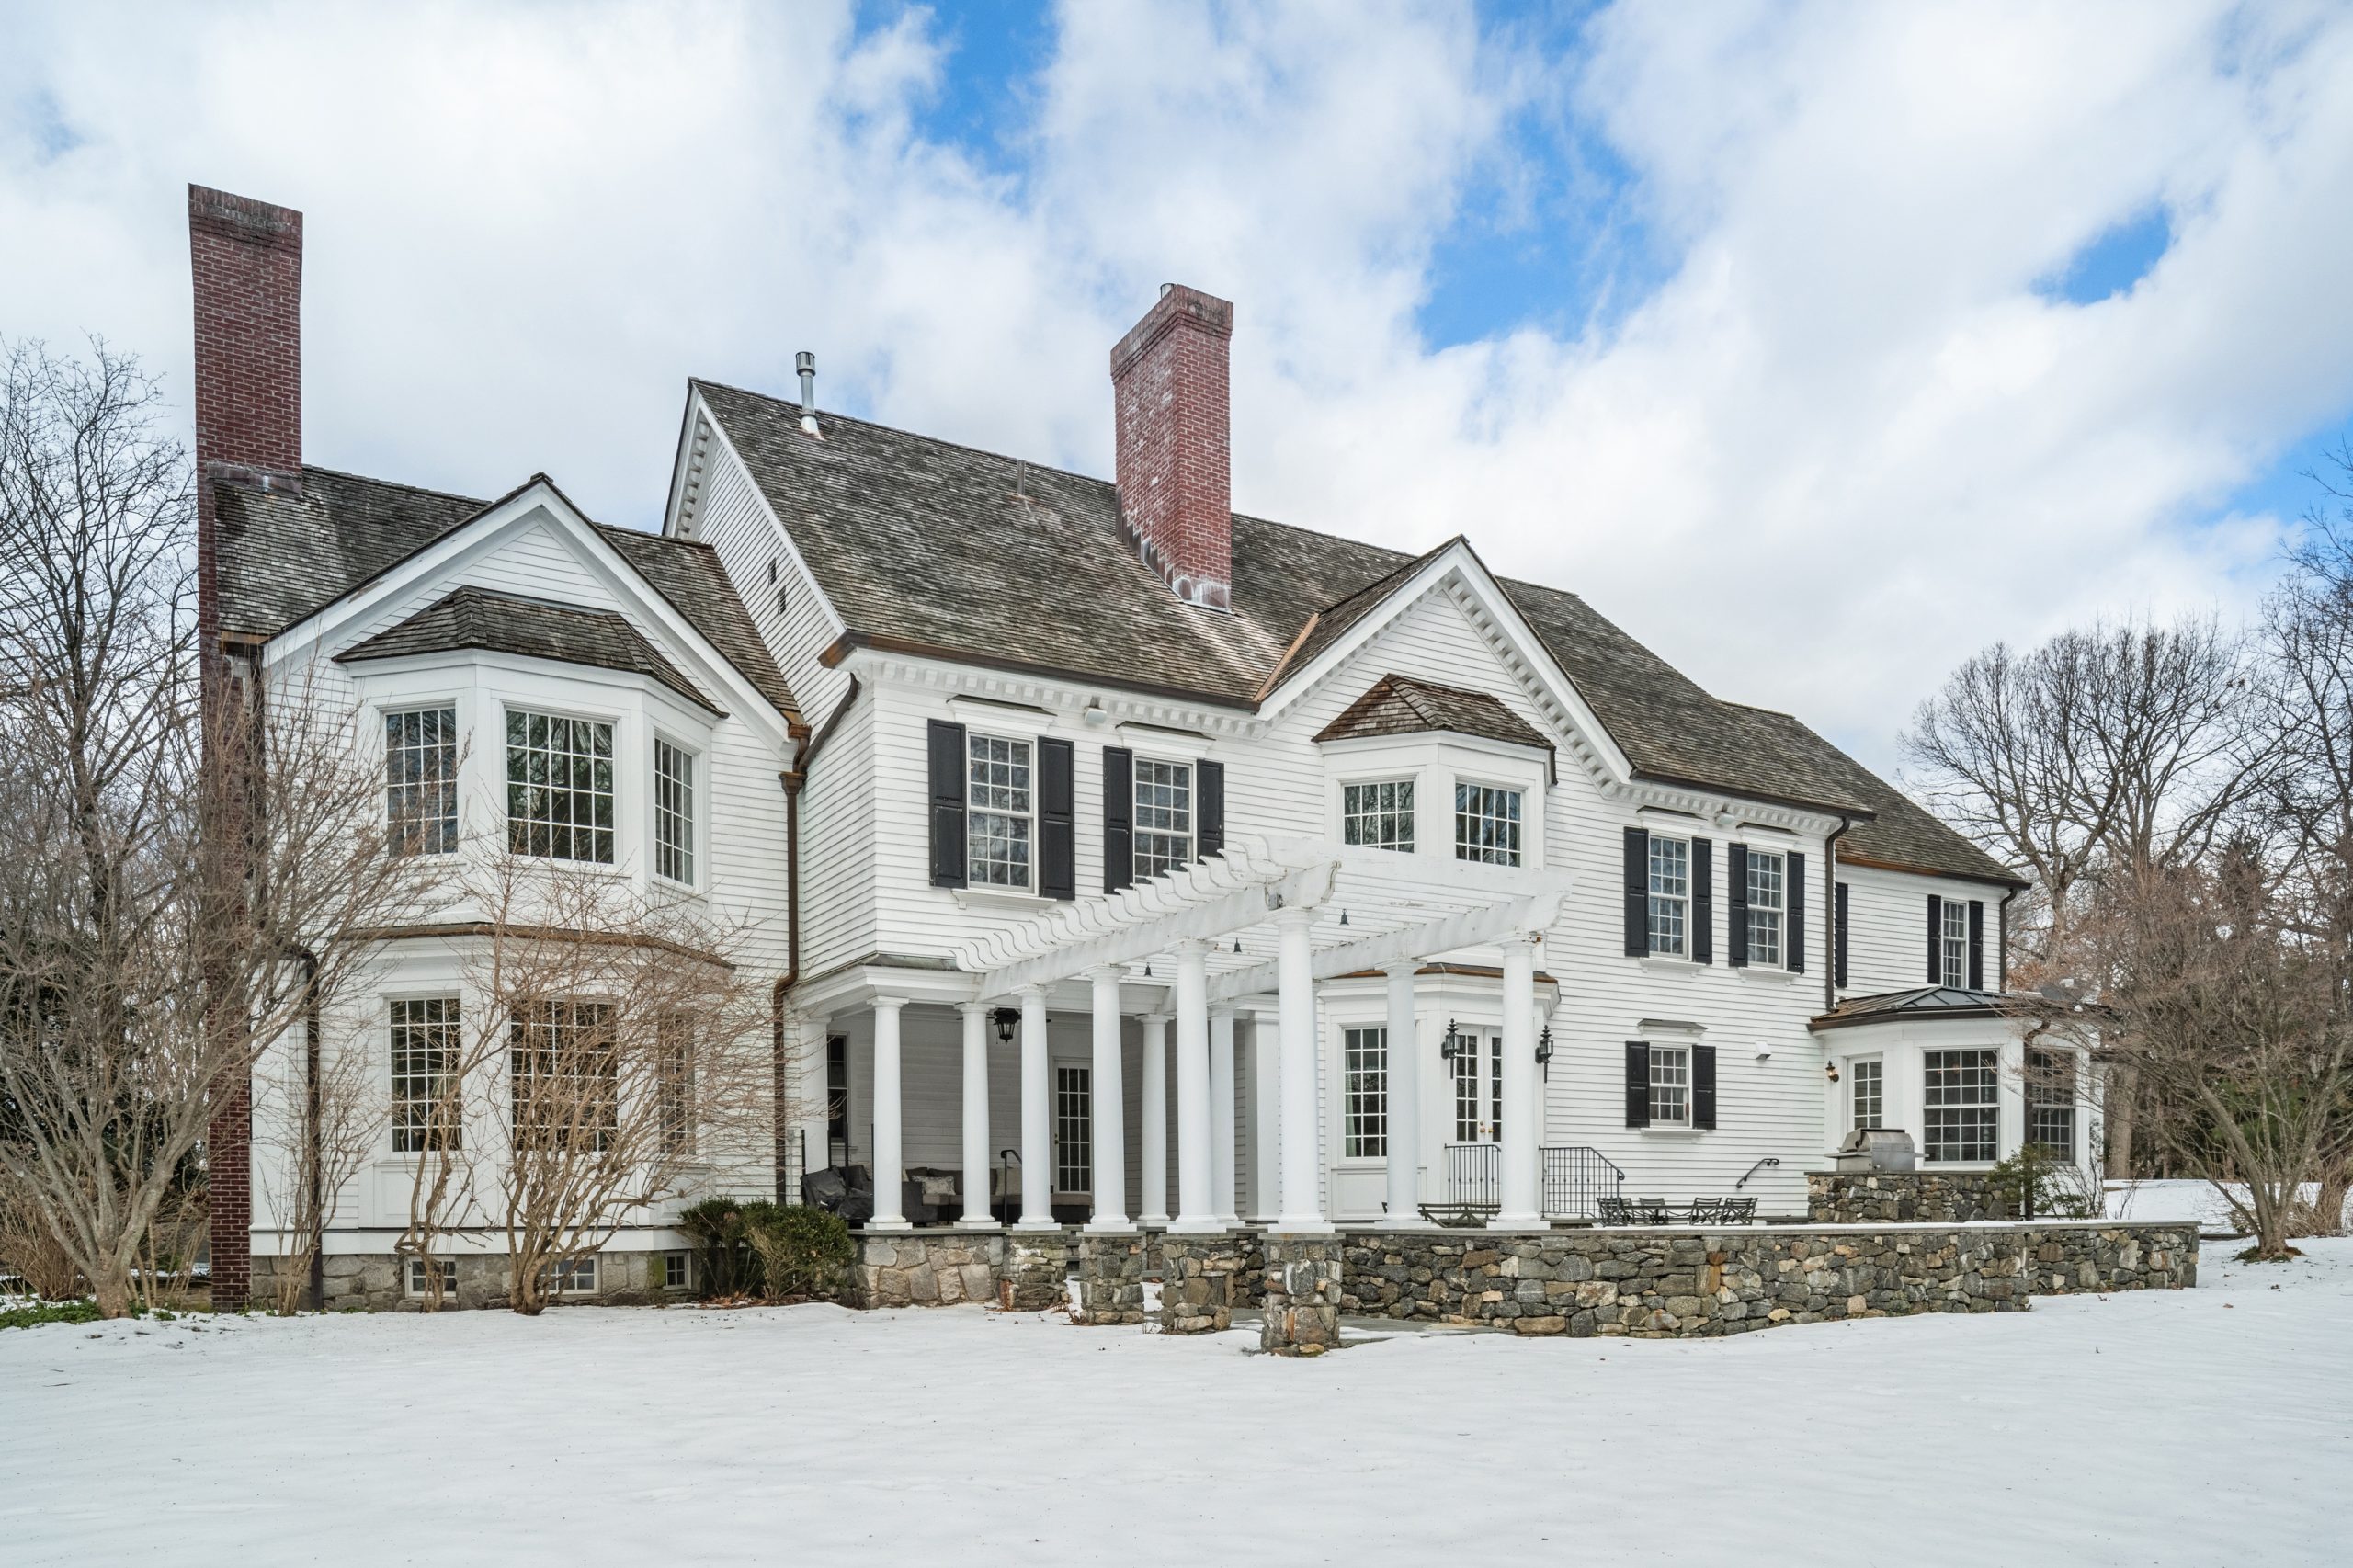
A haven for hedge-fund titans and Hollywood grandees, Greenwich is one of the world’s most expensive residential enclaves, where eye-watering prices meet unapologetic grandeur.