





The Reason the Office Isn’t Fun Anymore
RIP eavesdropping. Employees are now hiding out in privacy booths or empty conference rooms, turning workplaces into quiet zones. ‘It’s weird.’

 4 min
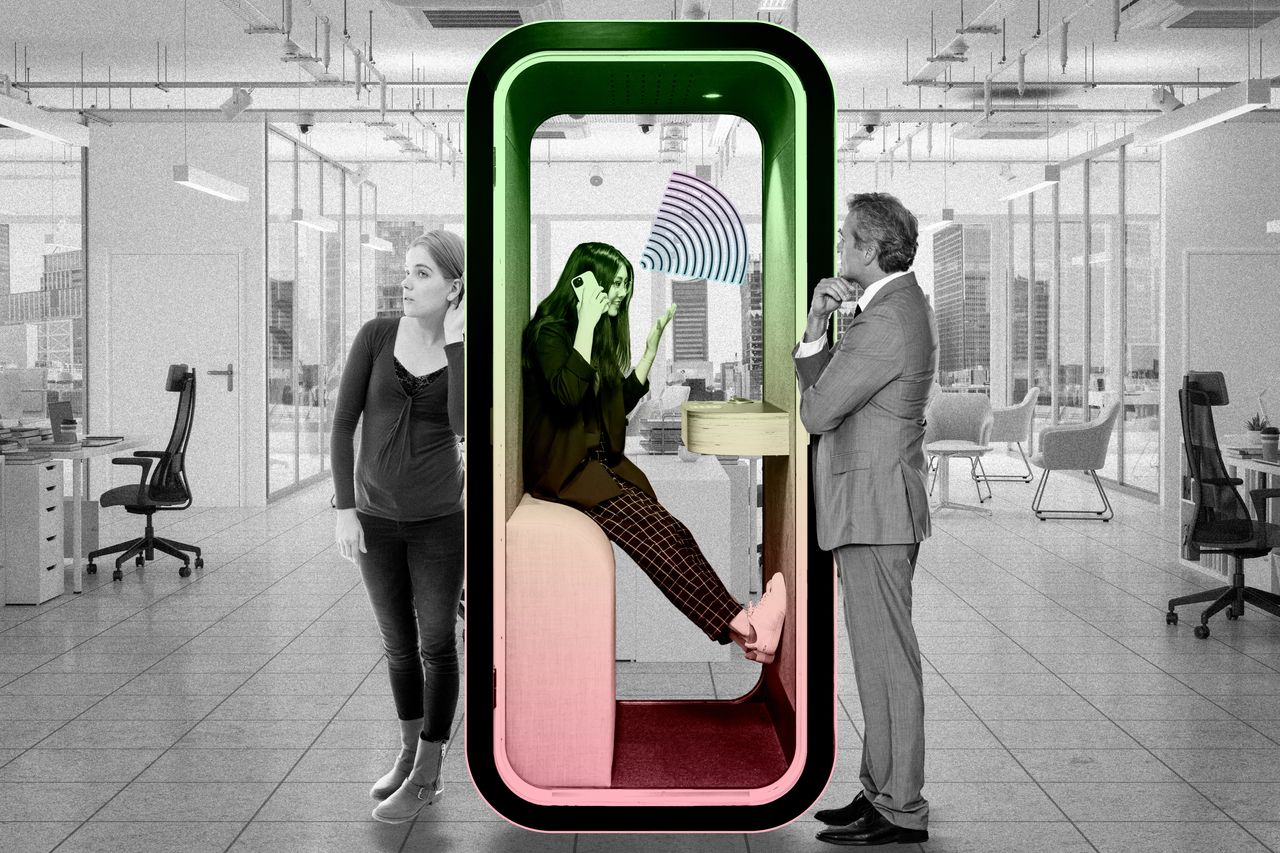
When David Witting prepared digital-marketing agency Dept@’s Boston-area offices for employees’ return in 2022, he ordered trendy couches, chairs and high tables, envisioning lively collaboration and banter.
Yet when his co-workers arrived, many skipped the furniture and gravitated toward the private booths scattered in the office. Since then he’s jettisoned some of the furniture, and added more booths.
“People are coming in to do occasional big meetings, but really the rest of the time, they want a quiet private spot to get on a Zoom call,” said Witting, a partner at the company. “It’s weird.”
As Covid-19’s remote-work surge fades, some workplaces are quieter and odder than ever. Employees have returned only to park themselves in deserted conference rooms or sound-muffling chambers. Colleagues grumble about booth-hogging co-workers, and some companies have started enforcing time limits on them.
The pods, some resembling old-school telephone booths, have emerged as one of the hottest segments in the $24 billion North American office-furniture industry. Manufacturers such as Room, Nook and Framery say business has been brisk. But some workers and managers say more booths means less eavesdropping, less gossiping, less camaraderie and less fun.
“It’s strange,” said William Blaze, a technology recruiter and consultant, referring to colleagues who end up occupying booths for much of their workdays. Blaze, who lives in Atlantic Highlands, N.J., observed the phenomenon while working at tech companies from 2021 to 2023, as well as at a client’s Manhattan co-working office where he now works two days a week.
“It seems that the goal of returning to office has been to create a rowdy buzz,” said Blaze. “We’re not seeing that.”
Janet Pogue McLaurin, global director of workplace research at architecture and design firm Gensler, said workplace privacy has never been more important. Many of the firm’s clients, which include big companies such as Amazon, have more than doubled their booths and other private or semiprivate areas since the pandemic.
“This is a huge trend,” she said.
Demand for privacy has office architects and landlords scrambling to rearrange layouts. Open-plan offices, often dreaded by employees, are now being peppered with pods and booths that scream “do not disturb.”
Jamie Hodari, chief executive of global co-working company Industrious, said some workers are monopolising private areas in office spaces that were designed for professionals to connect with other professionals. “We see a lot more people linger for two hours post-phone call or a Zoom call because they like having a little space to themselves.”
Booth-inclined office workers say their needs have changed post-Covid, and they have a harder time concentrating among noise and distractions.
At CrowdComms, a U.K.-based maker of event technology, managing director Matthew Allen got used to working in near-silence at the office during the pandemic. When colleagues returned, their phone calls—even at normal volume—annoyed him so much he bought a sound-dampening booth.
Though it was ostensibly for the entire office, he soon moved in.
“It’s quite selfish,” said Allen, who has added a trio of plants. “I think it has very much become my home.”
On social-media sites such as X, Reddit and TikTok, employees generally celebrate the booths. Even Chatty Cathys are seeking them out. One X user tweeted that she locks herself in an office phone booth most days because she talks too much.
Others vent about booths’ poor ventilation and small size, or their aesthetics. Kirsten Auclair, a biomedical researcher in San Francisco, shudders at the harsh lighting in the booths she uses to take Zoom calls at work.
“It casts like the worst shadows, you look just kind of, like, on the brink of death,” she said. Still, Auclair considers the oasis from colleagues’ noise an office lifesaver.
Booth manufacturers insist their products can coexist with collegiality. SnapCab founder and CEO Glenn Bostock said the glass walls of his company’s pods allow for a sense of connection with co-workers.
“They can see you,” he said. “You can wave at them. You can still interact with people visually but you get that audio privacy.”
Other products seek a different balance between isolation and community. Furniture maker Steelcase offers a desk-encircling tent meant to ensure “territorial privacy” instead of silence. Nook, headquartered in the U.K., makes hut-shaped hideaways intended to provide a sense of psychological safety without being completely enclosed.
Nook founder David O’Coimin said an office filled with phone booths “is like you have a jail instead of having a workplace.”
Furniture distributor Thinkspace sells booths that Sid Meadows, principal and vice president, said are designed to allow a low level of outside sound. Humans are wired to crave some background noise, he said, pointing to popular YouTube videos of ambient office chatter.
That matches the findings of a study co-authored by Dr. Esther Sternberg, director of the University of Arizona Institute on Place, Wellbeing and Performance. She and colleagues discovered people became stressed when their surroundings were too quiet as well as too loud. The typical volume of birdsong, at 45 decibels, appears to be just right.
Nick Fine, a user-experience researcher in London, describes himself as an “old school, pre pandemic office worker” who enjoys the hubbub of a busy workplace. But the now-hybrid worker still spends considerable time in an enclosed pod to work without overhearing his colleagues’ chatter on days he’s in the office.
“I have ADHD and working in a pod engages my hyper focus,” he said, adding he likes having the booth option when the din is too much.
Farmer’s Fridge, which sells fresh salads out of vending machines, has eight pods made by Zenbooth and a plethora of conference rooms in its Chicago office. It offers about 40 hideaways for the 85 people who work there, yet that bounty of isolation isn’t always enough, even for the CEO.
“I actually live three minutes from here,” said Luke Saunders, also the company’s founder. “If I really have to get work done, I do it at home.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
The grand harbourside residence combines sweeping Sydney Heads views, resort-style entertaining and refined designer finishes with a reported $36 million price guide.

Hand-built in Melbourne and limited to just 10 cars a year, the Zeigler/Bailey Z/B 4.4 is reshaping what a modern collector car can be.


