The Six-Figure Cars Drawing Enthusiastic Women Buyers

 5 min
Classic cars or SUVs painstakingly retrofitted with modern drivetrains and interiors, otherwise known as “restomods,” are selling out despite prices of US$200,000 to US$400,000 and up. And the buyers are not all men.
The world of classic cars is overwhelmingly male-dominated, but it turns out these modernized versions have a broader appeal, tapping into girlhood nostalgia, too. The specialty shops that make these cars, based on everything from the Mercedes 280SL and Chevrolet Chevelle to off-roaders like the Land Rover Defender and the Ford Bronco, are reporting that their lists of female clients are growing, and some are buying more than one.
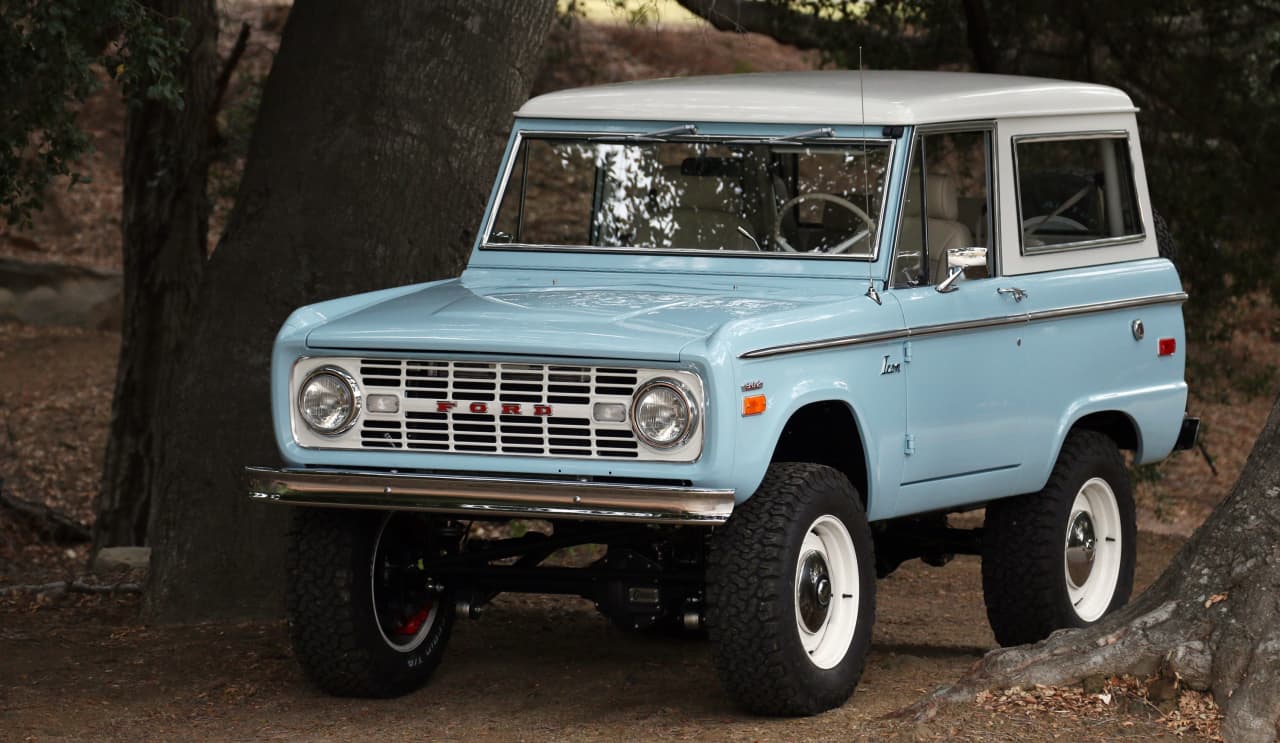
Jacqueline Comolli, who has homes in California and Maui, has a mid-US$300,000s Icon4X4 Ford Bronco, in orange and light blue, at each location.
“I’m happy with both of them,” she says. “I’ve only ever been drawn to old cars. They speak to me. But I can’t have a car that wouldn’t be safe or reliable. I don’t want to think that it’s about to break down.”
Icon4X4
Comolli reports that she’s using the orange Bronco, fitted with a modern Ford five-liter “Coyote” V8 producing 420 horsepower, in Maui as her daily driver.
“It really connects with people who see it, in the way a regular expensive luxury car would not,” she says. “The older cars that people remember just evoke a feeling.”
Restomods are bespoke commissions, encouraging their owners to get involved in choosing colours and materials. Comolli says she sent in a “ratty old bikini top and a high-heeled shoe” for the colours she wanted.
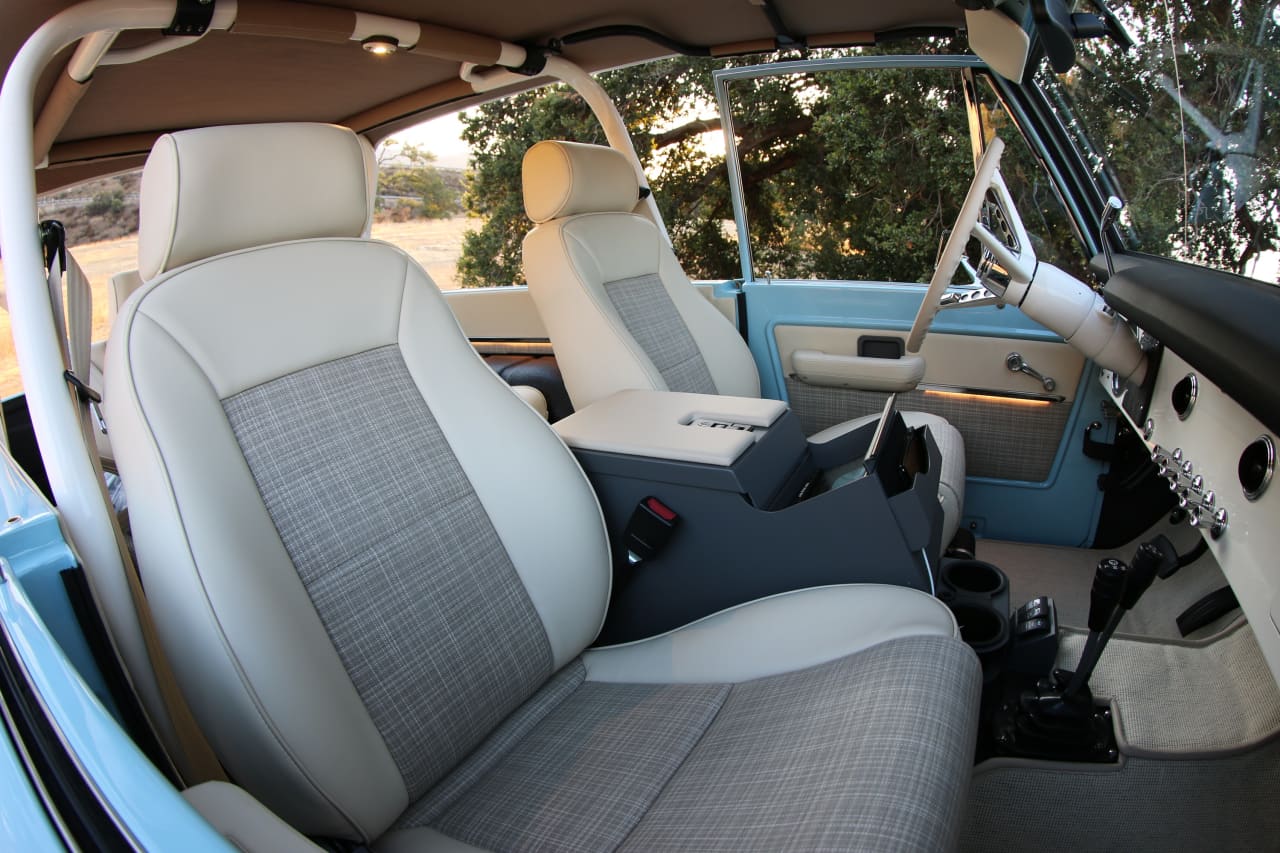
Icon4X4
Though the colour inspiration might be a bit different, the priorities of male and female clients are “pretty much the same,” says Jonathan Ward, CEO and lead designer at Icon4X4.
“They want enhanced performance, safety, and ease of service, while maintaining the vintage style and vibe.” He added that only 5% of his customers are women now, but “we are seeing more female interest.”
Emme Hall is a California-based auto writer who is very hands-on with her 2001 Mazda Miata off-road racer.
“There are fewer women who are car people today, and traditionally we haven’t had the same opportunities to work on cars,” she says. “When I wrench on my car I have to watch YouTube videos to avoid making mistakes. But when you buy one of these restomods, you get a dream car that is already done for you. The reliability and the workmanship are guaranteed.”
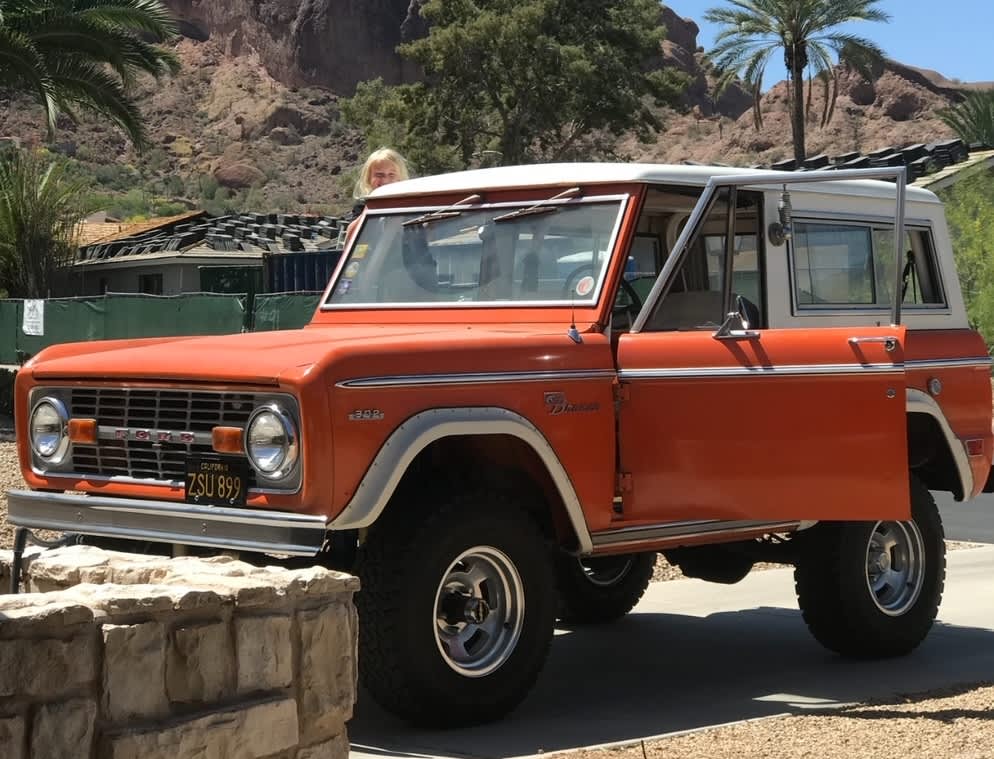
Katy Schuman
Katy Schuman, who drives a car from Illinois-based Gateway Bronco built to her individual style, is an interior designer who has also worked with Gateway on the details of another pair of Bronco builds. She has a second restomod on order, a Defender being built by the Landrovers, a company in Holland. Schuman’s husband drives a blacked-out LS3-powered 1968 Chevrolet Chevelle restomod with an eight-speed push-button automatic that was originally special-ordered by comedian David Spade from Florida-based Velocity.
Schuman says that her Bronco was built from a second-hand 1969 car that she and her husband had on the road for 12 years.
“They completely rebuilt our old Bronco,” she said. “It’s a lot smoother now with a new chassis, stronger brakes and motor.” When the Bronco was just a well-worn used car it broke down frequently, often while Schuman was ferrying the kids to school. “It was usually the battery,” she says.
Wales-based Hemmels completely rebuilds Mercedes SLs to exacting specifications, and CEO Thomas Butterfield says that 10% of his clients are women—more than most of the competition.
“Our women buyers are exceptionally focused on detail, and they thrive on the car being custom and bespoke,” Butterfield says. “There’s a reason one-off handbags from Hermès sell for millions, because they’re statements.”
He added that the company has matched exterior and interior colors from handbags, flecks of house paint, and shades of nail varnish.
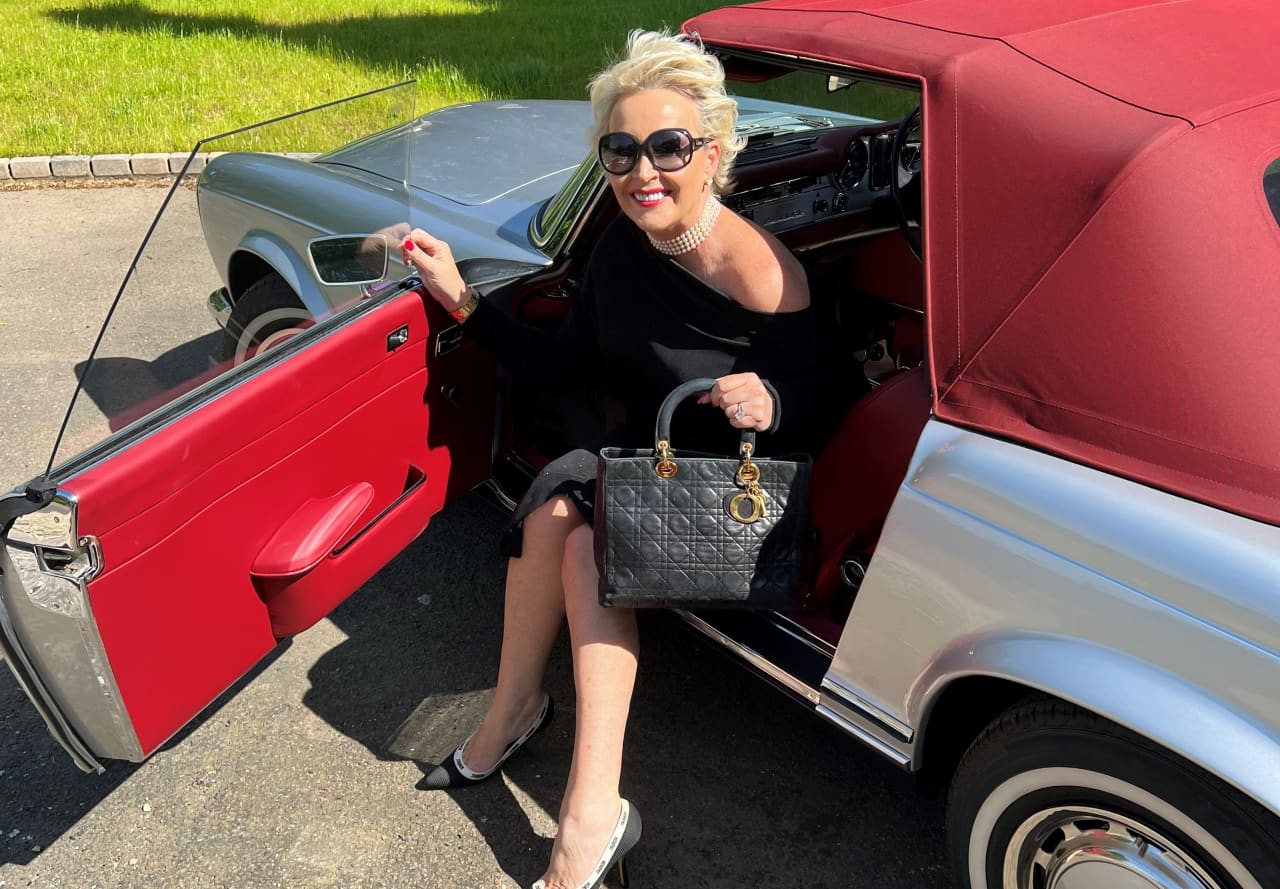
Tessa Hartmann , a Scottish branding strategist in the fashion and entertainment space who appeared on ITV’s Real Housewives of Jersey for two seasons, first fell in love with Mercedes sports cars as a child when she saw movie star Grace Kelly in a 190 SL. Hartmann first owned “Grace,” a 1969 Mercedes 280SL “Pagoda” that she’d traded for her Maserati Ghibli. But the car needed a lot of expensive loving care and attention, and a restoration through a local shop stalled—in part because, Hartmann felt, the owners took advantage of a woman client. Hartmann decided to swap Grace for a restored SL.
“It was at that point that I discovered Hemmels,” Hartmann says. “I felt bad for Grace, but I named the new car ‘Doris’ after Doris Day, who also has an effortless charm and a wholesome femininity about her.”
Hartmann notes that her four kids thought she was making an eccentric move, which prompted the thought that “it’s O.K. for a man to idolise engines, exhaust, and torque, but if a woman expresses an interest in cars, especially classic cars, she’s eccentric? Frankly I couldn’t have cared less what people thought. I was in charge. I had earned the right to do what I wanted. I am a workaholic and if this was my vice, so be it.”
Doris has had a makeover, and Hartmann took delivery of the 1970 car last year, paying around £220,000 (about US$280,000 and minus the £70,000 she got for trading in Grace). “Doris has a silver body, red leather interior, a red roof, and a hardtop—she’s quite magnificent, and the craftsmanship from Hemmels is impeccable,” Hartmann says. “Doris only gets to come out on sunny days. I feel an immense pride in being able to have one of these cars—it was an achievement many years in the making.” She’d buy another restomod, and thinks they hold their value well.
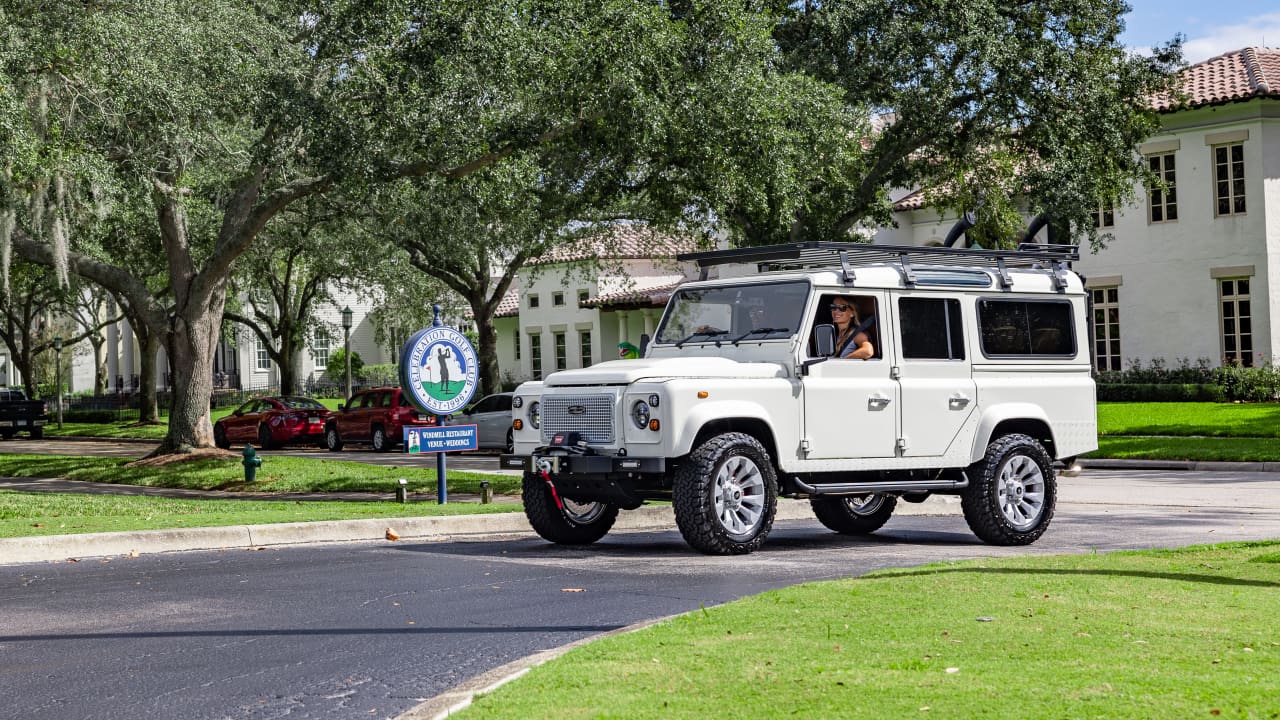
E.C.D. photo
The ride owned by Diane Johnson-Marchand and Tania Marchand, is a restored bright-white 1990 Land Rover Defender 110 known as “Island Girl” in right-hand drive, upgraded to 455 horsepower via a GM LT1 V8. The builder, at a cost of around US$300,000, was Florida-based E.C.D. Automotive Design, which also restores Jaguar E-Types and Mustangs and has a little more than 6%female clients.
E.C.D. CEO Scott Wallace says the women he’s worked with bring a unique “perspective and flair” to their custom builds, “resulting in one-of-one vehicles that truly stand out. Their attention to detail and passion for design continually inspire us.”
Johnson-Marchand, a veterinarian in the Daytona Beach area of Florida, learned to drive in a Defender in Hawaii. That one was right-hand drive, so the new one had to be, too. She wanted an alloy-bodied car, located one in South Africa, and imported it to the U.S. before handing it over to E.C.D. for a nine-month build.
“We spent a month just on the design and personalised many aspects of the car,” Johnson-Marchand says. “And there were several on-site visits. E.C.D. kept us posted each step of the way, so we were able to see the car through the assembly process. Vintage looks combined with a modern drivetrain, that combination allows us to have the best of both worlds.”
There is actually a club for women supercar owners, the Arabian Gazelles, based in Dubai. Seeing the growing trend, similar organisations could take root around the world.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Four decks, 34.5 metres and a made-to-measure interior: step aboard the new Custom Line Navetta 35, unveiled at Cannes.
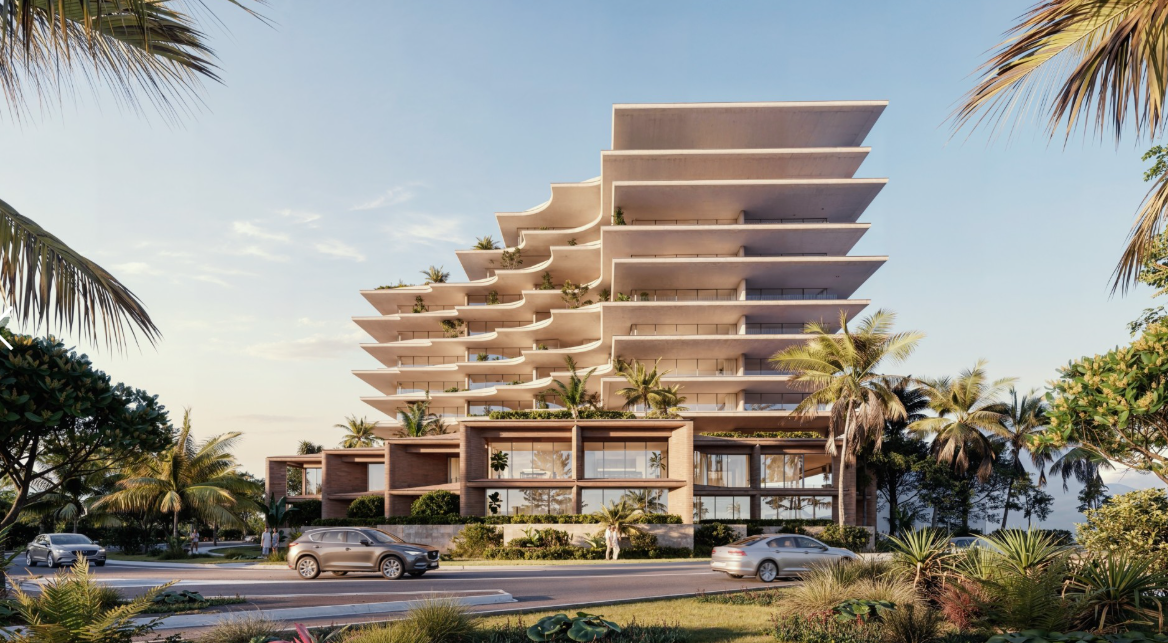
Queensland-based builder-developer MAYD has unveiled an exclusive first look at its anticipated ultra-luxury North Kirra mixed-use project as it lodges a minor amendment with the City of Gold Coast Council. The project sits across a 4,742sqm amalgamated landholding spanning seven parcels at 2–6 Pacific Parade and 27–33 Golden Four Drive, Bilinga, which MAYD secured in …
Continue reading “MAYD”s North Kirra Plans Unveiled Ahead of Early 2027 Launch”