





2024 Mercedes-AMG GLE 63 S Is a Coupe on V8 Steroids

 4 min

The coming model year brings an updated machine into the Mercedes-Benz AMG garage: a large, powerful coupe launched by a wonderfully inappropriate V8 engine.
The 2024 Mercedes-AMG GLE 63 S is a type of vehicle that didn’t exist for previous destinations. Bigger than some lesser SUV models at 195-inches long and weighing more than 2.5 tons, the AMG GLE 63 S rides higher than most Mercedes-Benz models. It lives under the coupe label despite its four-door frame, preserving the moniker with a hard top roof and sloping rear lines. Still, as the 63 S muscles its way along from its almost 118-inch wheelbase to its broad haunches, its visual impact says “coupe, but on AMG steroids.”
If there’s a challenge to overcome in getting comfortable with the GLE 63 S Coupe, it’s those visuals. With so many modern vehicles on the road taking the form of SUVs or crossovers that are really no more than large hatchbacks, the sight of a vehicle that’s none of the above while also shrugging off the modest lines of a sedan takes some getting used to from the outside. Still, once the driver makes that adjustment, he or she can get on with the enjoyment of driving an AMG-tuned Mercedes barely tamed brute.
More:From Handbags to Classic Cars—the Value of Collectibles Is up 7% Annually
For the uninitiated, AMG is the Mercedes-Benz tuning shop where already great cars become more aggressive. AMG amps the power and handling abilities, adds more than a few more bucks, quid, or euros to the price tag and hands them along to serious driving enthusiasts.
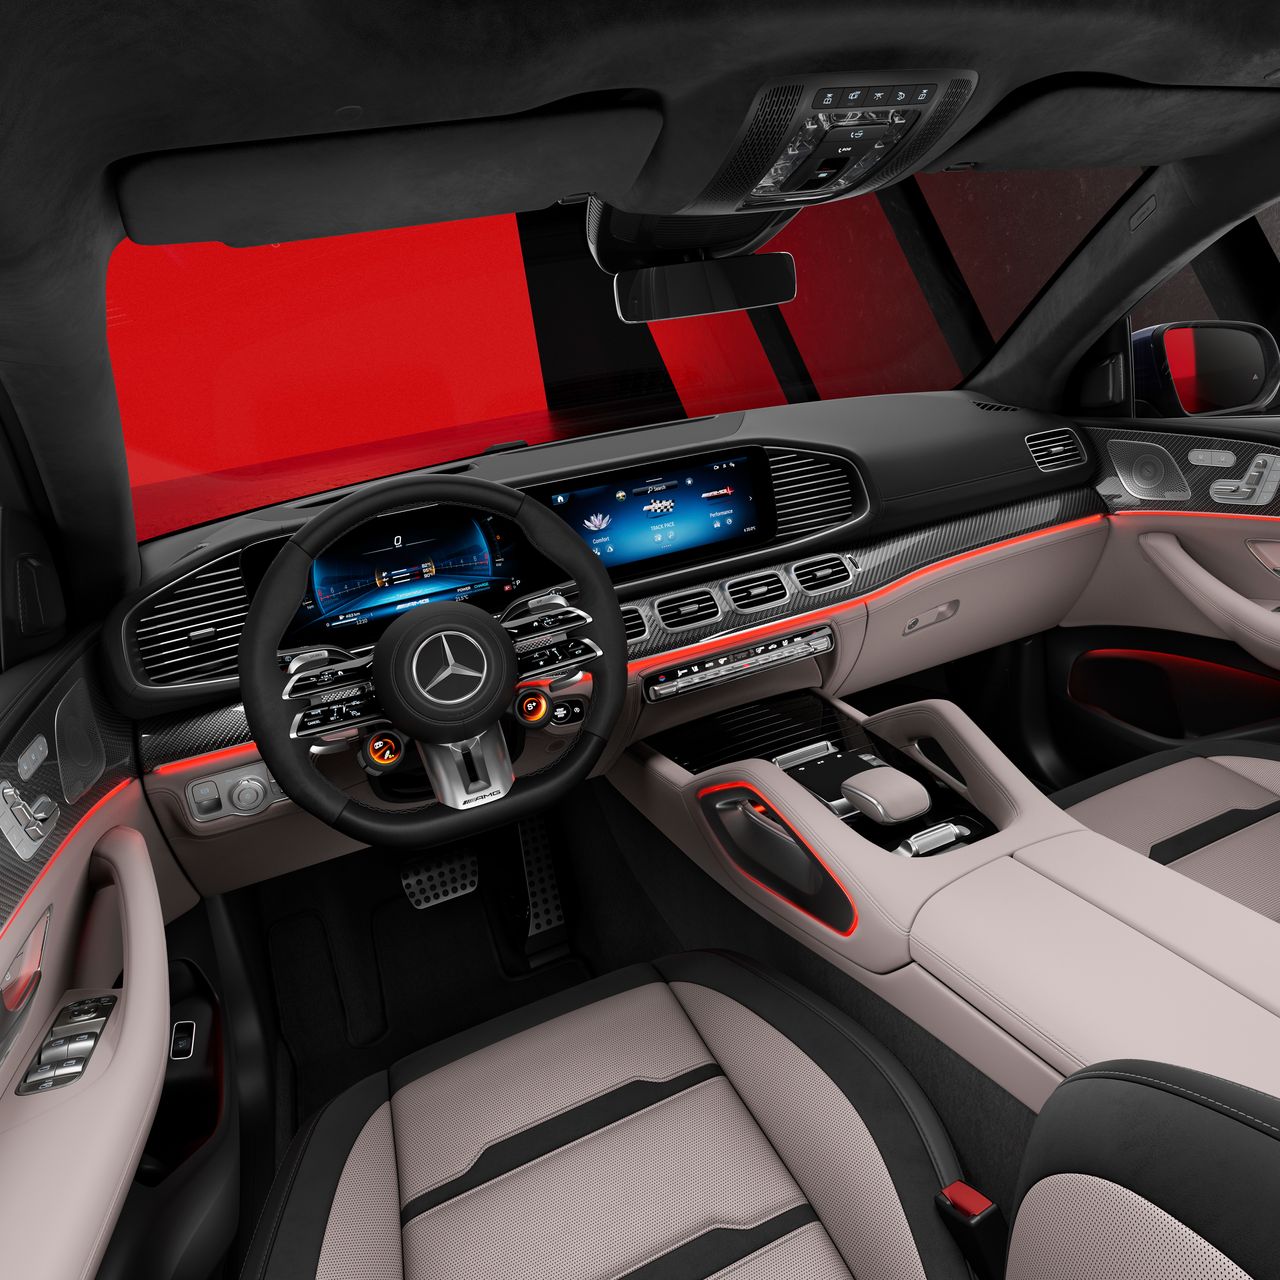
For the GLE 63 S, the shop penned in a handcrafted 4-liter V8 Biturbo beast under the hood—but at least nodded to environmental concerns by layering electric hybrid assist. The result of all that uncompromising German engineering is 603 horsepower and a 0-to-60 time of 3.8 seconds. That’s serious, “snap your head back” speed in a large, solidly built vehicle.
A combination of AMG Speedshift TCT 9-speed automatic transmission with sport paddle shifting and all-wheel drive with fully variable torque distribution keep all of that power on the road. The end result driving experience features a grounded, balanced, and stately ride that elevates the owner above the ugliness of common pavement—with truly aggressive, roaring power waiting if you put your toe down in Sport or Sport+ mode.
Michael Knoeller, head of marketing and sales at Mercedes-AMG, says a lot of planning and thought go into how the company maintains two identities: an automaker providing traditional, tuned power and performance for enthusiasts, while also forging technology for electric vehicles.
“Mercedes-AMG is in the transformation phase in the mid- and long-term,” Knoeller says. “While our handcrafted V8 powertrains will continue to be offered in familiar models for some time, we are also working on AMG’s own BEV platform, AMG.EA. This will enable us to meet a wide range of customer needs in markets where the V8 engine continues to play a role, as well as with our all-electric EQ models.”
And regardless of the drivetrain technology, a Mercedes has to be a Mercedes, Knoeller adds. There are high expectations for buyers of make and its models, whether or not they’re AMG-forged vehicles.
“All Mercedes-AMG models must deliver on our brand promise of superior performance and unique technology,” he says. “In doing so, we can adopt certain technologies from the world of combustion engines, while other technologies we develop completely from scratch.”
As for what purpose the 2024 AMG GLE 63 S Coupe plays in this grand scheme of old meets new and power meets preservation, the answer is a mixed grill. The monster-sized coupe is large enough to serve as a luxury people carrier, but powerful enough for the occasional track day before standing in as a grand tourer with ample power.
“We think the GLE 63 S Coupe excels in a variety of areas,” Knoeller explains. “It perfectly meets the demand for luxury and comfort, while also offering ample space.”
More:Cadillac’s Escalade Goes Electric With Three-Row Luxury
He points to the distinctive, though challenging appearance as a plus that brings interested eyeballs to the vehicle, while the 603-horespower output looks to thrill the human behind the wheel. The Sport + dynamic driving setting is intended for track days and maximum driving entertainment, he says (even if there are more suitable products in the Mercedes-Benz portfolio for track days, such as the SL Roadster).
In terms of the future, Knoeller reassures passionate drivers that high performance models such as the GLE 63 S Coupe and its ilk will have a place in the Mercedes AMG family for a while yet.
“The segment of sporty SUVs and the demand for our models has grown steadily in recent years,” he says. “We also see further potential here in the long term, so there is no need to worry about the future of the GLE 63 S Coupe. We have already set the course for an electric future and recently presented our new Mercedes-AMG EQE SUV.”
The starting MSRP for the rides making up the GLE class start around US$80,000, with the AMG enhancements on the GLE 63 S Coupe nudging the price up to US$125,000 and beyond. If the lover of German meticulousness can get used to the edgy and nontraditional styling cues, he or she will buy into a unique blend of stately performance with deceptive and effective power.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
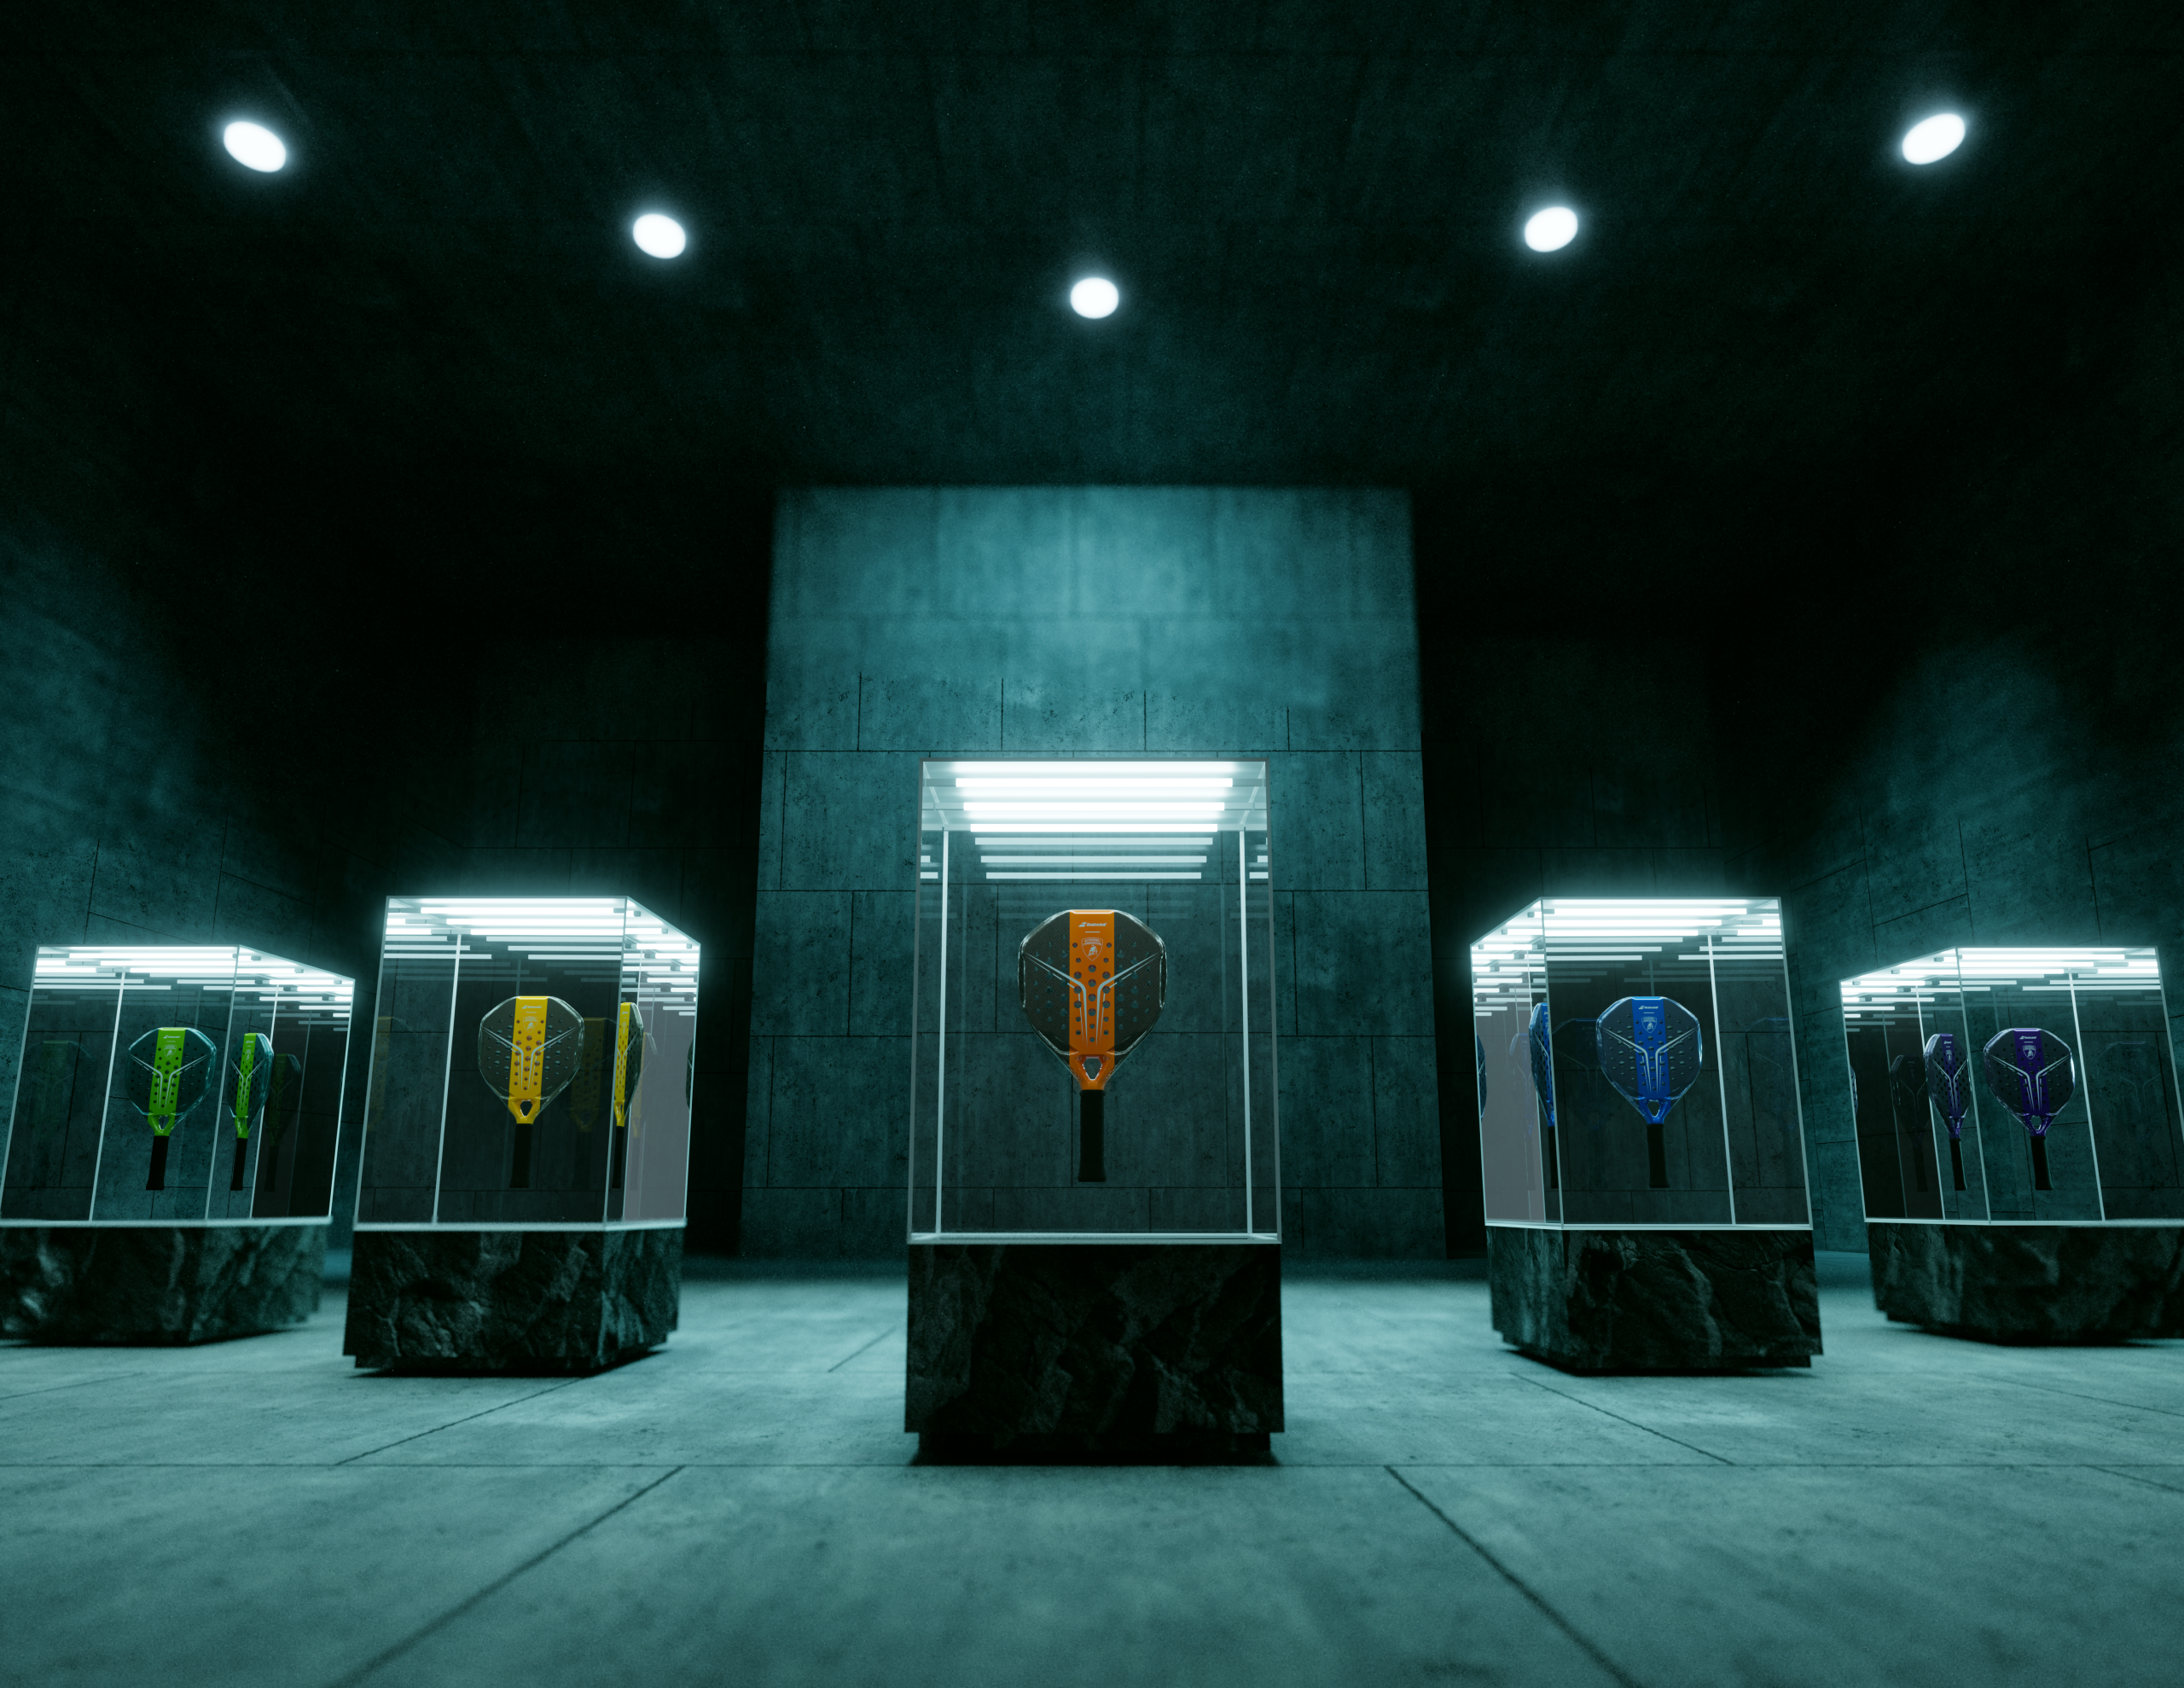
Automobili Lamborghini and Babolat have expanded their collaboration with five new colourways for the ultra-exclusive BL.001 racket, limited to just 50 pieces worldwide.

An opulent Ryde home, packed with cinema, pool, sauna and more, is hitting the auction block with a $1 reserve.


