7 Ways To Self-Fund Your Retirement Beyond Just Your Super
Super isn’t your only option. These smart strategies can help you self-fund a comfortable retirement.
 3 min

Superannuation is the first thought when it comes to self-funding retirement. Yet it is hardly the only option for doing so.
Just as we have a choice in how and where we work to earn a living, many people also have a choice in how to fund their retirement.
It is possible and sometimes preferable to leave your superannuation untouched, allowing it to continue growing. Some or all of your income can come from alternative sources instead.
Here are some alternatives you can consider.
1. Downsize your home
For many who own their own homes, the equity accrued over decades can eclipse the funds in superannuation. However, it’s theoretical money only until it is unlocked.
Selling up the family home and downsizing – or rightsizing – for retirement allows you to pocket those gains tax-free and simultaneously relocate to a more suitable home with lower upkeep costs.
Up to $300,000 from the proceeds can be contributed by a downsizer to boost your super, and the remainder can be used to fund living expenses or actively invested.
Remember that while the sale proceeds of your home are tax-free, any future profits or interest earned from that money will be taxable.
2. Part-time work
Semi-retirement allows you to gradually step into retirement. You continue earning income and super while working part-time, keeping a foot in the workforce while testing the waters of your new found free time.
Doing so also offers scope to move into different roles, such as passing on your skills to future generations by teaching/training others in your field of expertise, or taking employment in a new area that interests you and is closer to home.
3. Self-employment
Retirement from a full-time position presents a good opportunity to pursue self-employment. With more time and fewer commitments on your hands, you have greater scope to turn your hobby into a business or leverage your professional skills and reputation as an external consultant.
Also, for the self-employed and those with a family business, director’s loan repayments from the company are typically tax-free, offering a potentially lucrative source of
income and a means of extracting previous investments into the business without selling your ownership stake.

4. Investments
Rental property income (from residential or commercial properties) can supplement or even provide a generous source of income. The same applies to dividends from shares.
These are likely to be more profitable if you own them well before retirement.
Income that is surplus to your everyday needs can be reinvested using tax-effective strategies to grow your future returns.
5. Family trust
A family trust could be used to house investments for yourself and other relatives, building intergenerational wealth.
Trusts allow funds to be allocated to beneficiaries to manage marginal tax rates and stretch the money further, you have control over how income is split between different family members and have flexibility for changing circumstances.
6. Selling collectables
You may not realise the value of items you have collected over the years, such as wine, artwork, jewellery, vintage cars, and antiques.
Rather than have them collect dust or pay to store them, they could be sold to fund your living costs or new investments.
Where possible, avoid selling growth assets in a depressed market – wait until you can extract maximum value.
7. Obtaining a part-pension
Part-pensions are not only possible but valuable in making your superannuation stretch further. They still entitle you to a concession card with benefits in healthcare, transport, and more.
Take these savings even further by requesting pensioner discounts with other companies, on everything from utilities to travel and insurance to eating out.
Also, don’t overestimate the value of your assets as part of the means test. It’s a common mistake that can wrongly deny you a full or part-pension.
Plan ahead
However, you ultimately fund your retirement, planning is crucial. Advice would hopefully pay for itself.
Understand your spending and how those habits will change before and during retirement, then look to investments that offer the best fit.
Consider a mixture of strategies to diversify your risk, manage your tax liabilities and ensure ongoing income.
Above all, timing is key. The further ahead you plan, the more time you have to embrace additional opportunities and do things at the right time to maximise their value. You’ve worked hard and now is your chance to enjoy the fruits of your labour!
Helen Baker is a licensed Australian financial adviser and author of the new book, Money For Life: How to build financial security from firm foundations (Major Street Publishing $32.99). Find out more at www.onyourowntwofeet.com.au
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.

From elevated skincare to handcrafted home pieces, this year’s most thoughtful gifts go beyond the expected.
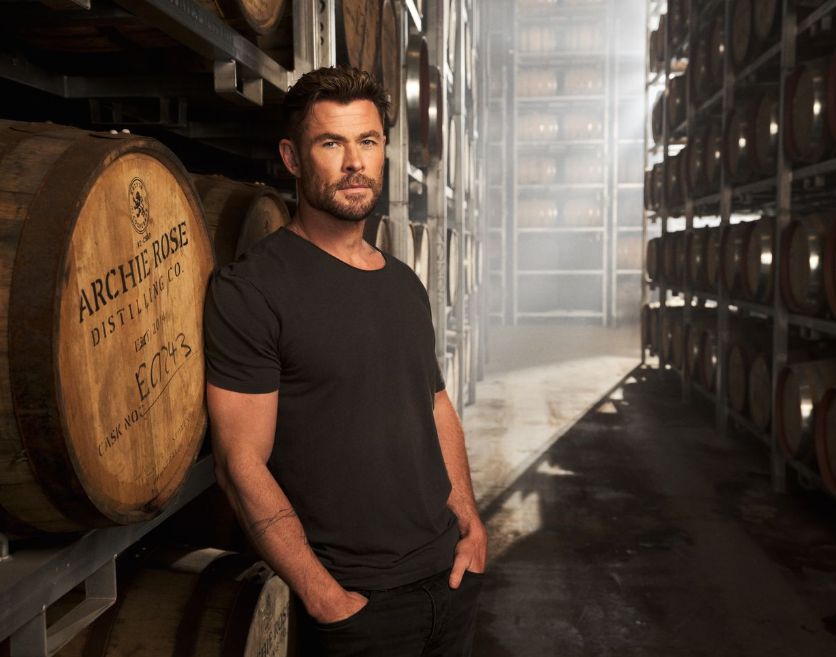
Australian actor Chris Hemsworth has joined Archie Rose Distilling Co. as co-owner and strategic business partner as the Sydney spirits company prepares to enter the United States. The partnership brings Hemsworth together with Archie Rose founder Will Edwards, with the pair aiming to build greater international recognition for Australian whisky. Founded in Sydney in 2014, …
Continue reading “Chris Hemsworth Joins Archie Rose as Co-Owner Ahead of Global Expansion”