Fed Raises Rates but Nods to Greater Uncertainty After Banking Stress
Officials voted unanimously to increase their benchmark short-term rate by a quarter percentage point

 5 min
The Federal Reserve approved another quarter-percentage-point interest-rate increase but signalled that banking-system turmoil might end its rate-rise campaign sooner than seemed likely two weeks ago.
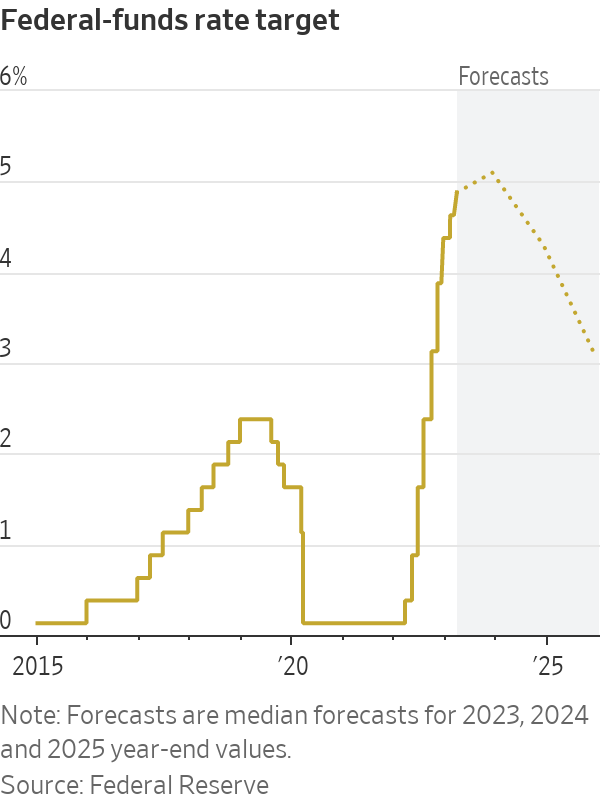
The decision Wednesday marked the Fed’s ninth consecutive rate increase aimed at battling inflation over the past year. It will bring its benchmark federal-funds rate to a range between 4.75% and 5%, the highest level since September 2007.
Officials sent a hint that they might be done raising interest rates soon in their post meeting policy statement. “The committee anticipates that some additional policy firming may be appropriate,” the statement said. Officials dropped a phrase used in their previous eight statements that said the committee anticipated “ongoing increases” in rates would be appropriate.
The policy statement said it was too soon to tell how much recent banking stress would slow the economy. “The U.S. banking system is sound and resilient,” the statement said. “Recent developments are likely to result in tighter credit conditions for households and businesses and to weigh on economic activity, hiring, and inflation. The extent of these effects is uncertain.”
All 11 voters on the rate-setting Federal Open Market Committee agreed to the decision.
New projections showed 17 out of 18 officials who participated in the meeting expect the fed-funds rate to rise to at least 5.1% and to stay there through December, implying one more quarter-point increase. The quarterly projections were little changed from those released in December.
Fed officials have at times over the past year acknowledged the risk of being forced to simultaneously fight two problems—financial instability and inflation. Several have said they would use emergency lending tools, along the lines of those unveiled this month, to stabilise credit markets so they could continue to raise interest rates or hold rates at higher levels to combat inflation.
At a news conference after the decision, Fed Chair Jerome Powell said officials had considered holding rates steady but opted to raise them given signs of still-high inflation and economic activity.
Various estimates of how much the banking stress could slow the economy amount to “guesswork, almost, at this point,” Mr. Powell said. “But we think it’s potentially quite real. And that argues for being alert as we go forward.”
That turmoil offers the strongest evidence yet of spillovers from higher interest rates to the broader economy. The upheaval has served as a stiff reminder of the perils Fed officials, regulators, lawmakers and the White House face trying to corral inflation that soared to a 40-year high last year.
U.S. policy makers cushioned the economic shock created by the Covid-19 pandemic in 2020 and 2021 by providing extensive financial aid and cheap money. Congress and the White House have largely delegated to the Fed the task of taming price pressures.
The fed-funds rate influences other borrowing costs throughout the economy, including rates on mortgages, credit cards and auto loans. The Fed has been raising rates to cool inflation by slowing economic growth. It believes those policy moves work through markets by tightening financial conditions, such as by raising borrowing costs or lowering prices of stocks and other assets.
Two weeks ago, Mr. Powell suggested officials would debate whether to raise rates by a quarter-point or a bigger half-point after reports showed hiring, spending and inflation were stronger early this year than they thought at the time of their Jan. 31-Feb. 1 meeting. “Nothing about the data suggests to me that we’ve tightened too much,” he said on March 7 before the Senate Banking Committee.
An astonishing run on the $200 billion Silicon Valley Bank changed everything. SVB’s depositors were heavily concentrated in the tight knit world of venture capital and startup firms, which were burning cash and withdrawing deposits as the once-highflying technology sector cooled.
On March 8, SVB said it was looking to raise capital from investors and that it would record a loss on longer-dated securities whose values had fallen as interest rates shot up. Nearly a quarter of the bank’s deposits fled over the next day and the bank was taken over by regulators on March 10.
To avoid a broader panic, federal authorities guaranteed the uninsured deposits of the California lender and a second institution, New York’s Signature Bank. The Fed also began offering loans of up to one year to banks on more generous terms as a precaution.
Banking-sector tremors are likely to lead to a pullback in lending because banks will face increased scrutiny from bank examiners and their own management teams to reduce risk taking. Banks could also see earnings squeezed if they feel pressure to raise deposit rates, which could further crimp lending.
That would mean fewer loans to consumers to buy cars, boats, homes and other big-ticket items, and less credit for businesses to hire, expand or invest, raising the risk of a steeper economic downturn.
Banks with fewer than $250 billion in assets account for roughly 50% of U.S. commercial and industrial lending, 60% of residential real estate lending, 80% of commercial real estate lending, and 45% of consumer lending, according to Goldman Sachs.
“I think we’re looking at a sizeable credit crunch,” said Daleep Singh, a former executive at the New York Fed who is now chief global economist at PGIM Fixed Income.
Since officials’ previous meeting, the economy had shown surprising strength, leading to concerns that aggressive rate rises over the previous year hadn’t done enough to slow the economy and lower inflation. Central bankers are concerned that prices will keep rising rapidly if consumers and businesses expect them to.
Inflation fell to 4.7% in January from 5.2% in September, as measured by the 12-month change in the personal-consumption expenditures price index excluding food and energy, the Fed’s preferred gauge. Economists expect the government to report next week that the inflation rate was unchanged in February.
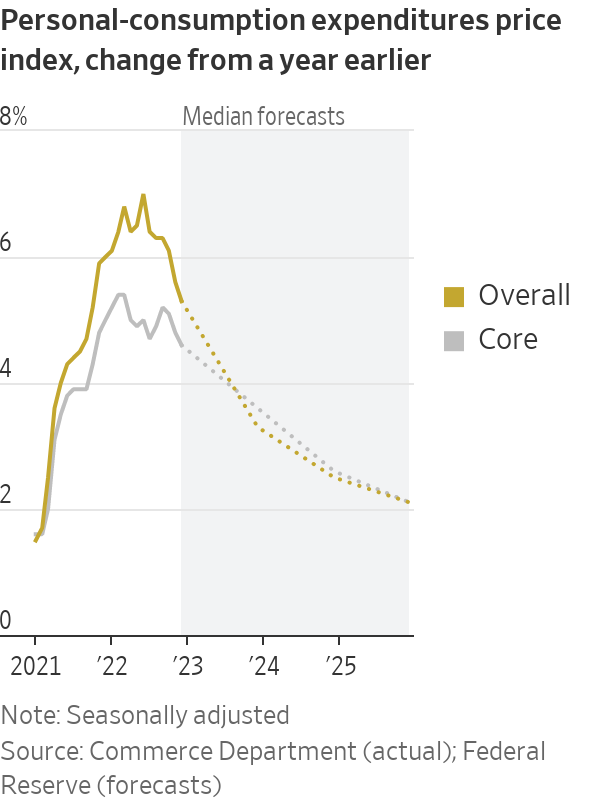
Banking stress had led to questions in the past week over whether the Fed would even raise rates at all.
Some analysts fretted that a timeout on rate rises would risk so-called financial dominance, in which monetary policy becomes overly focused on avoiding market stress to the detriment of fighting inflation. A big market rally, in which stock prices rise and borrowing costs fall, could spur more demand and fan price pressures.
“They’d like to avoid that,” said William English, a former senior Fed economist who is a professor at Yale School of Management.
Others said the Fed would have been hard-pressed not to raise interest rates given recent strength in the economy and aggressive measures taken to shore up confidence in the banking system.
“Right now pausing would cause disruption,” said Donald Kohn, a former Fed vice chair. Deciding against raising rates would “signal that they don’t have confidence in their financial stability tools.”
Jan Hatzius, chief economist at Goldman Sachs, disagreed. It would have been better for the Fed to move cautiously given the highly uncertain environment that resulted from the banking stress, he said. “If more issues crop up after Wednesday, that’s also not going to be very confidence inspiring,” he said.
Fed officials have tried to signal their interest-rate moves deliberately over the past year to avoid the kind of market turmoil set off in 1994, when the Fed doubled its short-term benchmark rate from 3% to 6% in a 12-month span.
That rapid tightening hammered stocks and bonds and indirectly contributed to the demise of Kidder Peabody & Co., the bankruptcy of Orange County, Calif., and Mexico’s peso devaluation, which required a bailout from the U.S. and the International Monetary Fund.
After skipping on a rate increase in December 1994, as the peso crisis intensified, the Fed made a final rate increase in early 1995.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion

The PG rating has become the king of the box office. The entertainment business now relies on kids dragging their parents to theatres.

Rugged coastal drives and fireside drams define a slow, indulgent journey through Scotland’s far north.