The Office Market Had It Hard in 2023. Next Year Looks Worse.
Office building owners are losing hope that occupancy rates will rebound soon

 4 min
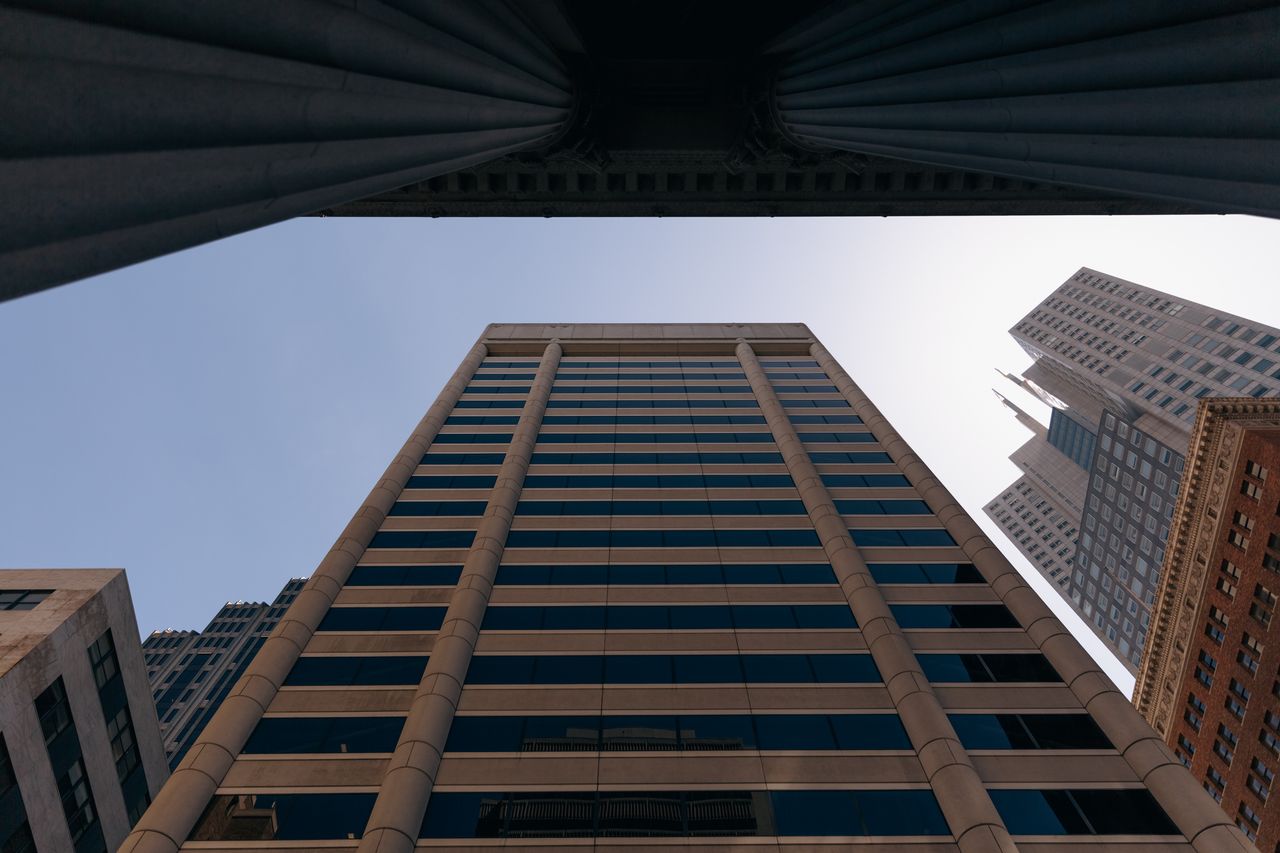
Office building owners, hammered by falling demand and high interest rates, struggled in 2023. But they mostly managed to stay afloat.
That is going to be a lot harder to do next year.
Many landlords have been able to extend their loans, often by putting in more capital. But a lot of those extensions are now expiring, and owners are losing hope that occupancy rates will rebound soon.
That means many more office landlords will be compelled to pay off their mortgages, sell their properties at a steep discount or hand their buildings over to their creditors.
“In 2024, it’s game time,” said Scott Rechler, chief executive of RXR Realty, a major owner of office buildings in the New York region. “Owners and lenders are going to have to come to terms as to where values are, where debt needs to be and right-sizing capital structures for these buildings to be successful.”
Office demand shows no sign of returning to pre pandemic levels. While the number of full-time remote employees has dwindled, hybrid workplace policies look here to stay. In the fourth quarter, 62% of U.S. businesses allowed employees to work from home some days of the week, up from 51% in the first quarter, according to Scoop Technologies.
Return-to-office rates also stalled for most of 2023. Kastle Systems, which tracks security-card swipes in 10 major U.S. cities, said that average office attendance is about half of its pre pandemic level. Placer.ai, which tracks mobile phone data, puts it in the 60% to 65% range. But it also said the return rate has topped out.
The office market has shown “some monthly fluctuations but little real change in the overall trajectory,” Placer.ai said in a November report.
The U.S. office vacancy rate stands at a record 13.6%, up from 9.4% at the end of 2019, according to data firm CoStar Group. The firm is forecasting it will rise to 15.7% by the end of 2024 and will peak above 17% by the end of 2026.
That vacancy rate is poised to push higher because nearly half of office leases signed before the pandemic haven’t expired, CoStar said. When they do, many of the businesses will likely take less space than they are currently occupying, whether they are renewing or relocating.
Take the case of Chicago law firm Neal Gerber Eisenberg, which signed one of the city’s largest 2023 office leases earlier this fall. The firm, which has grown steadily throughout the pandemic, adopted a policy that requires employees to work from the office at least eight days a month. Neal Gerber leased 90,000 square feet at its new location, down from the 113,000 square feet it will be giving up.
Beyond the longer-term decline in demand, office landlords are still contending with high interest rates. Landlords that have to refinance debt borrowed when rates were at historic lows will face much higher borrowing costs as high vacancy is putting rents and incomes under pressure.
In recent weeks, inflation has been declining and the Federal Reserve is likely to ease interest rates in 2024. That will soften the blow. But landlords still face a financial squeeze, analysts say.
“If you have a mortgage that’s expiring at 3% or 4%, there’s no way you’re refinancing at 3% or 4%,” said Steve Sakwa, an analyst with Evercore ISI. Even though rates have come down, he added, property owners are still looking at rates that could be double their expiring rates to refinance.
Not all the signals are bleak for the office market in 2024. Demand is still strong for the highest quality and best-located space in many markets from tenants willing to pay high rents to encourage employees to return to offices.
Developers have retreated from new construction in the sector, so there’s little competition from new supply. The 30 million square feet in office construction starts in 2023 was the lowest amount since 2010, according to CoStar.
Cities such as San Francisco, New York and Boston are lowering costs and streamlining the process for converting obsolete office buildings into apartments. While this isn’t expected to result in a big decline in vacancy, the actions might bring more activity to business districts, giving a psychological boost to downtown landlords and businesses.
But the steadily rising number of owners who are defaulting on their mortgages because of falling rent rolls looms over the market. The delinquency rate of bank loans and loans converted into commercial mortgage-backed securities currently is over 6% compared with below 1% before the pandemic hit, according to data firm Trepp.
High delinquencies combined with the dismal office outlook already have convinced some owners to hand properties back to lenders or sell for sharply discounted prices.
In Stamford, Conn., the owner of One Stamford Forum, a 500,000-square-foot building whose tenants include troubled Purdue Pharma, this fall gave the building back to its creditors, according to Trepp. In San Francisco, buyers have purchased office buildings like 60 Spear Street and 350 California Street for fractions of what they were worth before the pandemic.
Trepp is projecting that the office delinquency rate could be over 8% by the second half of next year. As more landlords default, the new owners that replace them—buying in at greatly reduced prices—will likely put more pressure on the market because they’ll be able to charge lower rents and still make a profit.
“What could be catastrophic is if you start seeing corporate profit pressures leading to continued or accelerated pace of office downsizing,” said Stephen Buschbom, Trepp’s research director.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min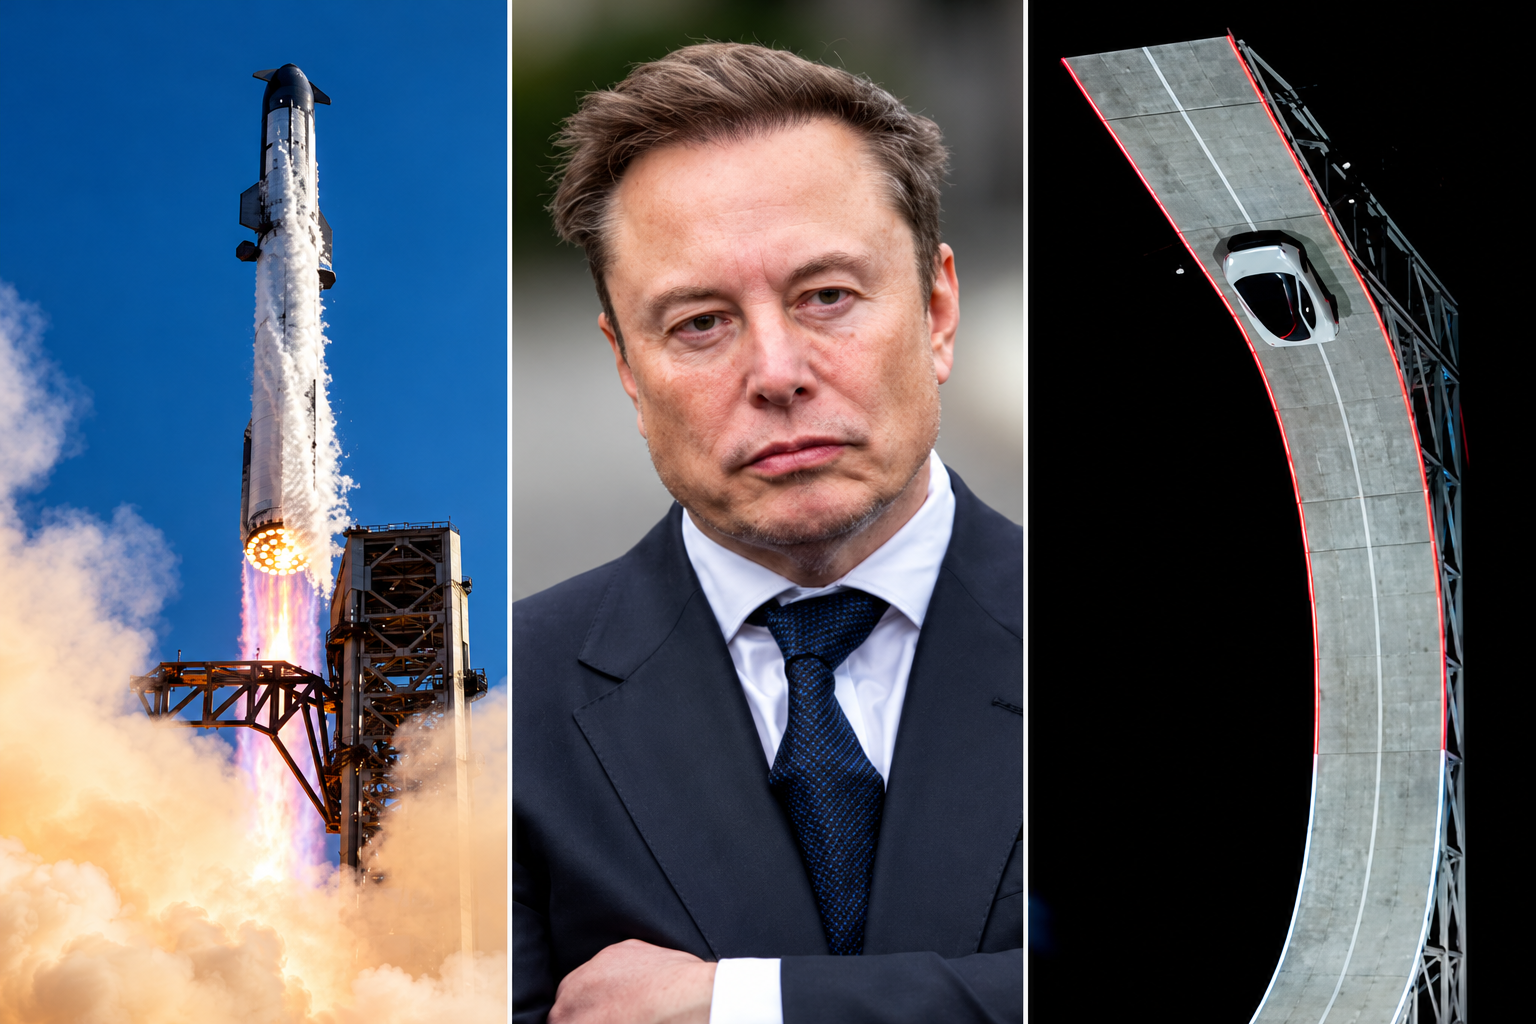
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.
Victorian auction buyers will soon receive a piece of information that has traditionally been withheld until bidding reaches it: the vendor’s reserve price. Under new property-sale and underquoting laws, agents must publish the agreed reserve at least seven days before an auction or fixed-date sale. Most changes begin on 1 October 2026 and apply to …
Continue reading “Victoria’s New Auction Rules Will Force Reserve Prices Into the Open”
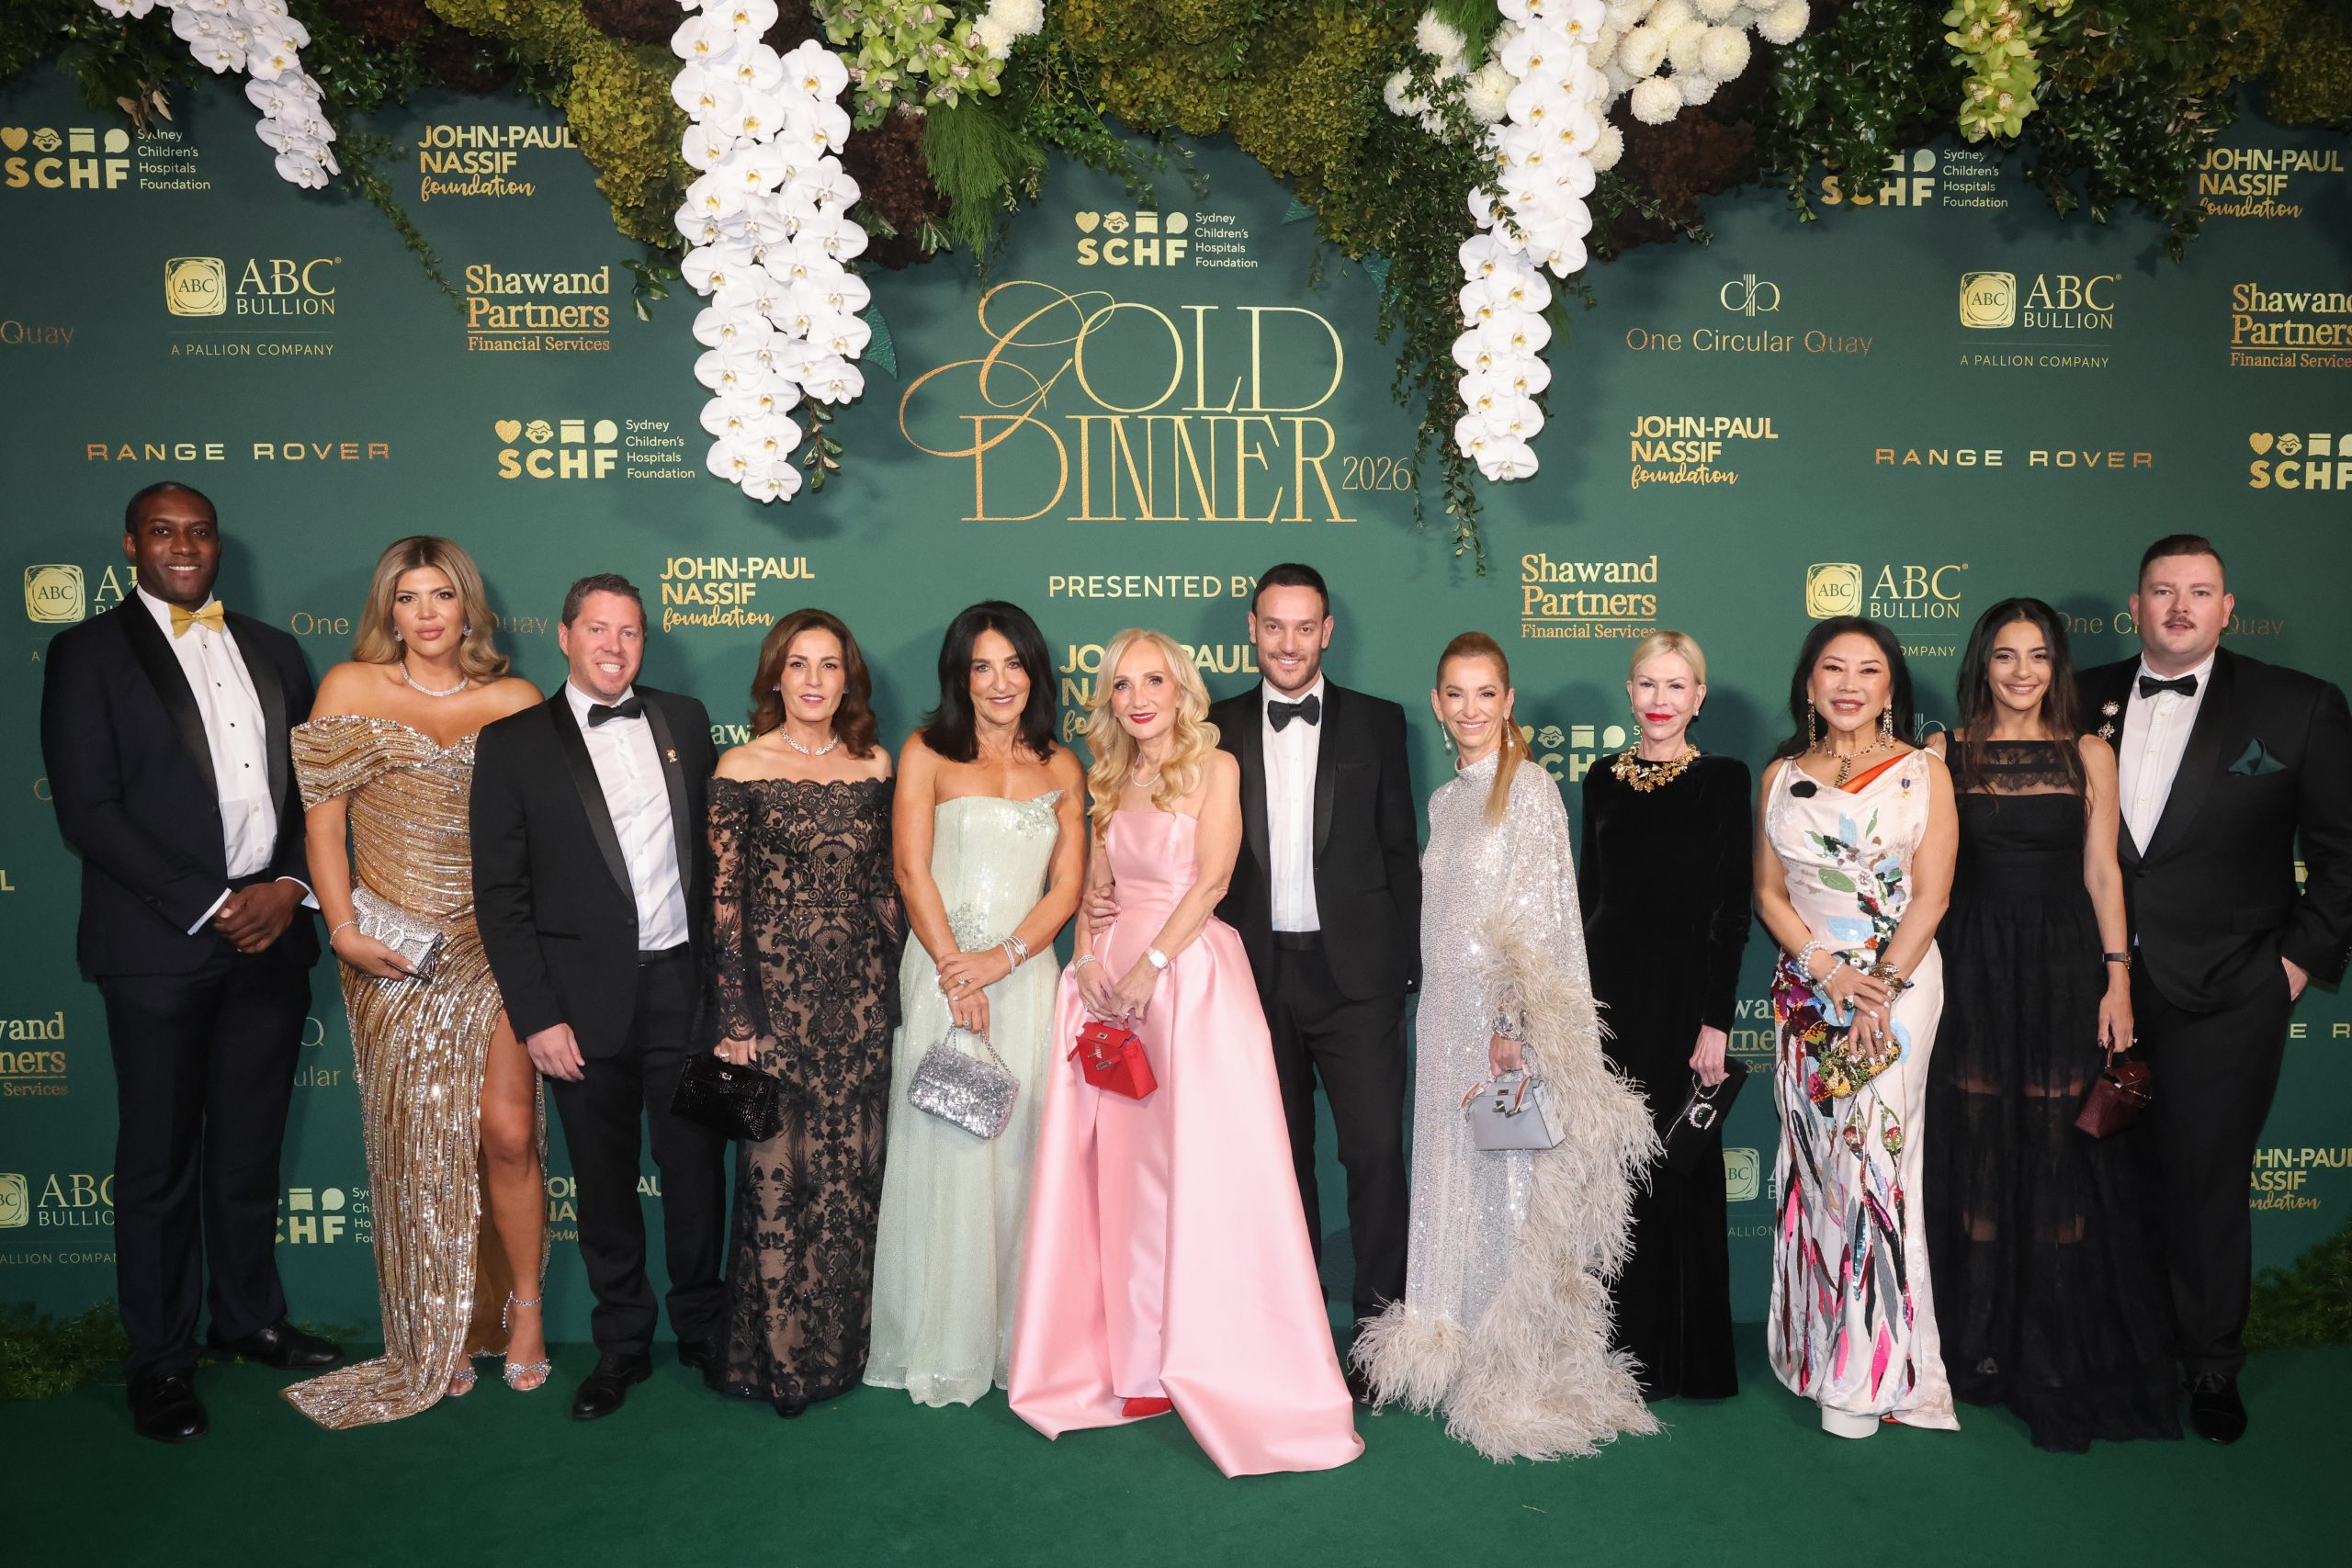
Sydney Children’s Hospitals Foundation CEO Kristina Keneally says Australia’s culture of large-scale philanthropy is becoming more sophisticated as Gold Dinner raises $75.5 million for children’s health, research and innovation.