World’s Major Economies Fall Behind U.S.

 2 min
Economies in the U.K. and Japan shrank at the end of last year, underlining the widening gulf between robust growth in the U.S. and more anemic conditions in the rest of the world.
The decline in activity in Japan came as a surprise to economists and meant that it has slipped in the global rankings of the world’s largest economies behind Germany and into fourth place.
In the U.K., the economy shrank for the second consecutive quarter, the shorthand definition of a recession. The U.K.’s statistics agency Thursday said gross domestic product fell at an annualized rate of 1.4% in the final three months of 2023, compared with a 3.3% increase in the U.S. over the same period.
U.K. consumer spending, the main driver of the U.K. economy, fell over the second half of 2023 even as wage growth outpaced inflation for the first time in two years, boosting consumers’ purchasing power. Japanese consumers, who are still seeing prices rise faster than wages, also cut their spending in the final quarter.
The growth numbers from the U.K. and Japan mirror similarly weak conditions in much of continental Europe and China .
The divergence between the U.S. and the rest of the rich world is in large part a story of surprising U.S. strength . The U.S. grew much faster than economists had expected it would at the start of 2023, while Europe was badly hit by high energy prices from the Ukraine war and rising interest rates. Economists forecast the growth gap will narrow somewhat over the course of the year, but remain wide.
U.S. consumer spending has been more resilient in the face of rising interest rates than in other parts of the world. Government spending in the U.S. has also remained at historically high levels for periods outside of recessions, giving the economy an added boost.
The Organization for Economic Cooperation and Development earlier this month said it expects the U.S. economy to grow by 2.1% this year, while it sees the U.K.’s economy growing by 0.7% and Germany’s economy by 0.3%.
To be sure, the declines in activity in Europe and Japan have been relatively modest and are a reflection of slow-growing economies that by nature fall into contraction more often than those that have a higher sustained level of growth.
And while economic output declined in a number of rich countries as 2023 drew to a close, job markets in Europe and Japan remained tight, as they were in the U.S. As a result, many economists hesitate to describe the U.K. and Japanese downturns as full-blown recessions.
Policymakers expect economies to pick up as inflation ebbs in the months ahead.
“We’re seeing some signs of a pickup,” Bank of England Gov. Andrew Bailey told lawmakers Wednesday.
Japan’s unemployment rate fell to an 11-month low in December, and the Bank of Japan ’s Tankan survey “showed that business conditions across all industries and firm sizes were the strongest they’ve been since 2018.”
Many economists expect the Bank of Japan to end its policy of negative short-term interest rates in either March or April, although the bank hasn’t confirmed that.
“We doubt that today’s GDP figures will prevent the Bank [of Japan] from ending negative interest rates in April,” said Marcel Thieliant , head of Asia-Pacific at Capital Economics.
The decline in its GDP during the second half of the year, and the yen’s weakness relative to the euro, meant that Japan dropped from third place in the global rankings of economic heft when measured in U.S. dollars.
Germany takes over the third-place spot behind the U.S. and China, despite Europe’s largest economy contracting during 2023. Japan lost its second-place spot to China in 2010 .
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
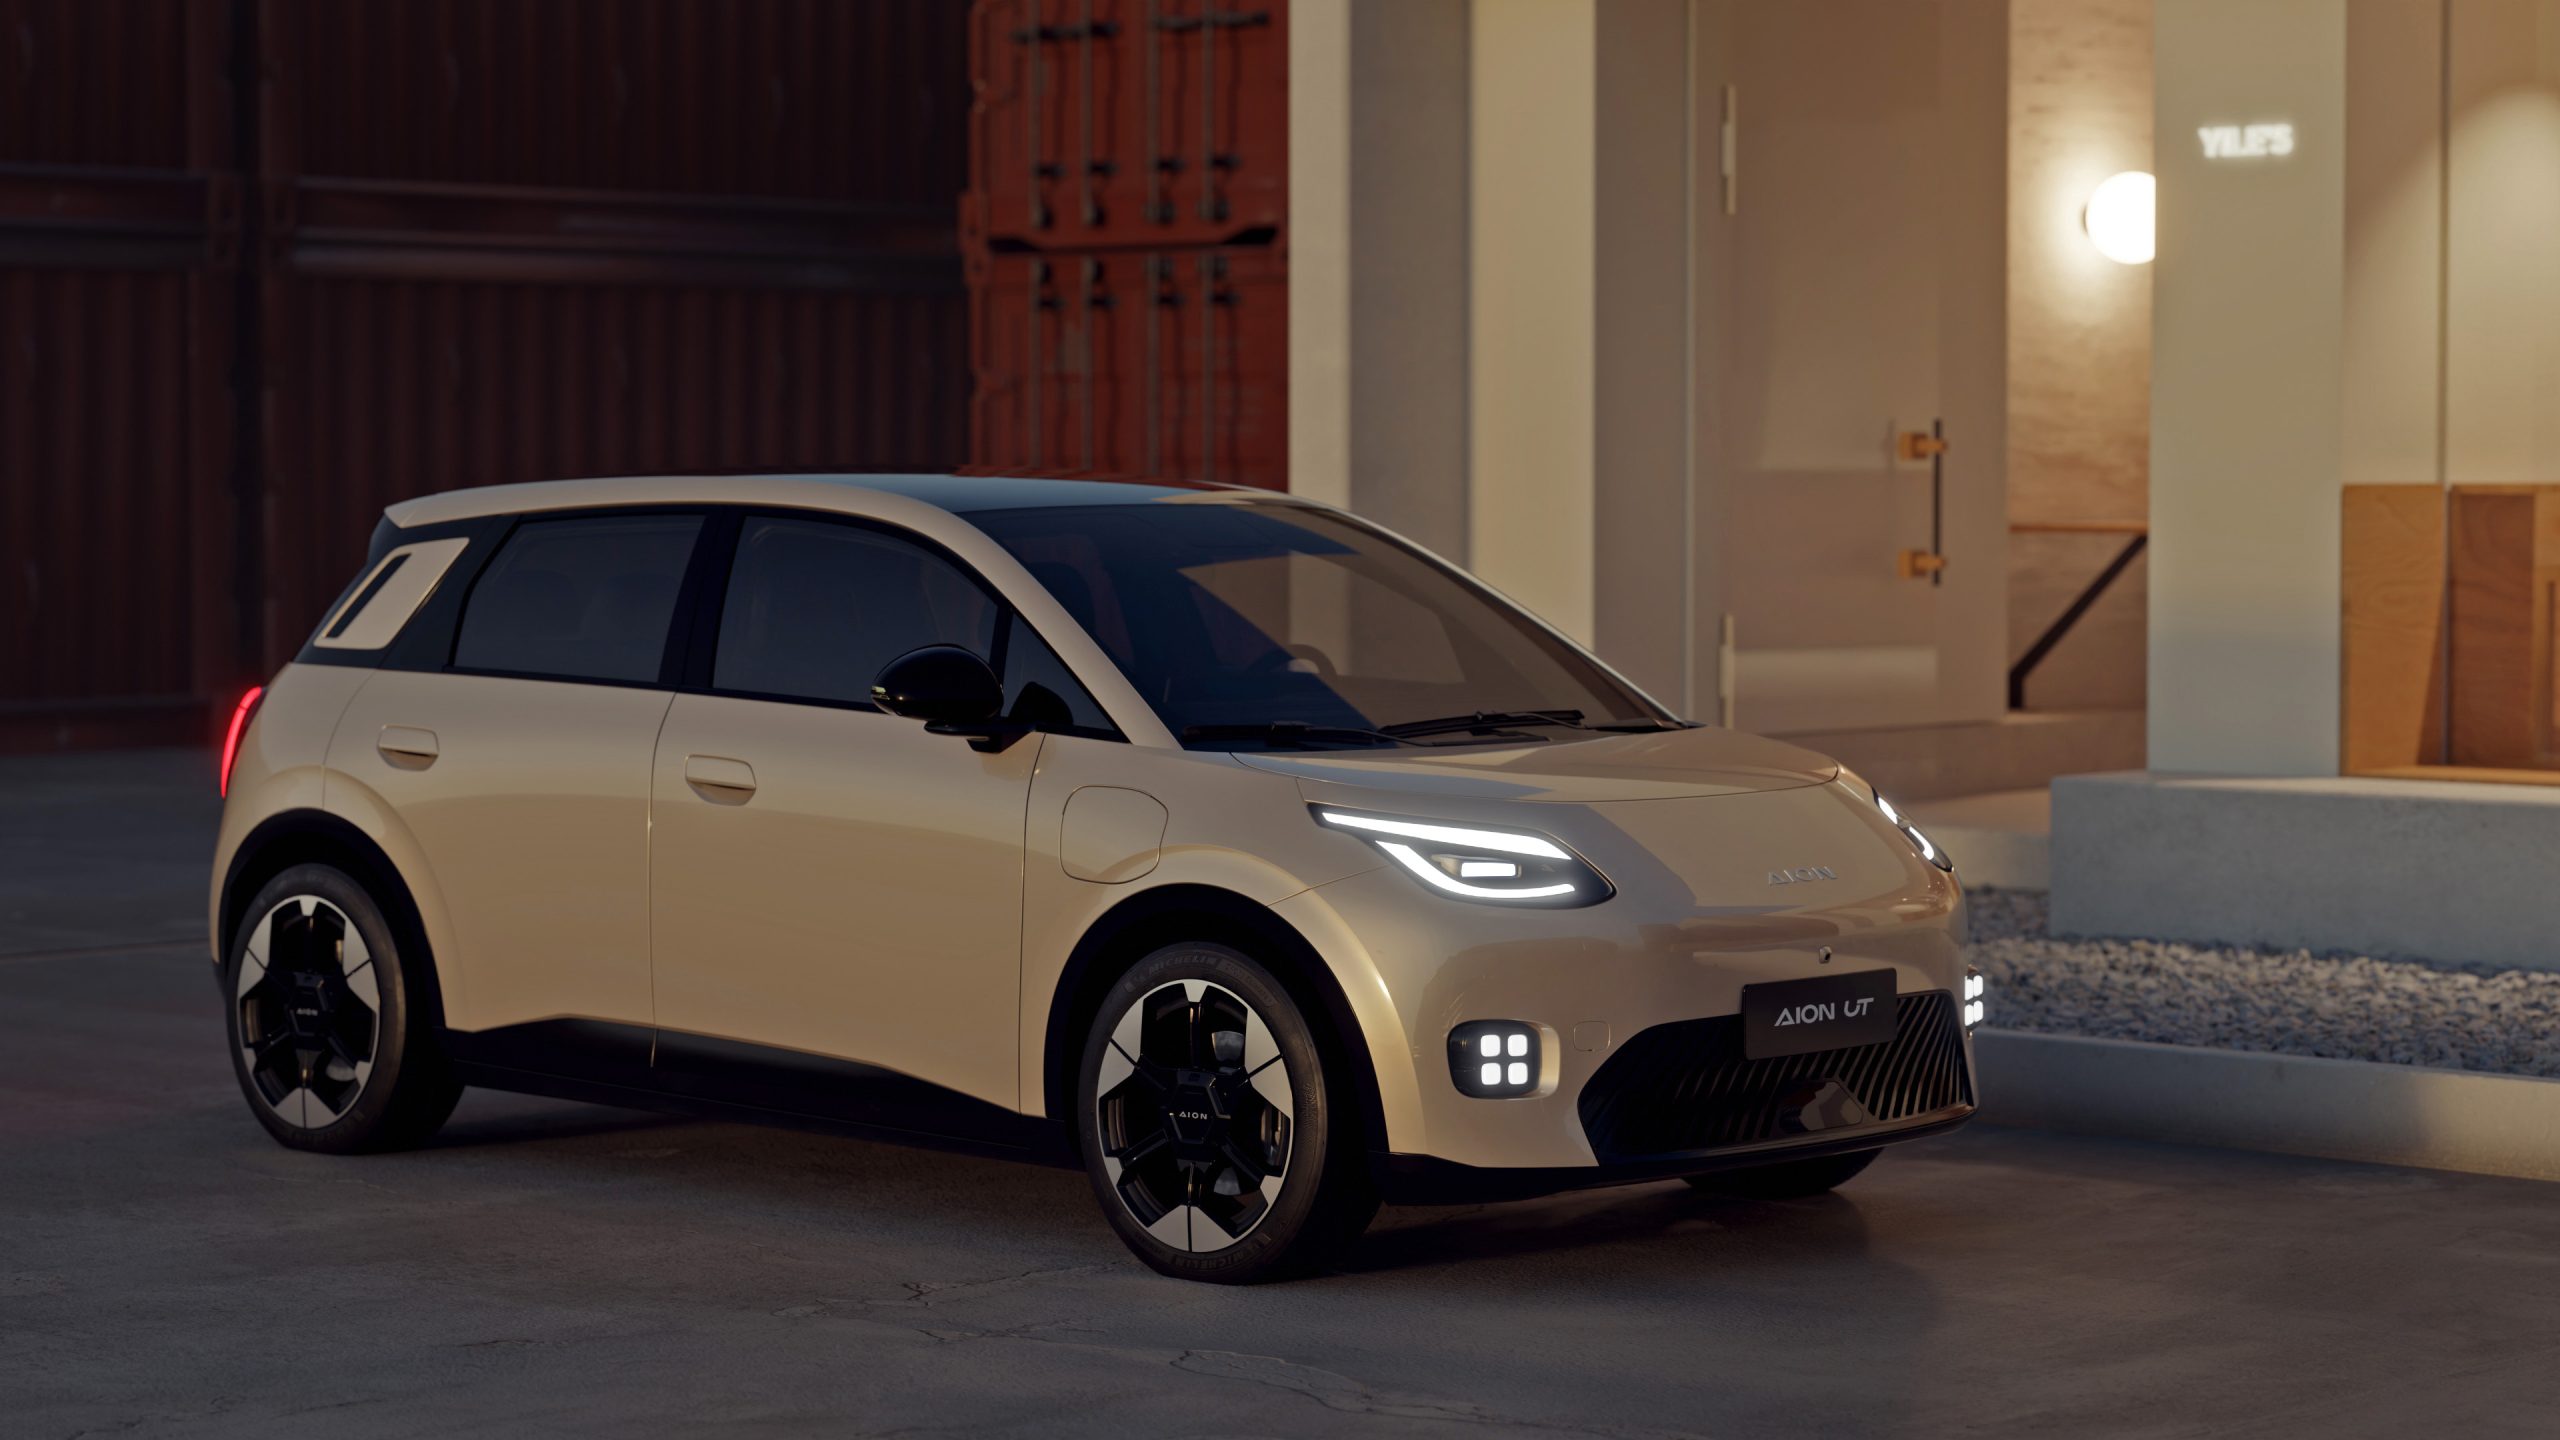
Chinese carmaker GAC will expand its Australian electric vehicle line-up with the city-focused AION UT hatchback.

From gorilla encounters in Uganda to a reimagined Okavango retreat, Abercrombie & Kent elevates its African journeys with two spectacular lodge transformations.