China’s Economy Shows Signs of Stabilizing—and a Slower Recovery

 2 min
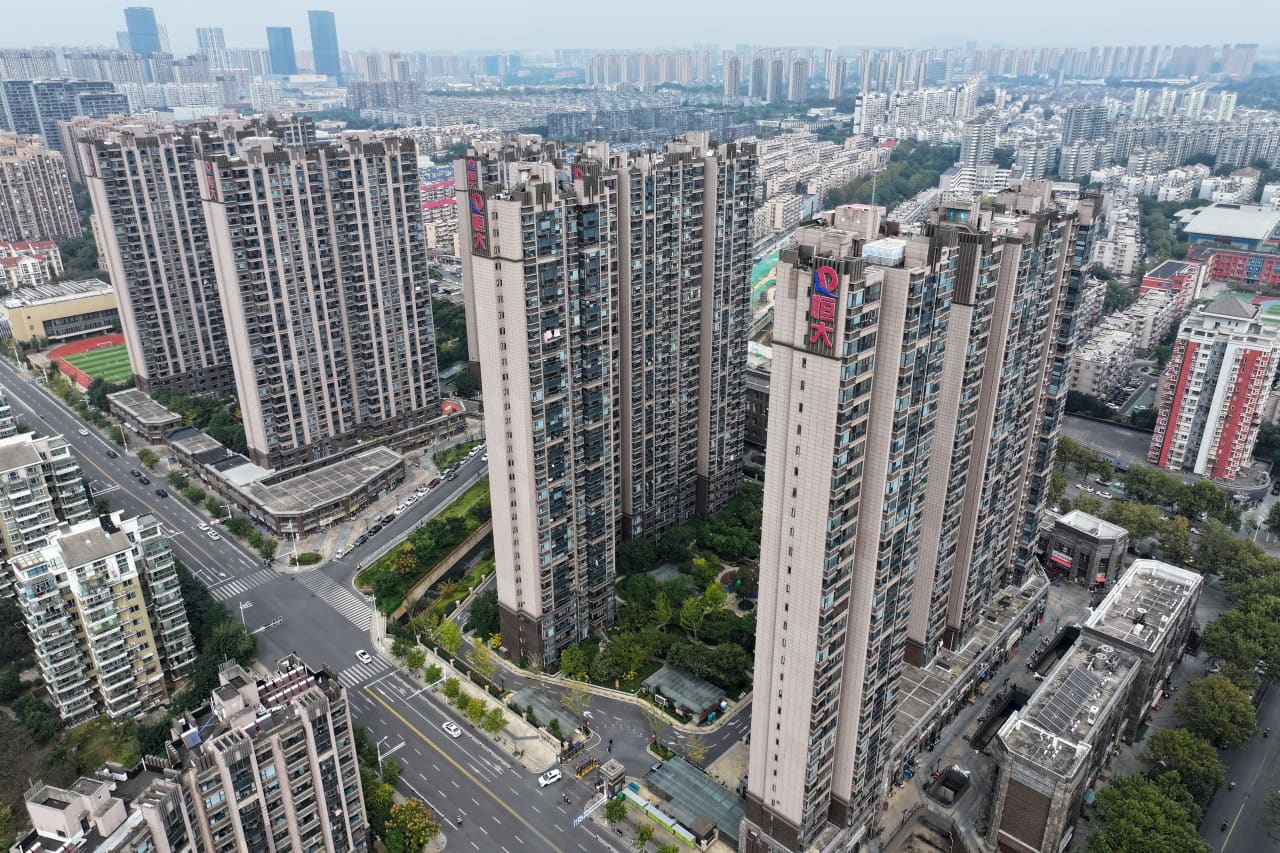
China’s economy is showing signs of stabilising but the improvements are decelerating. That could leave it in an L-shaped recovery—where the economy doesn’t see an upturn—that is unlikely to excite investors.
The iShares MSCI China ETF (ticker: MCHI) is down 11% so far this year. China’s recovery from three years of Covid restrictions has underwhelmed, there are concerns about the country’s longer term growth prospects, and geopolitical tensions loom.
While most analysts expect China to hit its 5% economic growth target, that may keep officials from bigger stimulus efforts, resulting in a recovery that is still anemic.
Indeed, a spate of October data from independent research firm China Beige Book show areas such as the property market still struggling to find a bottom, while there has been a slowdown in consumer spending.
Housing sales have softened in October from a month earlier and commercial real estate has had its worst showing this year. Both factory production and domestic orders also slowed.
Consumer spending is cooling, with households pulling back from big-ticket items including cars and appliances. They also are reducing their revenge spending on travel and dining out in recent months, according to China Beige Book.
Still, analysts are feeling more confident Beijing will do what is needed to create some stability, especially after it approved an additional $1 trillion renminbi government bond issuance to support infrastructure investment.
The debt will be issued not by local governments but by the sovereign, pushing headline deficit to 3.8% of GDP. It is a surprise move indicating political will to put a floor under economic activity, but also the latest signal of pain in the economy, says TS Lombard’s Rory Green in a note to clients.
Central authorities are trying to put a floor on equities, with reports Central Huijin Investment Limited—which is a part of the sovereign-wealth fund—bought exchange-traded funds. And authorities are trying to limit weakness in the yuan as part of stimulus efforts, he adds.
The next guideposts are a Politburo meeting in November and a Central Economic Work Conference in December that could offer clues to next year’s growth and fiscal outlook.
Green expects more emphasis on reallocating resources to technology sectors aligned with Beijing’s efforts to become more self-reliant, and a possible plan on how officials resolve local government debt burden.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
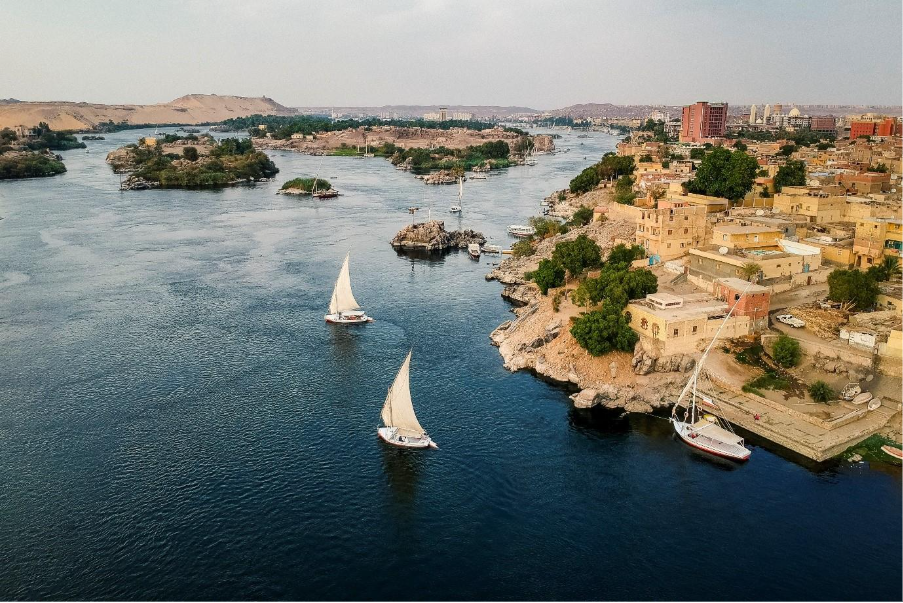
A resurgence in high-end travel to Egypt is being driven by museum openings, private river journeys and renewed long-term investment along the Nile.
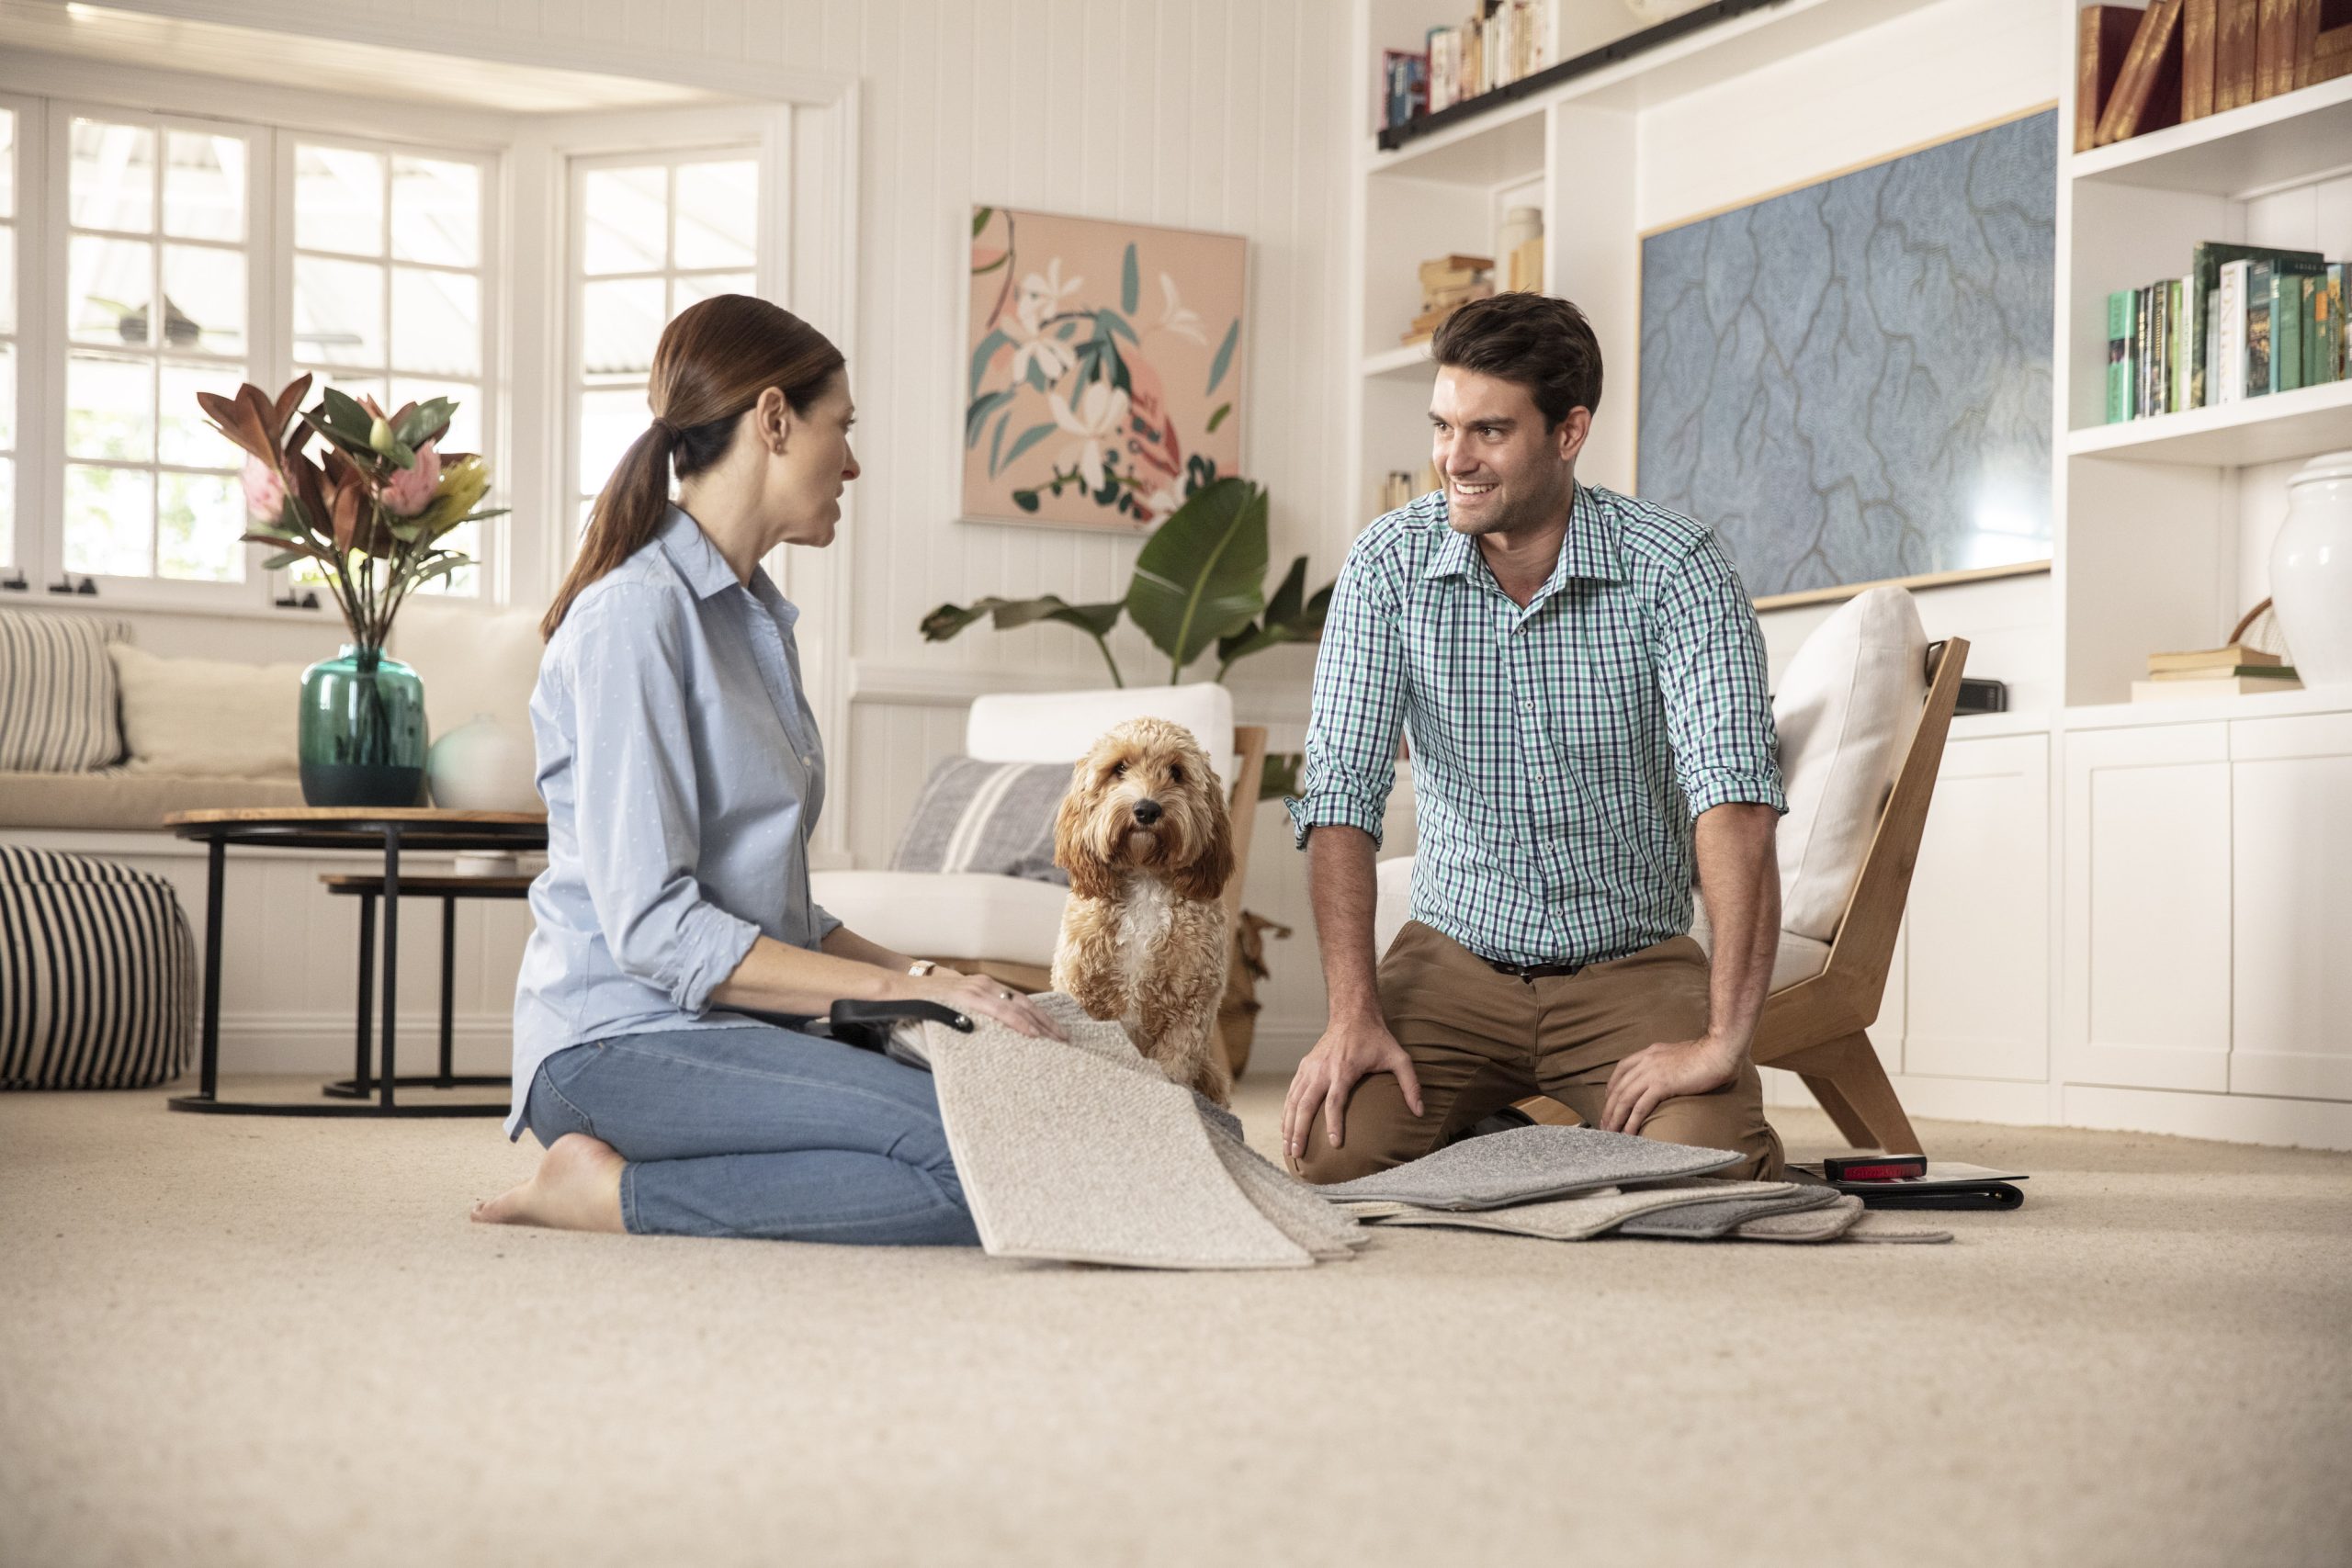
High-end homeowners are choosing to upgrade rather than relocate, investing in bespoke design, premium finishes and long-term lifestyle value.