Profiting From the Pet Boom

 4 min

Humans may not be acquiring pets at a pandemic-induced pace anymore, but they still are spending plenty on food, supplies, and services to take care of the furry members of their families.
Investors in public and private markets have their eyes on all that pet-care spending. Increasingly, consumers have gone beyond buying kibble to snapping up premium products and services that ensure their pets are living healthy, environmentally friendly lives. It’s a trend familiar to anyone who has followed the growth in eco-friendly wellness products and services for humans.
The shorthand for this phenomenon? The “humanisation of pets,” according to Milwaukee-based Baird.
“What that meant 10 years ago was you started to see the premiumisation of the quality of the diets and the emergence of grain-free brands and premium, cleaner-labeled food brands,” says Spencer DePree, a director in Baird’s global consumer and retail group. “That certainly is true today, but you’re starting to see that expand into other parts of the lifestyle of the pet.”
The entire pet economy is valued at about US$130 billion to US$140 billion, divided into four main categories: nutrition, products and supplies, healthcare, and services, according to Baird. Nutrition products snag most consumer dollars, but the so-called humanisation trend touches all of them.
Australia, Canada, and parts of Europe are leading the pet-market conversion to “non-traditional, more premium food and nutrition,” says Scott Ehlen, a director in Baird’s global consumer investment banking group. For the U.S., it’s a question of “how quickly, not if,” the trend will take hold, Ehlen says.
Penta spoke with DePree and Ehlen about what’s driving the growth in pet-related purchases and some of the companies on their radar screen.
Proactive vs. Reactive
One reason for the uptick in purchases of healthier pet products is consumers have realised they can proactively keep their pets happy and free from illness. The simplest step is to provide them with a diet that won’t lead to health problems in future years, and, as with humans, mix in nutritional supplements and treats with health benefits, such as dental care.
“That’s something you’ve seen in human wellness over the last five to seven years,” DePree says.
In pet food, that’s led companies to go beyond making grain-free kibble to producing fresh foods and to offering “toppers,” such as fish oils or freeze-dried raw meat. Companies are even developing foods that don’t rely on traditional beef and poultry proteins, such as Berkeley, Calif.-based Jiminy’s insect-based pet foods—a company backed by venture capital, according to private-markets data company PitchBook.
“Their value proposition is pretty impressive when you just look at the energy consumption that goes into producing a pound of beef,” DePree says.
As people spent more time at home with their pets during the pandemic, they also realized their furry companions have a lot of downtime. Humans that have returned to the office want to make sure their pets stay happy and active, so many are putting their dogs in daycare facilities with cameras that allow them to check in to see how their pup is doing.
“It’s not a kennel, it’s doggy daycare, where it’s analogous to taking your child to daycare,” Ehlen says.
There are a handful of franchisors backed by private equity in this sector including Dogtopia, which Ehlen says is one of the larger companies with at least 200 franchisees and more in the pipeline. An investment vehicle formed by the New York-based private-equity firm Red Barn Equity Partners with funding from institutions and family offices made a major investment in 2020 in the company, which offers daycare, boarding, and spa facilities, according to a news release.
Pet grooming is another area that’s prime for investment. Ehlen says he takes his own dog to a groomer who keeps track of appointments on a paper calendar. “It’s impossible to get a hold of her, impossible to schedule,” he says.
“A vast majority of the market continues to exist in that state in 2023,” Ehlen says. “You’re finally starting to see folks realise that this is a huge market, it’s a non-discretionary market, it’s going to be around forever. It’s just in desperate need of investment, of capital, of innovation.”
The ‘Pet’ Play in Food
The importance of pets to the economy is evident within the four major consumer products companies—Mars, Nestlé, Post Holdings, and General Mills. All include pet foods among their brands; Post, in fact, made a push into the business in February by purchasing Nature’s Way and Rachael Ray Nutrish, among other more standard pet food brands, from J.M. Smucker Co. for $1.2 billion.
For an investor interested in the growth of premium natural pet food, the only pure public-market play is Freshpet, based in Secaucus, N.J., DePree says.
While bigger companies have grabbed more market share, independent, private companies are “still the birthplace of new brands, new innovation, and that could be coming from either new companies or new product lines,” he says. “When the category validates itself or the scale hits, then you may see one of the bigger players jump in through an acquisition.”
Independent companies in the natural pet food space include the Farmer’s Dog, based in New York, which is backed by venture capital, according to Pitchbook. Denver-based Alphia, a pet food co-manufacturer that supplies other companies, was bought late last month by PAI Partners, a private-equity firm, from another PE firm, J.H. Whitney, according to a news release.
In March, the specialty pet food brand Natural Balance, announced it would merge with Canidae, which makes premium sustainable pet food, a news release said.
Before the stock market became more volatile last year, there was a “big queue of folks circling the wagons,” DePree says. Considering that the large consumer products companies are still trying to figure out how to grow this market, “over the next 18, 24 months, you’ll see some more stories become public.” For now, he says, “the demand for ways to play ‘pet’ outstrips the supply.”
The Internet-of-Things for Dogs
Pets aren’t exempt from humans’ obsession with tech, either. The latest pet-tech trends range from fitness trackers to food-monitoring devices that not only monitor how much and when your pet is eating, but also automatically order more food when you’re running low, DePree says.
Old-tech—such as electronic fences that keep dogs confined to a designated space—are being replaced by devices considered more humane and able to collect data on a pet’s behaviour, Ehlen says.
An example is Halo Collar, which uses wireless GPS and allows owners to set up zones to contain their pets wherever they are. The company, based in Woodcliff, N.J., and co-founded by dog psychologist Cesar Millan and tech innovator Ken Ehrman, was backed in May by Utah-based Decathlon Capital Partners, which provides revenue-based financing.
Most innovations in the pet economy so far have focused on dogs, but Ehlen and DePree say companies also have their sights on improving the lives of cats.
“If anyone is doing any innovation in cat, it’s alongside dog, but now you’re starting to see a more purpose-driven and specific sort of focus on the category,” DePress says. But he chides, “cats might be insulted at the humanisation concept—they probably hold themselves in a higher place.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
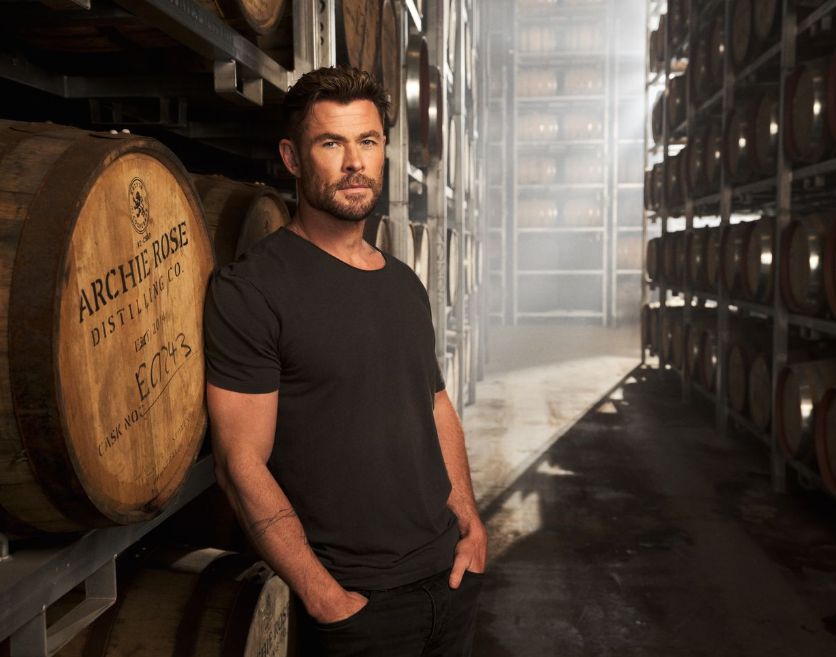
Australian actor Chris Hemsworth has joined Archie Rose Distilling Co. as co-owner and strategic business partner as the Sydney spirits company prepares to enter the United States. The partnership brings Hemsworth together with Archie Rose founder Will Edwards, with the pair aiming to build greater international recognition for Australian whisky. Founded in Sydney in 2014, …
Continue reading “Chris Hemsworth Joins Archie Rose as Co-Owner Ahead of Global Expansion”

Paine Schwartz joins BERO as a new investor as the year-old company seeks to triple sales.