RBA lifts rates to 4.60% as inflation risks become reality
Inflation risks are materialising, prompting the RBA’s fourth rate increase of 2026. Here’s what changed and what Michele Bullock said
 5 min
The Reserve Bank of Australia has delivered its fourth interest-rate increase of 2026, lifting the cash-rate target by 25 basis points to 4.60 per cent and warning that further tightening remains possible.
The unanimous decision on 29 September takes the cash rate to its highest level in almost 15 years. More importantly, it confirms that the RBA’s concern has shifted from inflation risks that might materialise to price pressures that are already spreading through the economy.
The increase was widely expected after a series of hawkish comments from senior RBA officials. Financial-market sentiment now remains tilted towards rates staying higher for longer, with some analysts expecting at least one further increase. Yet the decision is not straightforwardly hawkish: the economy is slowing, house prices are falling and household budgets are under mounting pressure. The RBA is tightening because inflation has proved stronger than anticipated, not because the economy is booming.
A significant change in the statement
The clearest change from the RBA’s August statement is the transition from warning about upside risks to declaring that those risks are “materialising”.
In August, the Board left the cash rate at 4.35 per cent to assess the effects of three earlier increases. It said inflation remained too high and acknowledged that the Middle East conflict, elevated energy costs, weak productivity and strong investment related to artificial intelligence could create further price pressure. However, those concerns were still framed principally as risks to the forecast.
The September statement is more definitive. Recent Australian inflation was stronger than the RBA expected, while output growth in the June quarter was also marginally stronger. Businesses consulted through the Bank’s liaison program reported that they were either raising prices or considering doing so. Short-term inflation expectations remained elevated.
The international picture has also deteriorated. The conflict in the Middle East has broadened, oil supplies have suffered further disruption and global energy prices are materially higher than the assumptions used in the RBA’s August forecasts. Higher fuel costs are now being passed through, at least partially, to the prices of other goods and services.
This distinction matters. Central banks generally try to look through a temporary increase in petrol prices because higher interest rates cannot produce more oil or end an overseas conflict. The RBA becomes more likely to act when the original price shock spreads into transport, manufacturing, retail prices, wages and inflation expectations. Its statement suggests that this second-round process has begun.
The RBA also introduced AI-related inflation more prominently into its reasoning. Rapid investment in artificial intelligence is supporting growth among Australia’s major trading partners but is also pushing up demand and prices for technology-related goods. The AI investment boom is therefore playing a double role: cushioning global growth from the Middle East shock while intensifying pressure on prices and scarce resources.
Domestic capacity remains the other half of the inflation story. Australia’s weak productivity growth continues to restrict how quickly the economy can expand without creating price pressure. Business investment and borrowing remain strong, while output has been slightly more resilient than expected. The RBA’s argument is that imported inflation has arrived while the domestic economy still has insufficient spare capacity to absorb it.
Nevertheless, the statement acknowledged considerably more weakness than was evident earlier in the year. Consumer spending is easing, labour-market conditions have softened, house prices have fallen in most capital cities and new housing lending has declined noticeably. The previous three increases appear to be slowing the economy.
That balance makes the decision unusually uncomfortable. The RBA is raising rates into a slowdown because it believes allowing inflation to persist would ultimately demand an even more severe response.
The statement’s final paragraphs also carry a stronger tightening bias than in August. Rather than merely saying rates could rise if required, the Board explicitly committed to doing what was necessary, “including increasing the cash rate target further if needed”. The fact that all nine members supported the increase reinforces the message that the Board saw a clear need to act. RBA monetary policy statement, 29 September 2026
What Bullock said after the decision
At her press conference, Governor Michele Bullock presented the increase as an insurance policy against inflation becoming entrenched rather than the beginning of a predetermined series of rises.
Bullock said the Board considered leaving the cash rate unchanged but ultimately concluded that inflation developments justified another increase. She stopped short of offering forward guidance about the next meeting, saying the RBA would need to observe how all four of this year’s rate increases flowed through the economy.
That caution is important. Monetary policy operates with a lag, so households and businesses have not yet felt the full effect of the earlier increases. Bullock pointed to mortgage payments consuming a growing share of disposable income and the housing downturn as evidence that policy was already restrictive. Whether it is restrictive enough, however, will be determined by subsequent inflation data.
Her core message was that the RBA cannot afford to let Australians become accustomed to inflation of 3 or 4 per cent. If businesses, workers and consumers begin treating that rate as normal, inflation expectations could become embedded in pricing and wage decisions. Reversing that psychology would require a much sharper economic contraction.
Bullock said a recession was not the RBA’s central forecast, but she conceded there were scenarios in which a dramatic slowdown could become necessary if inflation expectations escaped the Bank’s control. “I hope it’s not needed,” she said when asked whether the economy might have to enter recession. ABC News coverage of Bullock’s press conference
She also rejected the idea that the Middle East conflict was solely responsible for the rate increase. The energy shock has intensified the problem, but Australia already faced domestic capacity constraints and inflationary pressure. Interest rates cannot lower global oil prices, but they can weaken demand and make it harder for businesses to pass every cost increase through to customers.
Bullock acknowledged that this mechanism places a disproportionate burden on mortgage holders. She noted that some Australians were taking second jobs to manage higher living costs and debt repayments. Her defence of the decision was that failing to act would eventually produce higher inflation, higher rates and a worse economic outcome.
The mood is now “higher for longer”
Current sentiment is therefore distinctly cautious and hawkish. The September increase was expected, but the unanimous vote and explicit reference to further rises reduce the likelihood of near-term relief for borrowers. Bond-market pricing and some private-sector forecasts point to additional tightening, although the RBA itself has not committed to another move.
The central question is whether four increases—totalling one percentage point this year—will slow domestic demand quickly enough to offset persistent energy, technology and capacity pressures. Falling house prices, weaker lending and softer consumption suggest the policy is working. Stronger inflation and continuing price pass-through suggest it has not yet done enough.
For borrowers, the immediate conclusion is bleak: rate cuts are no longer part of the near-term conversation. The debate is now between holding at 4.60 per cent and raising the cash rate again.
The RBA hopes it can contain inflation without causing a recession. Its latest statement and Bullock’s comments show that it sees a greater danger in doing too little now—and being forced to inflict substantially more damage later.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
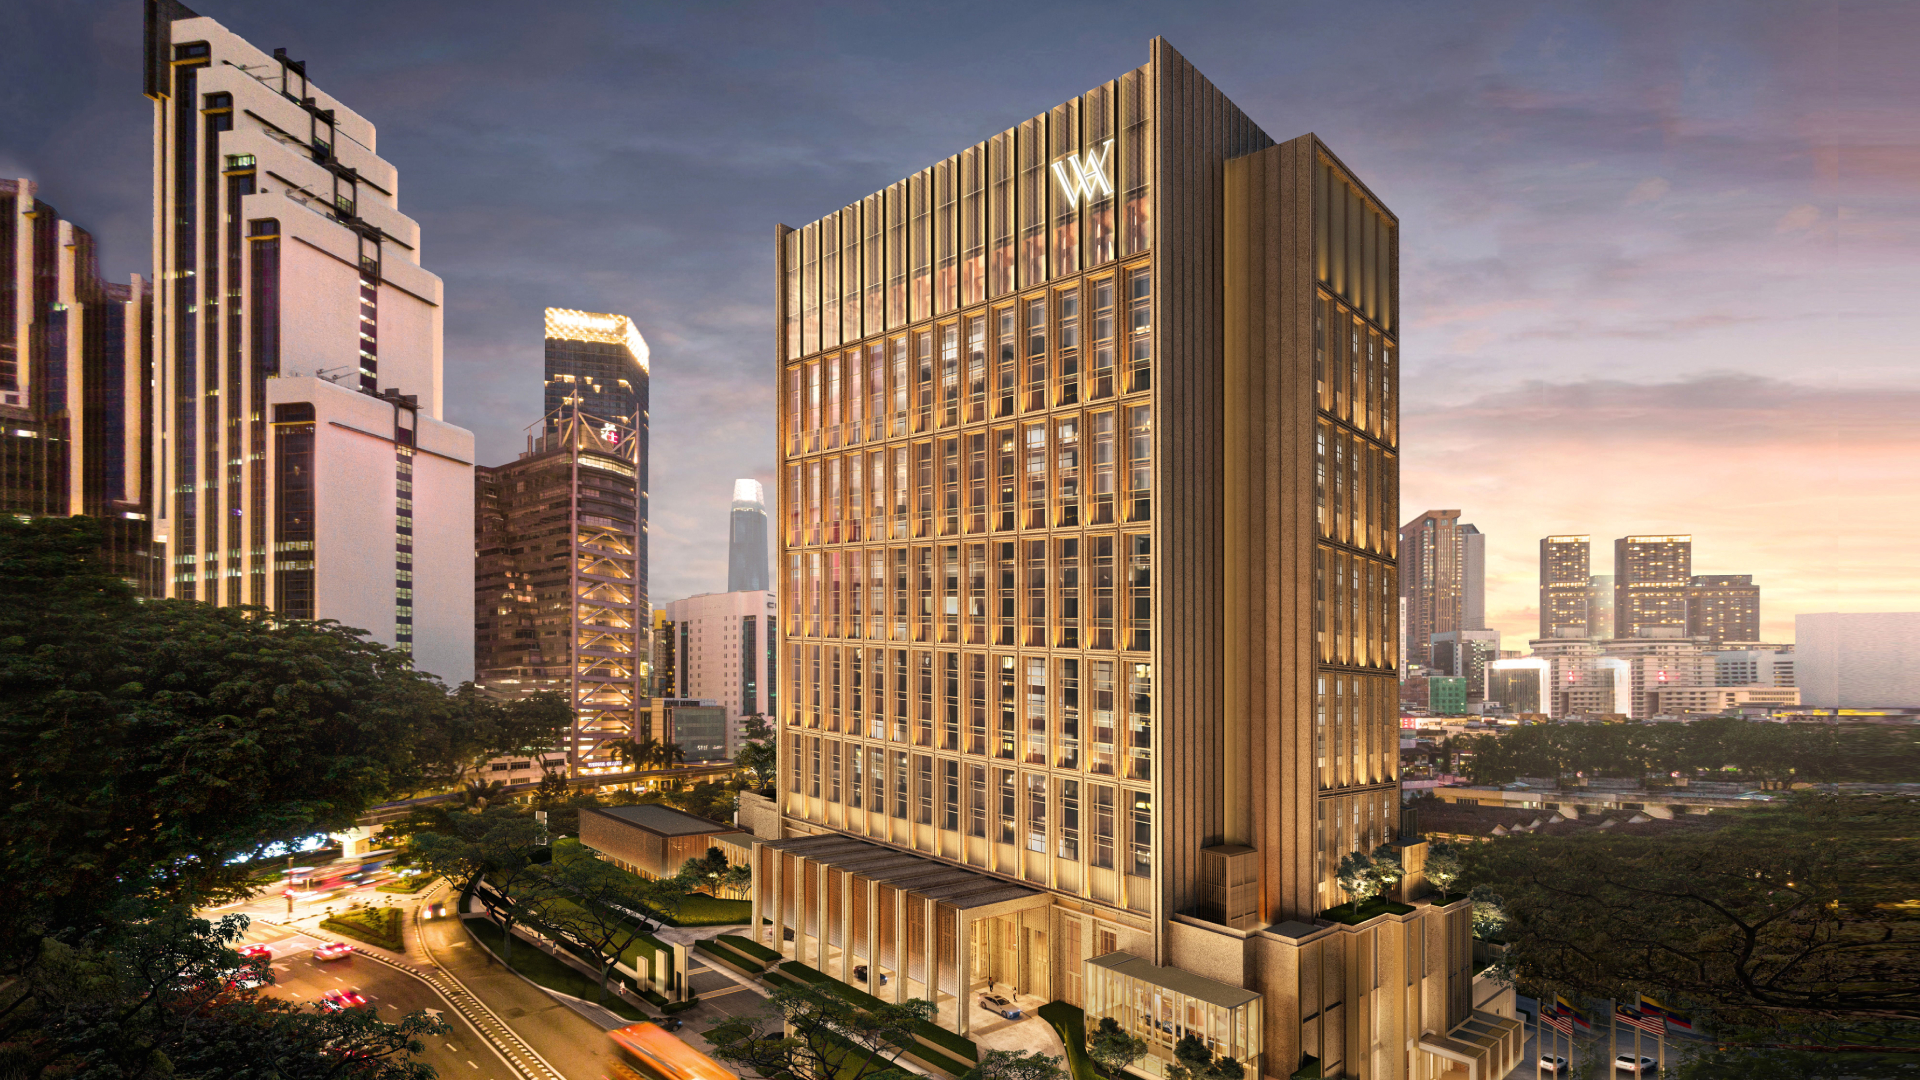
Waldorf Astoria Kuala Lumpur is scheduled to open on 30 October, introducing the Hilton luxury brand to Malaysia with an all-suite hotel in the city’s Golden Triangle.
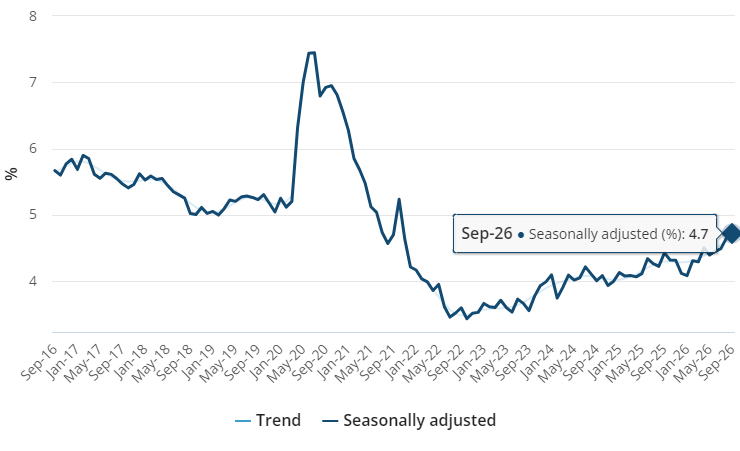
Employment fell by 39,300 and unemployment held at a revised 4.7 per cent, giving the RBA more room to pause in November.
2 min
Australia’s labour market weakened in September, reducing—but not eliminating—the case for another Reserve Bank rate rise in November.
The seasonally adjusted unemployment rate was 4.7 per cent, according to the Australian Bureau of Statistics. August was revised to the same level, while September employment fell by 39,300 people. The number of unemployed Australians increased by 8,900 to 732,000.
The weakness extended beyond the headline rate. The employment-to-population ratio fell 0.3 percentage points to 63.6 per cent, participation declined 0.2 points to 66.8 per cent and underemployment edged up to 6.3 per cent. Part-time employment fell by 73,700, partly offset by a 34,400 increase in full-time work.
For the RBA, this is a clearer sign that restrictive monetary policy is cooling demand. Higher unemployment and falling employment reduce wage pressure over time and increase the risk that another rate rise would push the economy harder than necessary.
That makes a November increase less certain. It does not make a hold inevitable. The RBA must balance labour-market softness against inflation, and the September-quarter consumer price index due later in October will carry more direct weight in the decision.
For mortgage holders and property investors, the practical conclusion is not to trade one data release. Borrowers should continue testing repayments at higher rates, preserve liquidity and avoid basing a purchase on an assumed near-term reversal. Refinancing decisions should be assessed against total cost, not simply the advertised rate.
Property markets may initially welcome a reduced probability of another increase because borrowing capacity and sentiment are highly rate-sensitive. But a weakening labour market is not unambiguously positive for housing: job security supports mortgage serviceability, rental demand and buyer confidence.
The September numbers have given the RBA a credible reason to wait. Inflation will determine whether it can use it.
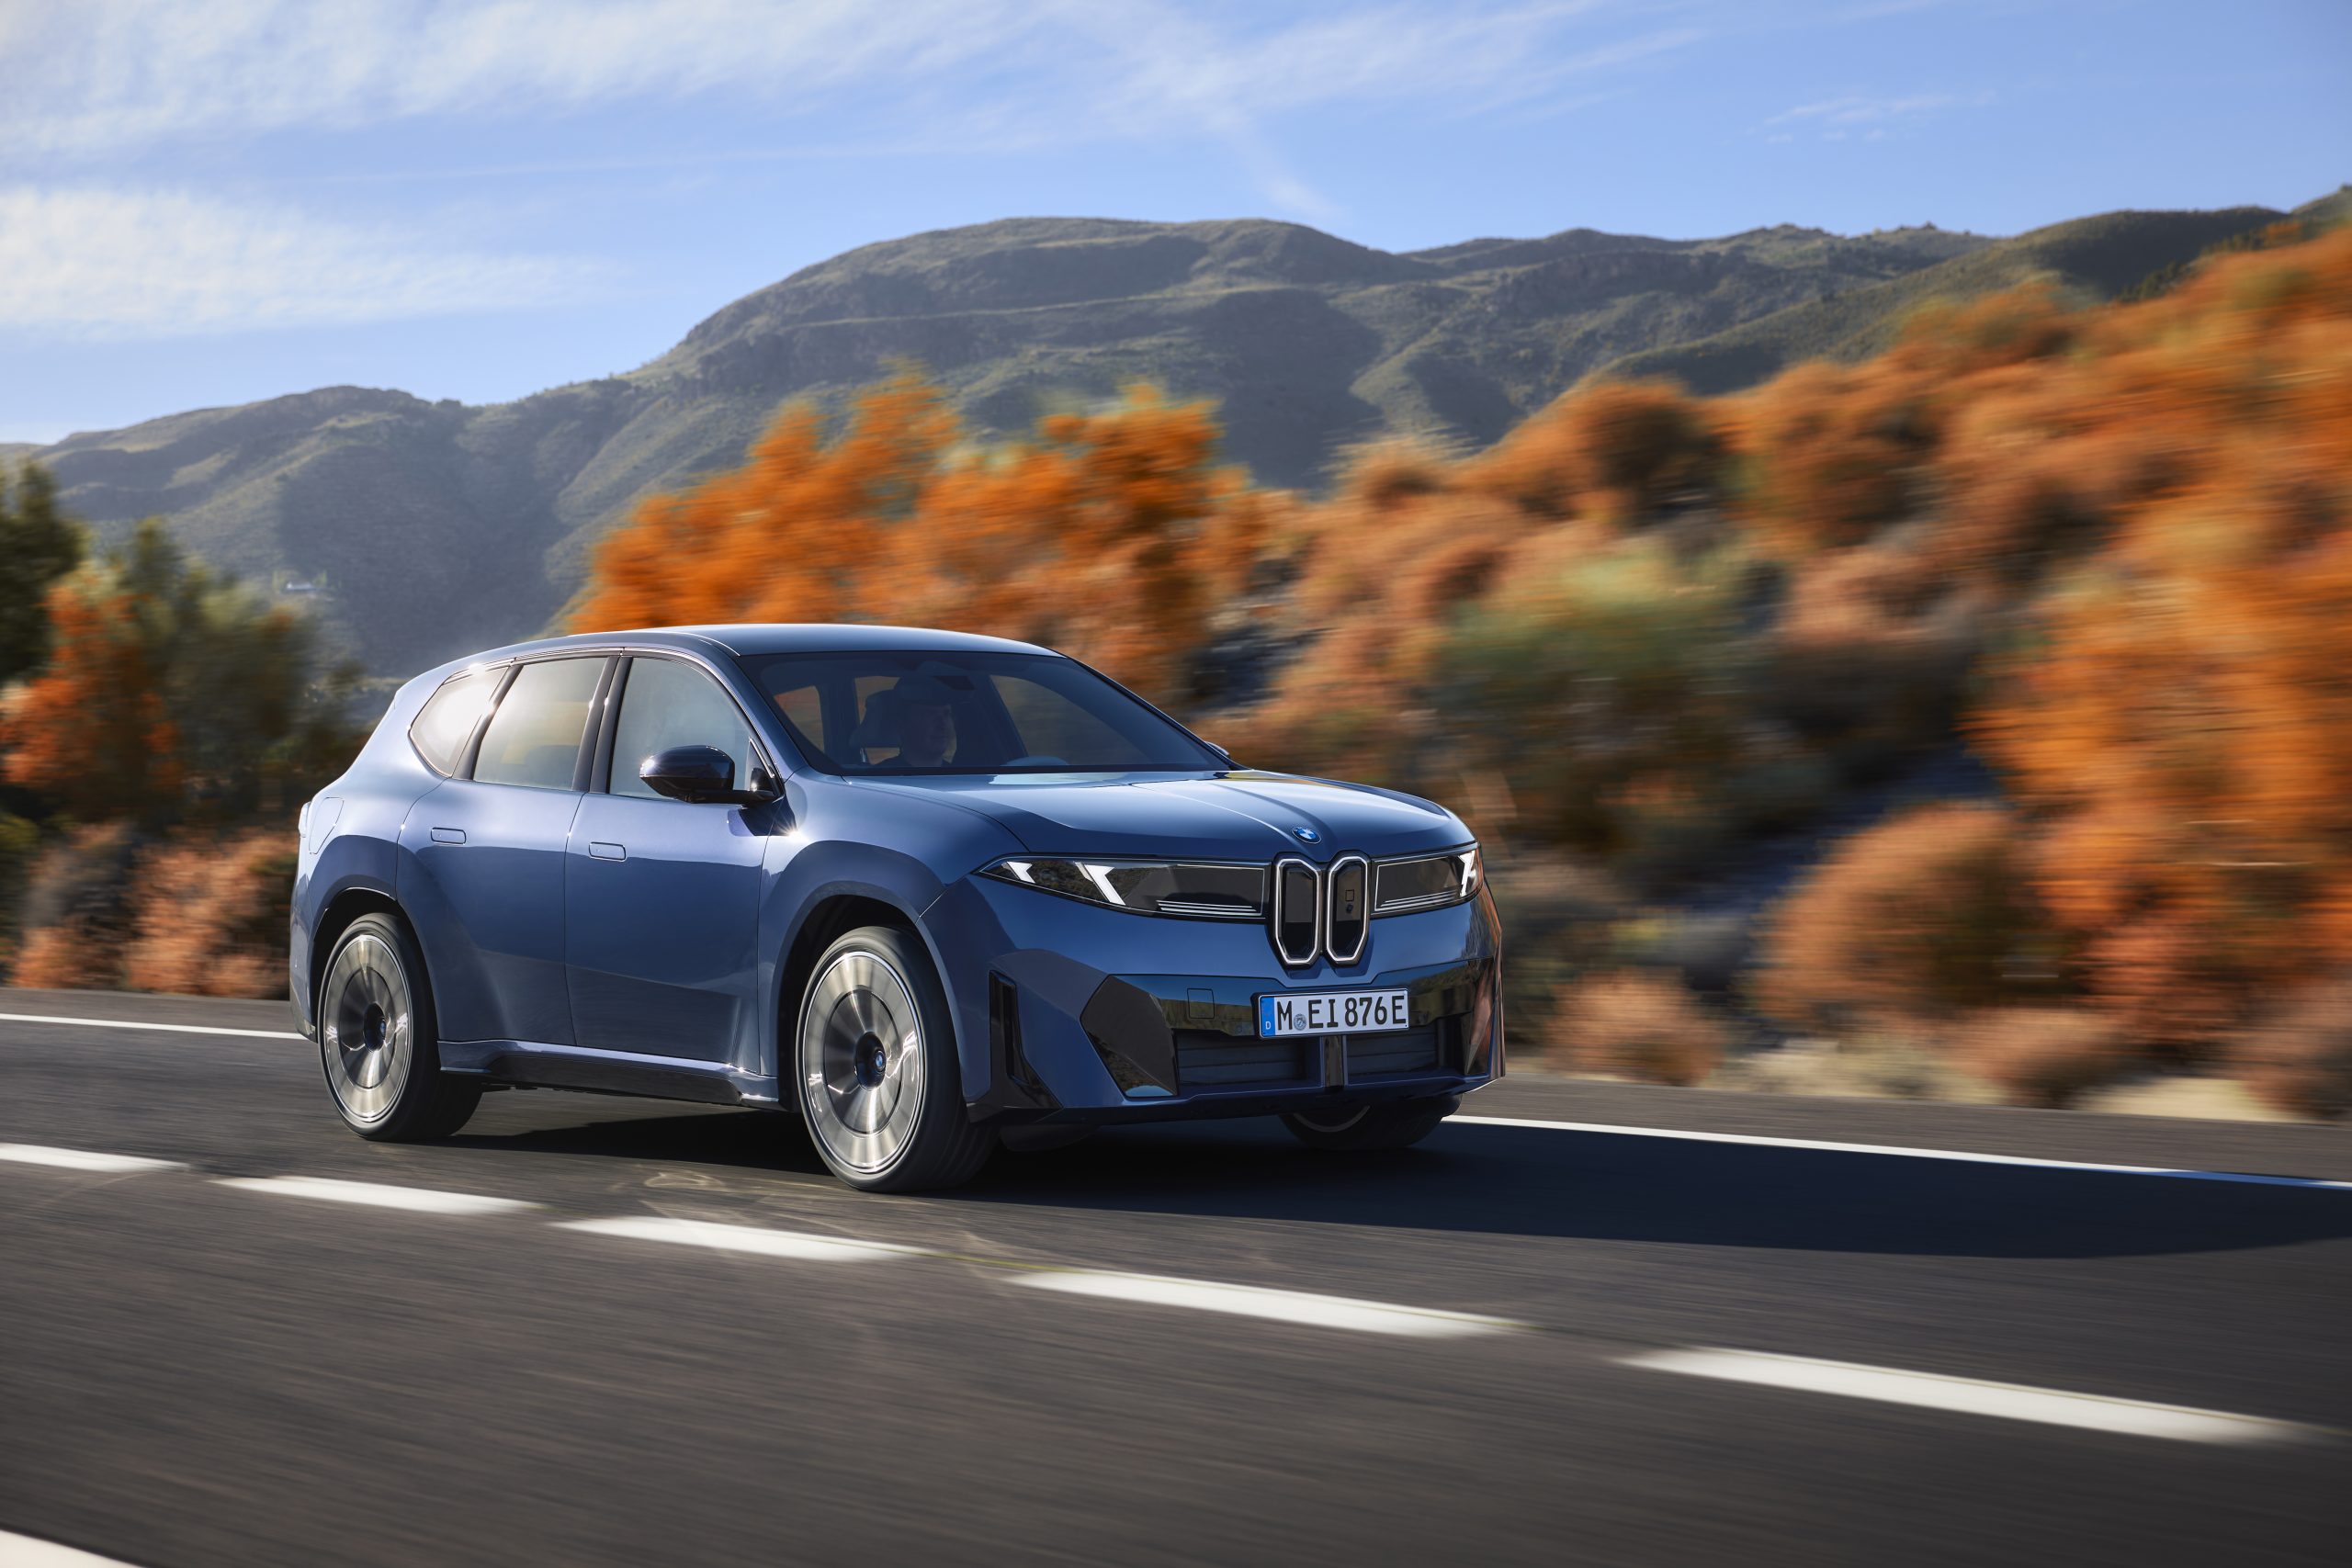
BMW has unveiled the Neue Klasse in Munich, marking its biggest investment to date and a new era of electrification, digitalisation and sustainable design.
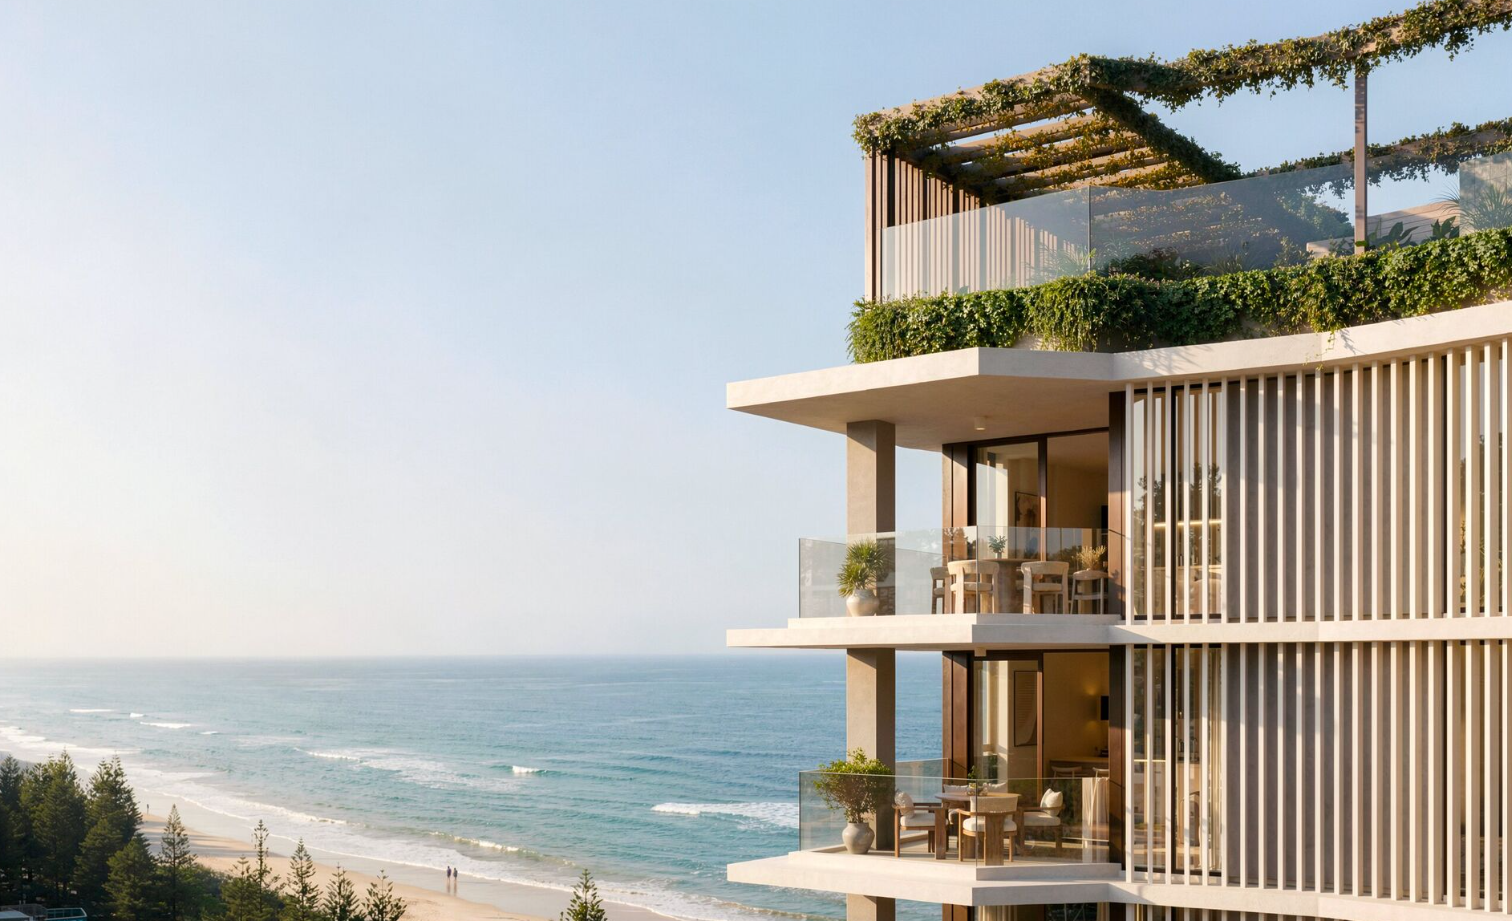
Studio apartments have almost disappeared from new Australian developments. Lura is bringing them back to Burleigh Heads from $495,000.