

The 60-Year-Old Real-Estate Agent Giving History Lessons on Instagram
Georgetown agent Jamie Peva blends history and real estate on Instagram, turning local stories into a powerful sales strategy.

 5 min
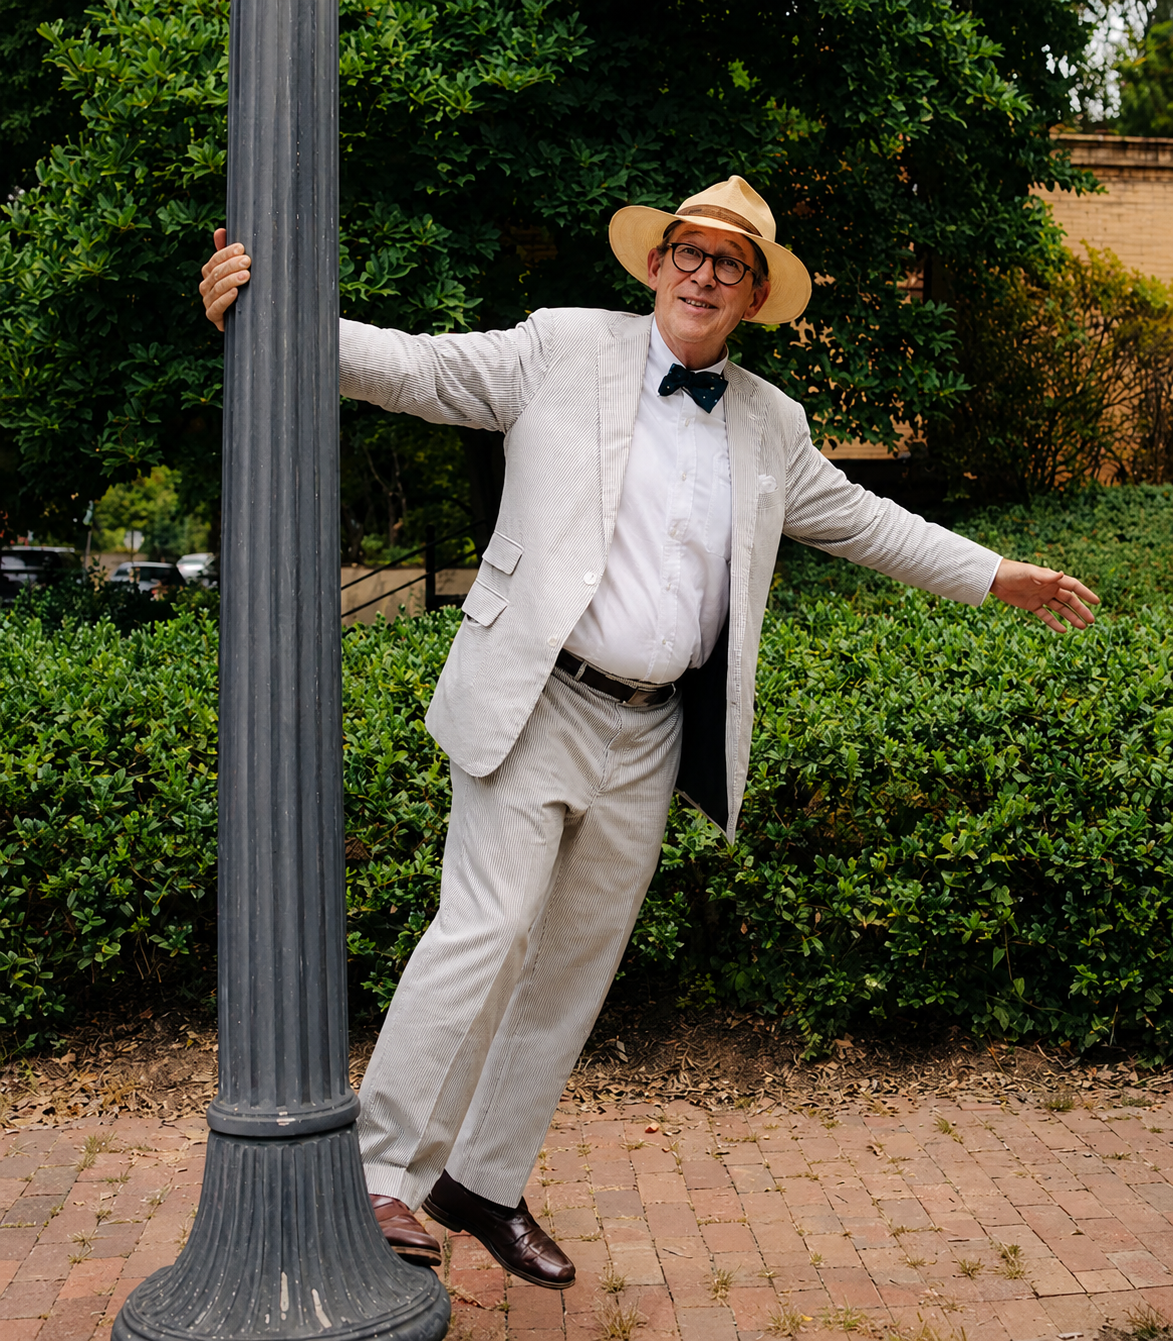
On a recent morning in Georgetown—Washington, D.C.’s oldest neighborhood—real-estate agent Jamie Peva strode down leafy N Street, brimming with historical tidbits.
Jackie Kennedy once lived on the street, he said. So did Ben Bradlee, former executive editor of the Washington Post, along with a former Miss America and a powerful U.S. Senator. Bradlee’s widow, author Sally Quinn, and Eric Schmidt, former CEO of Google, own stately homes there.
“I’ve seen a picture of Lyndon Johnson coming out of this house,” said Peva, passing a Federal-style brick mansion. “Also, the Beatles went to a lawn party here.”
Peva, a 60-year-old agent with Washington Fine Properties, has sold Georgetown real estate for over three decades, often traversing the neighborhood by bicycle. Of the roughly 2,500 houses in the historic neighborhood, he has been involved in the sale of 460, he estimated. A self-styled historian of the neighborhood, he knows stories behind its houses and their owners going back generations.
With a knack for lively storytelling, he shares his knowledge with some 37,500 Instagram followers, who have made Peva—sporting the bow ties he has worn since boarding school—an unlikely social-media influencer. Many of his followers are locals, and most have no plans to buy or sell real estate—until they do. It is then, according to Peva, that his spirited reels bring him to mind.
“It’s the digital version of a refrigerator magnet,” he said.
After Peva’s first video in November 2023, his eponymous Instagram account sparked a 10% increase in sales volume in the first year, and another 20% the next, he estimated. “It’s been very good for business, there is no question about it,” he said.
But Peva’s posts have also made him a local celebrity. As he walked down N street, the driver of a Mercedes station wagon slowed down to honk and wave. A lady walking a large dark gray dog stopped to ask what he was filming that day (a reel about a Colonial-era bottling plant.) Peva knew the dog from walking his two springers, Jumpy and Peggy-O, in the neighborhood.
“I need to make a video about the pooches of Georgetown,” he mused.
A growing number of real-estate agents now use social media to sell, and some have millions of followers with reels featuring ultraluxury pads, selling tips or reality TV-style reports on their daily lives. While Peva posts about his listings—and sometimes those of other agents—he mostly focuses on Georgetown history, local businesses and community events, saying his goal is to benefit both his business and the neighborhood.
“If we don’t find something genuinely interesting and worth sharing, we won’t do it,” said Peva’s daughter, Violet Peva, a New York social-media strategist who films, edits and posts his reels. “We cover many topics, not just real-estate information.”
Peva is originally from Connecticut, but has lived in Georgetown for over 30 years, currently in a cottage-style house with a white picket fence. Over the years, Georgetown has changed. The Georgetown Set, a powerful group of Cold War-era residents whose Sunday-night potluck dinners are said to have swayed U.S. policy, has long faded away. The community is still home to high-profile Washingtonians, including a Republican senator and several cabinet members. But it increasingly also attracts technology and finance executives, according to Peva. He now routinely signs nondisclosure agreements, ensuring privacy for wealthy clients. The shift has made him rethink his marketing approach.
“For years, a big part of our Georgetown business was made up of people who maintained a low profile,” he said. Real-estate agents were similarly low-key. Today, curb appeal is more important, he said, and agents are promoting themselves more. “As this change was underfoot, I was thinking that I needed to evolve myself too,” he said.
Though his own social-media use is mostly limited to following sailing accounts, he asked his daughter to help him post his listings online. Violet, now 26, started coming to D.C. once a month to film his reels. After an early video, on a condominium building called the Elliott, her sister Fern called her to report: “Daddy’s blowing up on Instagram,” Violet recalled. The reel got over 50,000 views. The next two each drew over 300,000. Peva’s most popular post ever, with over 838,000 views, was about the Grateful Dead playing in Georgetown. Sometimes, Peva interviews Georgetowners such as Quinn, the author, or Jamie Stachowski, the owner of a local butcher shop.
Peva, who majored in history in college, now spends up to two hours a day on research, usually in the morning while on his stationery bike. Online, he pores over old newspapers or the Library of Congress website, and he has a collection of articles and books—in and out of print—about Georgetown.
Companies often approach Peva for promotional posts, he said, but he turns them down, feeling that followers would lose interest in constant commercials. One exception is a recent paid post on Mount Vernon, the former home of George Washington. Peva wanted to share its history, he said, and didn’t want to lose the opportunity to another Instagrammer.
Anthony Arend, a professor at Georgetown University, has lived in his current home for 19 years without any plans to sell or buy real estate. But he follows Peva and often likes his posts.
“He is very charismatic, he is energetic, and he obviously knows a lot about the community,” said Arend, who has referred house-hunting friends to Peva.
One of Peva’s biggest deals—the $10.5 million sale of a 19th-century Italianate mansion—came after he made two 2024 reels featuring the property. In March, he sold the longtime O Street home of Tim and Jane Matz for $5.8 million after featuring it on his Instagram. Peva had showed them the home 25 years earlier, with Violet in a baby carrier on his back.
Last year, Kate Watts, 49, a digital consultant, called Peva to sell her late father’s three-bedroom house on Q Street; her husband had seen Peva on Instagram. In an October reel, Peva praised the architecture of the house, designed by modernist Hugh Newell Jacobsen. Halfway through, he mentioned an open house the next day, ending with an upbeat: “Did I also mention this house is for sale? $3.75 million!” The reel got 27,000 views, the open house was packed, and the buyers made an offer at the list price on the same day.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.
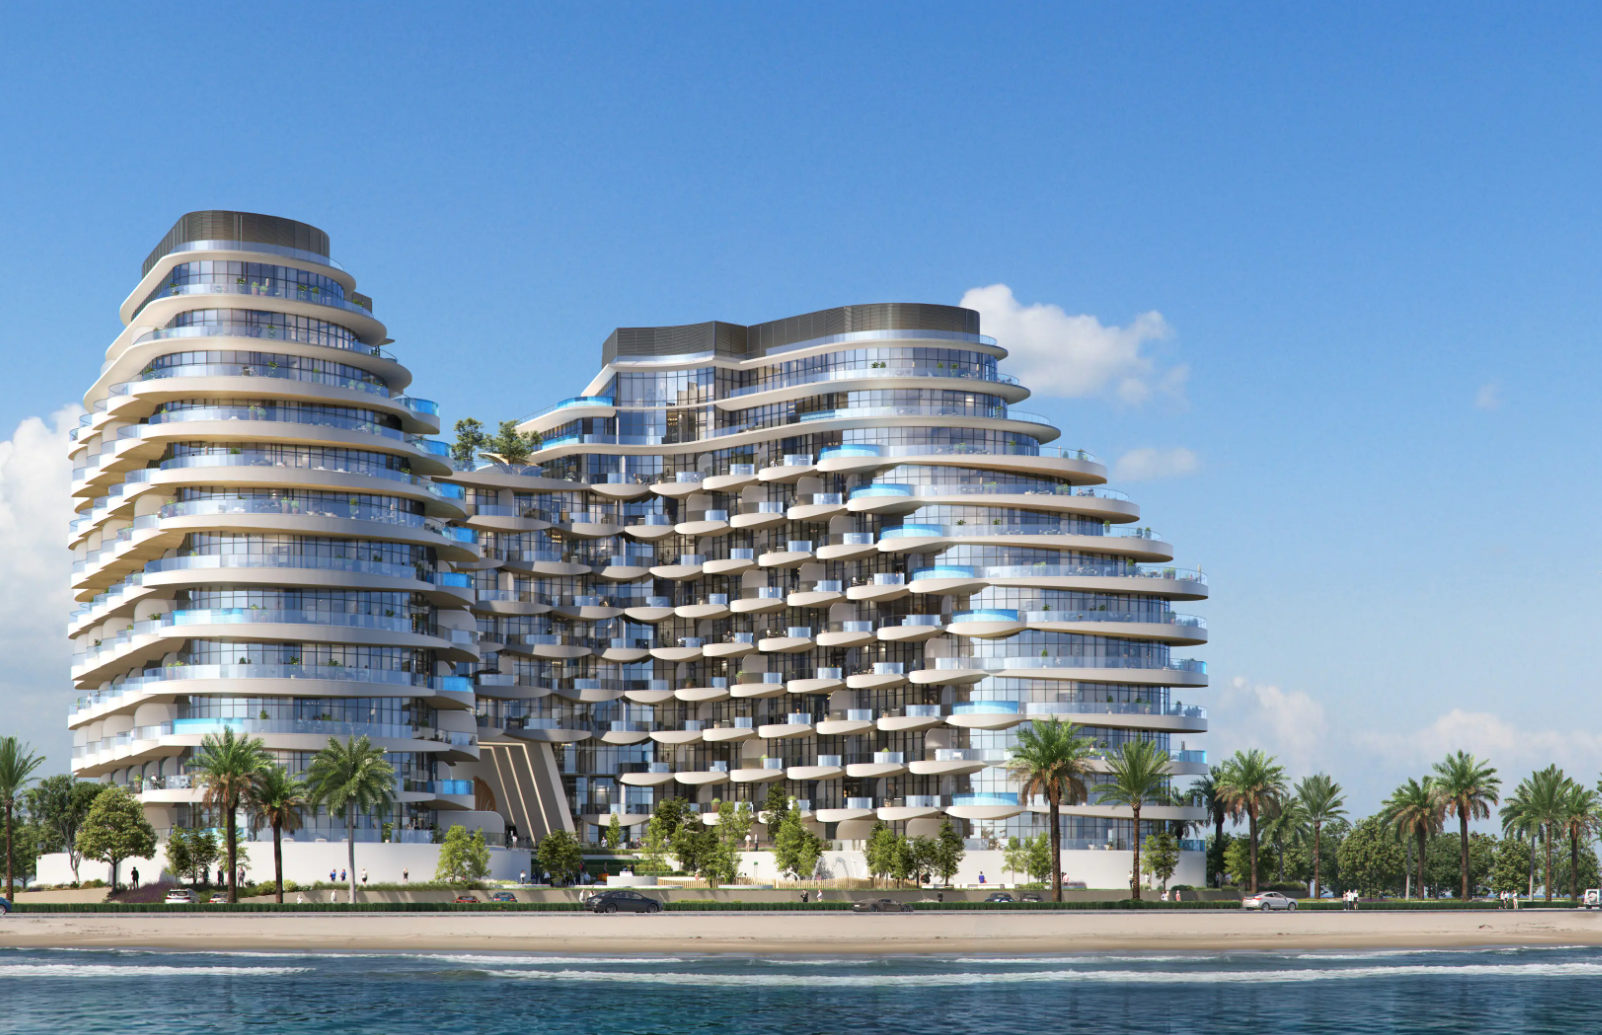
BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.

From elevated skincare to handcrafted home pieces, this year’s most thoughtful gifts go beyond the expected.
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”