The Rise of Women’s Sports Unlocks Unexpected Sponsorships
Unknown startups, female-focused companies and other brands with no prior dealings with sports are being named official sponsors of women’s leagues and teams

 4 min
Makeup brands, hair-care startups and fertility clinics historically haven’t been associated with sports. Now they’re taking over game nights as the draw of elite women’s players, teams and leagues attracts new kinds of sponsors.
The menstrual care brand Sequel this week was named as the official tampon provider of USL Super League, for example, as the new professional women’s soccer league prepares to start play this month. The Kansas City Current, part of the National Women’s Soccer League, in December granted naming rights of its stadium’s main entrance to Helzberg Diamonds, its official jeweller.
And the Women’s National Basketball Association’s New York Liberty has accompanied familiar corporate sponsors such as the financial giant Barclays and hotel brand Marriott with newer partners such as the acne-focused skin-care company Hero, women’s workwear designer M.M.LaFleur and fertility centre RMA of New York.
“There were years where I would scratch my head as to why we weren’t garnering more endemic interests, like, why wouldn’t the beauty companies and the hair-care companies and the clothing companies want to align with women?” said Keia Clarke , chief executive of the Liberty. “Now, finding those brands is not hard.”
The new sponsors are being drawn by fans’ growing appetite and female athletes’ soaring cultural cachet and social-media reach.
“There’s interest from new brands that have never ventured into the sports space before because they weren’t appropriate for men’s sports,” said Erin Kane , vice president of women’s sports at Excel Sports Management, a management and marketing agency.
At the same time, lower prices to back women’s sports mean that a wider pool of businesses can get into the game if they so desire. Despite the growing spotlight, women’s sports are still cheaper to sponsor.
Breaking records
The surge in women’s sports comes as sports in general is ascendant in media and marketing. Game days are one of the last occasions standing that can reliably deliver large TV audiences and generate conversation on social media across most demographics.
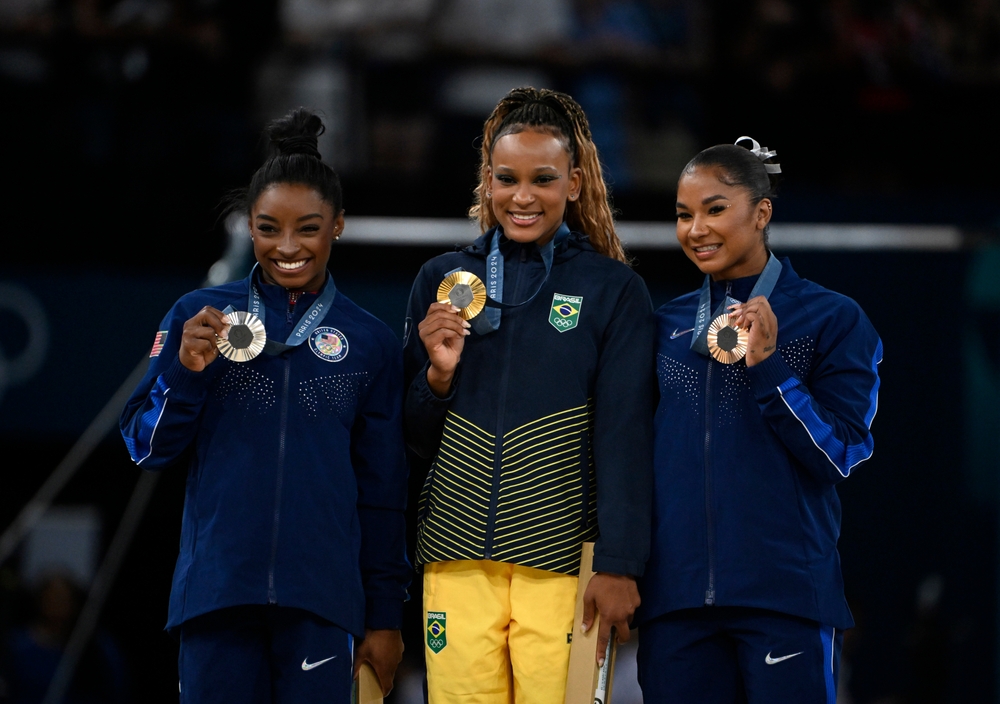
April’s championship game of the National Collegiate Athletic Association’s women’s basketball tournament for the first time drew more viewers than the men’s equivalent, fuelled in part by hype around superstar Caitlin Clark . The hype also helped bring attention to the tournament as a whole; viewership of even games she wasn’t in rose 76% year-over-year. And much of the excitement around Team USA at this year’s Olympics has centred on its female stars, rugby player Ilona Maher, swimmer Katie Ledecky, and gymnast Simone Biles and her teammates .
Women’s elite sports will generate around $1.3 billion in revenue globally in 2024, up from $981 million in 2023 and $692 million in 2022, according to consulting firm Deloitte. Commercial deals, including sponsorships, will make up around 55% of that revenue, according to the company, which does not report similar figures for men’s sports.
By way of comparison, the National Basketball Association’s team sponsorship revenue alone was estimated to be worth $1.5 billion for the 2023-24 season, according to sports and entertainment data firm SponsorUnited.
Some companies previously found themselves sponsoring women’s sports as a result of dual packages—buy-one-get-one-style deals whereby sports businesses that owned and operated both men’s and women’s teams would offer partner status across both for a huge discount on the women’s side.
Those kinds of deals are no longer in fashion, sports executives said.
David King , senior vice president of corporate partnerships for the NBA’s Minnesota Timberwolves and the WNBA’s Minnesota Lynx, said he is discussing more brand deals that are specific to the Lynx.
“That wasn’t necessarily the case a few years ago,” King said. “I welcome the day there’s an onslaught of people calling us, but there’s certainly more now than there’s been before.”
Minneapolis-based hair-care company Odele became a sponsor after hearing the pitch about aligning with passionate women and supporting equality, despite the WNBA’s shorter season and lower viewership compared with the NBA.
“These athletes are at the forefront of what influencers can be and should be,” said Lindsay Holden , co-founder of the brand.
The team has been distributing samples, coupons and hosting giveaways at games, and presented a “get ready with me” TikTok series featuring Lynx players.
Brands with less tangible offerings have sought creative ways to activate their partnerships, and often with little-to-no experience in sports marketing, executives say.
RMA of New York, the New York Liberty fertility centre sponsor, introduced a campaign called “Let’s Go, Baby!” that filled the team’s Brooklyn arena with merch giveaways and scoreboard animations during a Pride-themed game in June. And birth-control medication Opill, a WNBA league sponsor since April, this season has set up booths designed to educate women on contraception at other events like the fan festival WNBA Live.
Pricing performance
Women’s sports executives are now trying to narrow the price gap with men’s sponsorships.
“We’ve gotten pretty aggressive with what we’re asking our partners to spend,” said King, the Lynx executive, declining to confirm specific sponsorship costs. “We’re not going to grow our business by doing the $10,000, $20,000 and $30,000 deals anymore.”
Team owners and sales executives are trying to persuade marketers that women’s sports have more value in terms of engagement than has been historically recognised, even when viewership remains generally lower, games are often fewer or less frequent, and it’s still hard for top players to match the international star power of a Travis Kelce or Lionel Messi .
“Women’s sports is a brand conversation, it’s an engagement conversation—it’s less so a transactional, asset-based conversation,” said Laura Correnti , the founder and CEO of women’s sports firm Deep Blue Sports + Entertainment. “And so that requires teams to examine their pitch strategy, and not necessarily lead with how many people they reach.”
While a five-figure brand deal was once an acceptable number for WNBA sales teams, that’s no longer the case, said New York Liberty’s Clarke. The organisation in the past few years has regularly begun pitching and inking six-figure deals, and sometimes seven-figure deals, she said. The Liberty this season has 47 sponsors, up from 31 last season and 17 in 2022.
“It was easy before to dismiss the WNBA because the excuse was always, you don’t have the numbers. And now it’s like, well, we do have numbers, and we also have these really cool other attributes,” Clarke said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.
Australia’s housing market defies forecasts as prices surge past pandemic-era benchmarks.