

Wall Street Is Counting on Nvidia to Keep the AI Party Going
Nvidia’s earnings will test Wall Street’s confidence in the AI boom.

 3 min
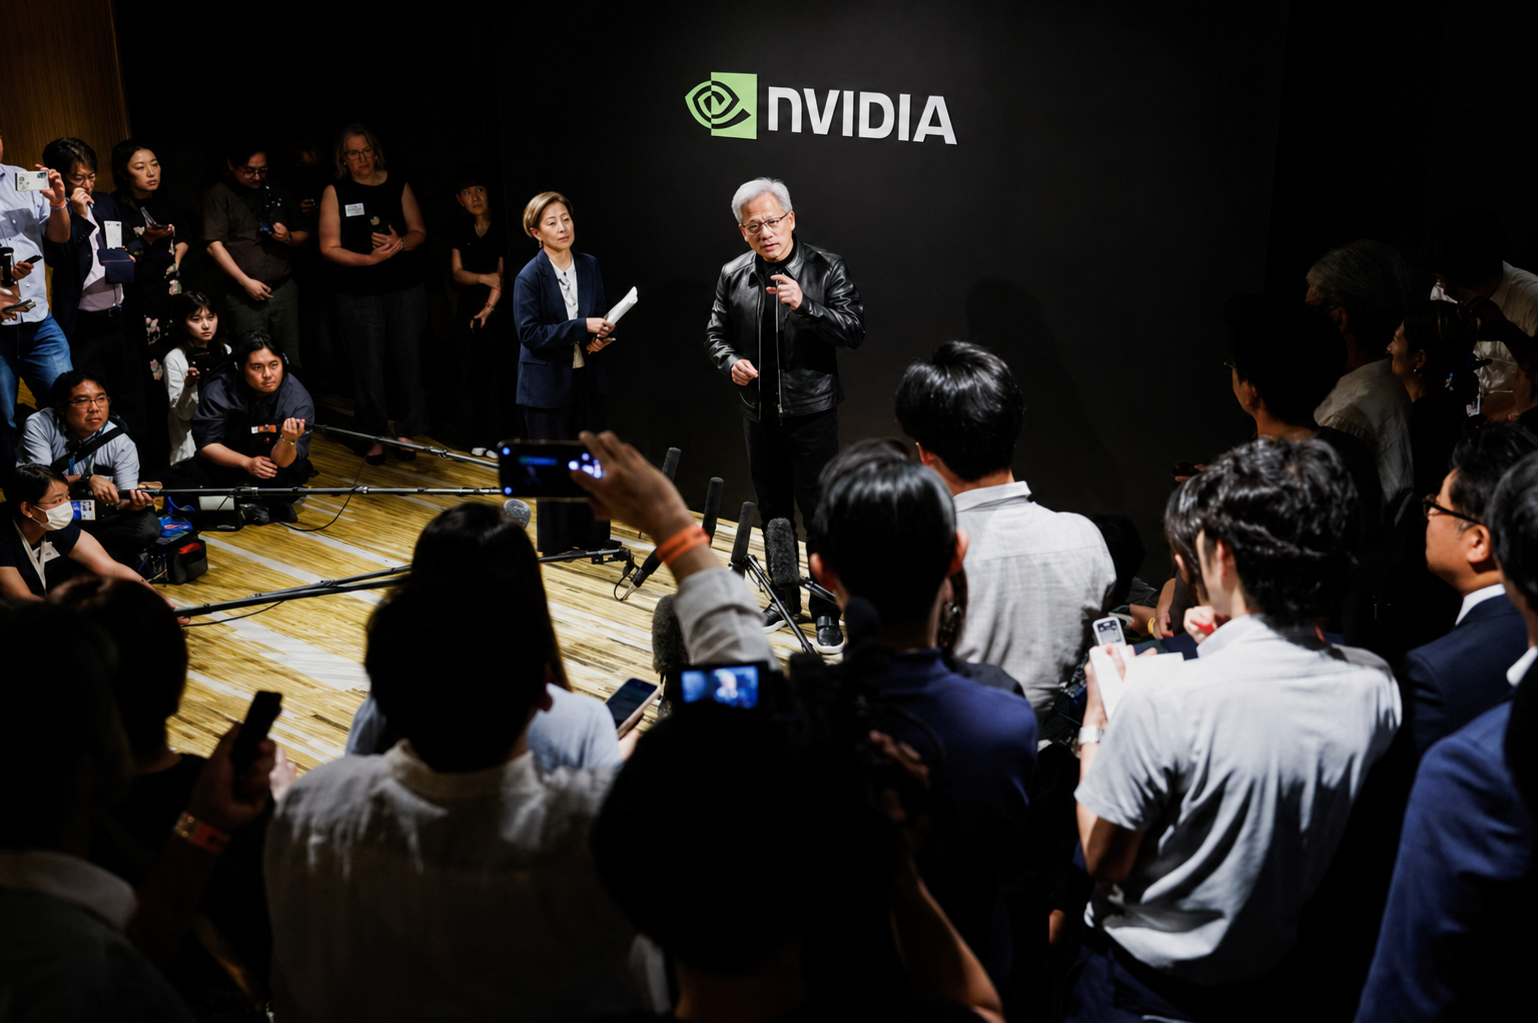
Chip makers are fighting to assure investors that the artificial-intelligence boom is racing forward. Wall Street might not believe it until Nvidia’s NVDA -0.98%decrease; down pointing triangle Jensen Huang says so.
When Huang steps up to the mic for his company’s earnings call Wednesday, he will have the world’s attention. What he says about Nvidia’s present will preview the future of AI, dictate the path forward for a tech-crazed stock market and influence an American economy increasingly tethered to hopes that the boom won’t go bust.
The $5 trillion chip maker has provided the key building blocks for AI since the launch of ChatGPT in 2022 set off a race for dominance among OpenAI, Anthropic and established Silicon Valley giants. Now, as Nvidia backstops sprawling data-center projects and an exotic money pipeline to boost chip demand, the company’s influence is arguably bigger than ever.
But there are signs of trouble ahead. Political pushback to AI is growing. A bond selloff propelled borrowing costs to their highest levels in years. The hyperscalers that include some of Nvidia’s key customers—once cash-printing machines—are relying more on debt. OpenAI recently told investors its revenue rose by a tepid 18% in the second quarter while its losses deepened.
Nvidia is increasingly stepping in to shore up potential weak points across the market. Earlier this month, the company teamed up with six of Wall Street’s biggest firms on a $500 billion AI-financing plan, pledging to backstop lending to customers that can’t afford its chips otherwise. The chip maker last week also took a stake in Cloverleaf Infrastructure, which arranges power for data centers, and struck a $6 billion deal with startup Poolside aimed at developing a powerful open-weight AI model.
After watching shares in other chip makers and the so-called Magnificent Seven tech companies swing wildly in recent months, Wall Street is hoping Nvidia can beat expectations—again. The countdown is on.
“It’s kind of becoming more and more like the World Cup final than the Super Bowl at this point,” said Brian Mulberry, chief market strategist at Zacks Investment Management. “It’s just gotten to be that big.”
The company has smashed analysts’ earnings estimates for each of the 14 quarters since the AI boom kicked into high gear. Nvidia posted 210% annual growth in net income in its last three-month period, according to FactSet, making Wall Street’s 126% projection look pedestrian.
Expectations for a blowout second quarter have risen rapidly over the course of this year. All Nvidia will have to do to beat this target: outrun 95% annual earnings growth to more than $51.5 billion. Analysts project the chip maker will report record sales of $92 billion for the period, up from a forecast of $78 billion at the start of this year.
In July, big-tech earnings sparked volatility. Concerns about runaway capital spending spread across the sector after Alphabet’s and Tesla’s results, driving a $890 billion wipeout that contributed to the unwind of hedge fund Situational Awareness. Microsoft posted the largest one-day gain in market capitalization by any company, ever, after a quarter proving that it could still show investors the money. SpaceX rocketed higher after a record-breaking initial public offering, only to see $1 trillion in value evaporate.
Surging memory prices and borrowing costs have fueled fears that those and other companies will be unable to keep plowing more money into supplies including Nvidia chips. Shaia Hosseinzadeh, founder of OnyxPoint Global Management, has recently bought dips in AI-infrastructure stocks when Wall Street has strained to absorb massive debt issued by Silicon Valley.
“The macro data is really quite robust,” he said. “Of course, there’s a level at which everything breaks.”
Investors have kept pumping money into the AI trade despite concerns around chip consumers—and to the benefit of chip producers. That is why Nvidia’s outlook for semiconductor demand could send ripples through counterparts such as Micron Technology and Sandisk, developers of the data centers in which their chips reside, and a supply chain of power producers, contractors and other specialists that underpin the globe-spanning AI build-out.
“We joke internally that we’re all Nvidia analysts now,” said David Lefkowitz, head of U.S. equities at UBS Global Wealth Management.
The irony is that investors have tended to sell Nvidia stock immediately after blockbuster earnings, with shares falling each trading session after its four past quarterly reports. Some are betting that will be the case this time around, too.
The options market is pricing in a 5.3% swing, higher or lower, in Nvidia shares during the session following earnings, according to Option Research & Technology Services. That is higher than the 4.8% average move in Nvidia’s stock over the last 12 months after the company reports quarterly results.
In recent days, some of the most actively traded Nvidia options have been put contracts tied to the stock falling from its Friday value of $214.75 to $205 and $210 apiece, according to Cboe Global Markets data. Put options give the right to sell a stock by a set price and typically represent a bearish wager.
Many analysts remain optimistic. Frank Lee, global head of tech hardware and semiconductor research at HSBC Global Investment Research, recently raised his price target for Nvidia shares to $360 from $325, citing, among other things, Nvidia’s strategic partnerships with suppliers and its role as a top contributor to open-source AI.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
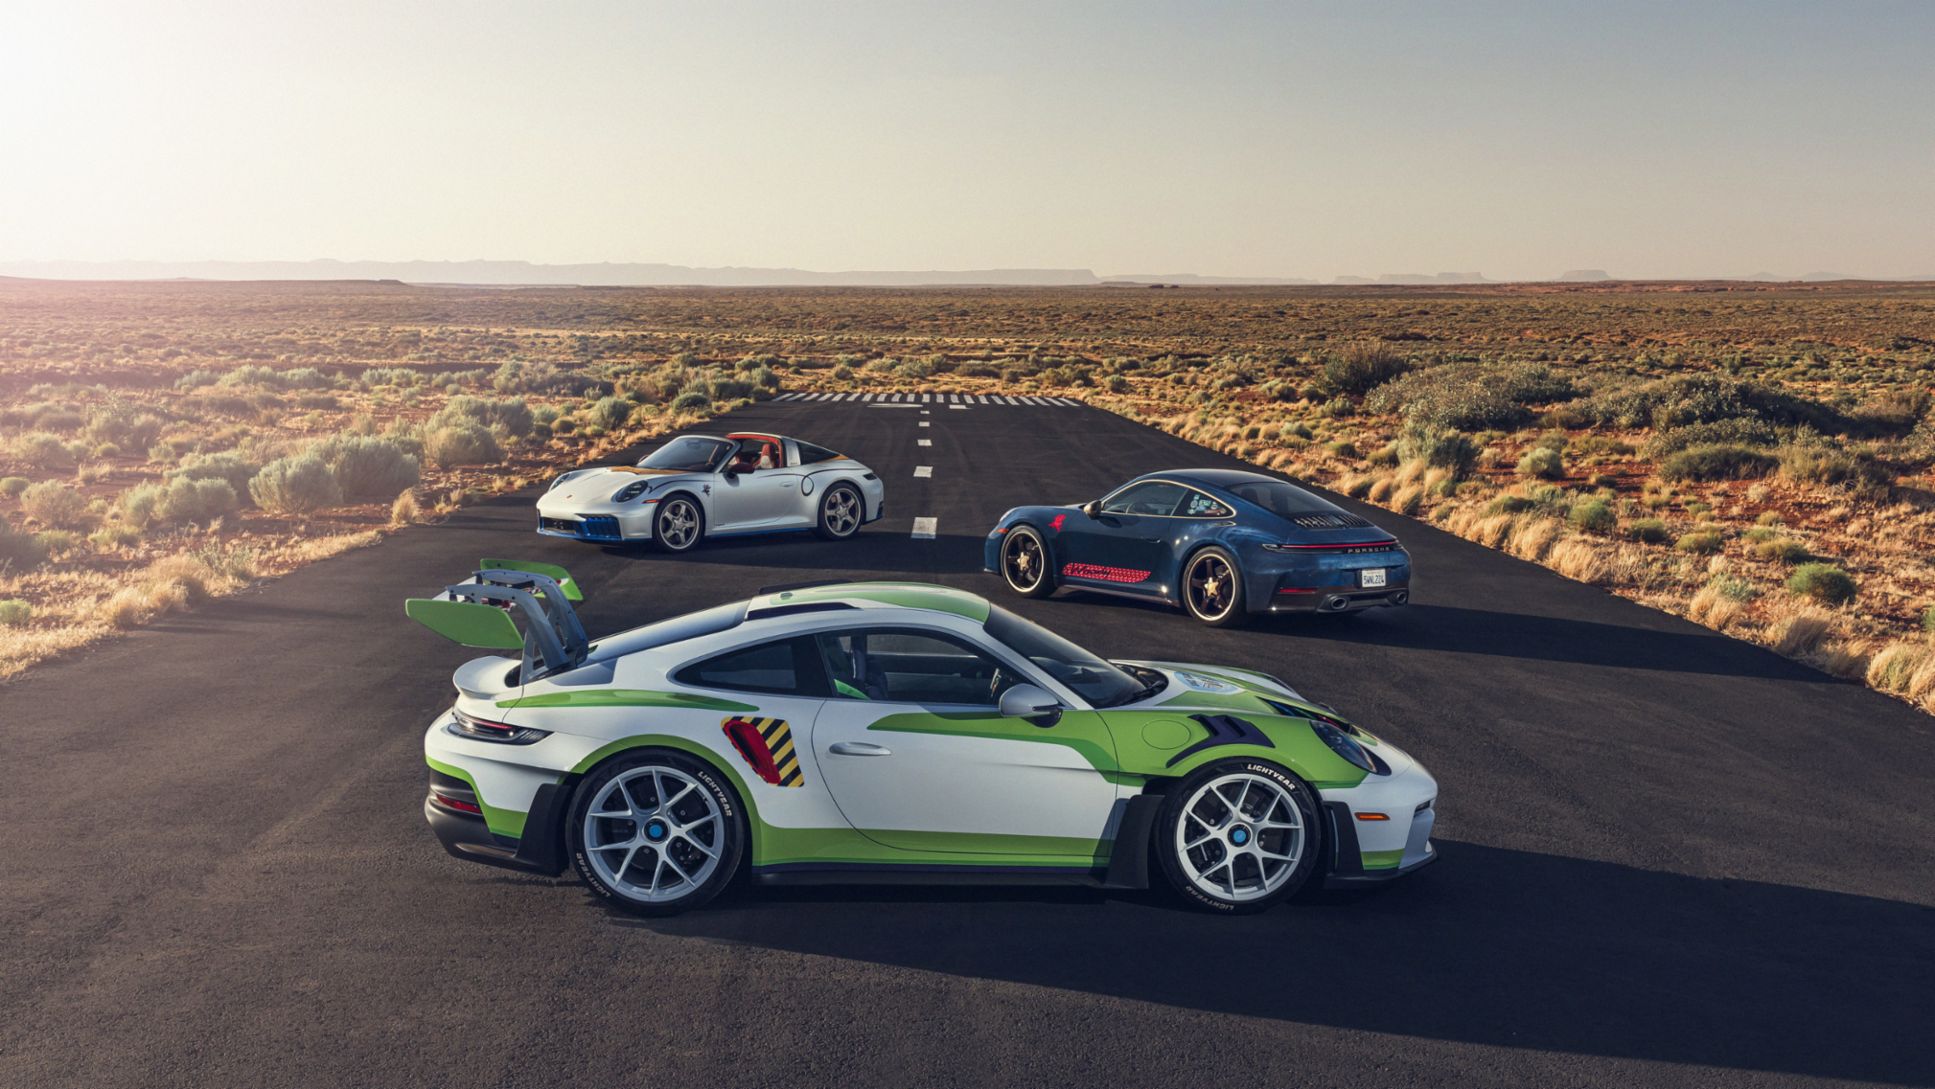
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations
5 min
Reporting season has once again reminded investors that a strong profit does not guarantee a rising share price, and a large loss does not always trigger a sell-off. What matters most is how each result compares with expectations and, increasingly, what management says about the year ahead. During the August 2026 season, companies offering credible turnarounds or unexpectedly strong guidance were rewarded handsomely, while those flagging weaker margins, slowing demand or greater uncertainty were punished.
The following ranking draws on Morningstar’s review of 164 ASX-listed companies and measures each company’s share-price movement on the day it reported. This captures the market’s immediate response to the earnings announcement, before subsequent economic developments, dividends and company-specific news cloud the picture. Here are the five biggest winners, and the five hardest-hit losers, of the season so far.
The five winners
1. Bapcor (ASX:BAP): +41.0%
Bapcor delivered reporting season’s largest relief rally after presenting early evidence that its troubled automotive-parts business was stabilising. Although underlying revenue fell 1.8% to $1.92 billion and underlying NPAT collapsed 85% to $10.8 million, underlying EBITDA of $152.5 million exceeded guidance.
More importantly, working-capital initiatives released $68.5 million in the second half, lifting cash conversion to 109.4% and reducing net debt by 63% to $135 million. The statutory loss was $431.6 million, largely because of non-cash impairments. Investors focused on improving operational momentum, stronger liquidity and management’s expectation of modest FY27 revenue growth.
2. Zip Co (ASX:ZIP): +18.2%
Zip comfortably surpassed its FY26 targets, sending the buy-now-pay-later provider’s shares sharply higher. Transaction volume rose 23% to $16.7 billion, while cash earnings before tax, depreciation and amortisation jumped 58% to a record $268.9 million. Statutory profit climbed 46% to $116.4 million, and the cash operating margin expanded by 4.2 percentage points to 20%.
The strongest signal was guidance for FY27 cash earnings of $340 million—around 26% growth and above analysts’ forecasts. US transaction volume increased 42.5% and now represents three-quarters of group volume, offsetting weaker customer activity in Australia.
3. CSL (ASX:CSL): +17.3%
CSL’s result was hardly spectacular in isolation, but it cleared a market bar that had fallen dramatically following earlier downgrades and restructuring announcements. Underlying NPATA was US$3.1 billion, down 2% in constant-currency terms, while operating cash flow reached US$3.51 billion.
CSL maintained its full-year dividend at US$2.92 per share and completed a A$1 billion buyback. The real catalyst was FY27 guidance for approximately 5% underlying profit growth, compared with market expectations closer to 2%. After an extended period of earnings disappointments, investors interpreted the outlook as evidence that CSL’s core plasma business was approaching a sustainable recovery.
4. Judo Capital (ASX:JDO): +16.9%
Judo Capital demonstrated strong operating leverage as its specialist business-lending franchise expanded. Full-year profit before tax rose 34% to $168.1 million, while pre-provision profit increased 42%. Gross loans and advances grew 18% to $14.7 billion, reaching the top of the bank’s guidance range and comfortably exceeding broader system growth.
Deposits increased 24% to $12.2 billion, return on equity improved by 1.1 percentage points to 6.4%, and earnings per share rose 29% to 9.9 cents. Reaffirmation of the FY27 outlook gave investors confidence that loan growth could continue without sacrificing margins or credit quality.
5. Super Retail Group (ASX:SUL): +15.8%
The owner of Supercheap Auto, rebel, BCF and Macpac reported record sales of $4.2 billion, up 3.2%, despite cautious discretionary spending. Profitability went backwards: normalised profit before tax fell 7% to $306 million and normalised NPAT declined 2.8% to $226 million as transformation spending weighed on margins. Nevertheless, the result exceeded subdued expectations, online sales grew 5.3% and membership across the group’s loyalty programs reached 13.1 million. Investors were also encouraged by positive early FY27 trading, stable gross margins and continued market-share gains. A fully franked 33-cent final dividend added to the appeal.
The five losers
1. Hansen Technologies (ASX:HSN): –21.2%
Hansen’s historic result met expectations, but investors recoiled from its outlook. The utility and communications software provider achieved an underlying EBITDA margin of 31%, exceeding its 30% target, while generating strong cash flow. However, management designated FY27 an “investment and transition year”, signalling a roughly five-percentage-point margin contraction as spending on products, sales capabilities and organisational changes increased.
Revenue had already been broadly flat, leaving investors concerned that the investment program would depress earnings before new growth appeared. Leadership changes, including the chief executive’s departure, added uncertainty. Management expects revenue growth and margins above 30% to return in FY28, but the market was unwilling to wait.
2. Life360 (ASX:360): –19.4%
Life360’s headline growth was impressive: quarterly revenue rose 38% to US$159 million, subscription revenue increased 31%, and adjusted EBITDA climbed 53% to US$31.1 million. Monthly active users reached 102.4 million and paying circles grew 27% to 3.2 million. The sell-off reflected expectations rather than a collapsing business.
Net income fell 18%, the net margin contracted from 6% to 3%, hardware shipments dropped 18%, and full-year EBITDA guidance was merely maintained. After a strong valuation run, investors wanted a larger upgrade and clearer evidence that heavy investment in advertising, international expansion and artificial intelligence would generate additional earnings.
3. PEXA Group (ASX:PXA): –17.0%
PEXA reported a 7% increase in continuing-operations revenue and 12% EBITDA growth to $152 million, accompanied by a two-percentage-point margin expansion. Free cash flow increased 39%, suggesting the core Australian electronic-conveyancing platform remained highly profitable. Investors instead concentrated on management’s warning that property-transfer volumes could decline, alongside regulatory uncertainty surrounding the fees PEXA can charge.
The company is also continuing to invest heavily in its loss-making international expansion. Morningstar considered the market reaction excessive, arguing that structural transfer-volume assumptions had not materially changed, but the combination of softer near-term activity and regulatory risk overwhelmed the respectable headline numbers.
4. SEEK (ASX:SEK): –14.3%
SEEK produced solid FY26 figures, including 10% revenue growth to $1.20 billion, a 15% rise in EBITDA and 28% growth in adjusted earnings per share. It also lifted its fully franked annual dividend by 13% to a record 52 cents. Those achievements were overshadowed by falling paid job-ad volumes and cautious FY27 assumptions.
The statutory accounts included a $201 million loss from the SEEK Growth Fund and $377 million of significant items, making the headline result considerably less attractive. Investors were particularly concerned that economic weakness could limit volumes while the company continued investing in platform integration and artificial-intelligence products.
5. JB Hi-Fi (ASX:JBH): –12.3%
JB Hi-Fi’s full-year result was broadly respectable, with group sales rising 5% to $11.1 billion and underlying earnings per share increasing 6% to $4.48. The damage came from its current-trading update. Australian sales were almost flat during the June quarter and deteriorated further in July, while earnings in the core Australian electronics business fell 3.6%.
Housing-related categories were particularly weak as higher living costs and interest rates constrained household budgets. With JB Hi-Fi entering the season on a demanding valuation, an in-line historic result was not sufficient: the loss of sales momentum prompted investors to rapidly reduce their expectations for FY27.
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations. Bapcor was rewarded for being less troubled than feared, while several fundamentally profitable companies were punished because their outlooks failed to justify elevated valuations.
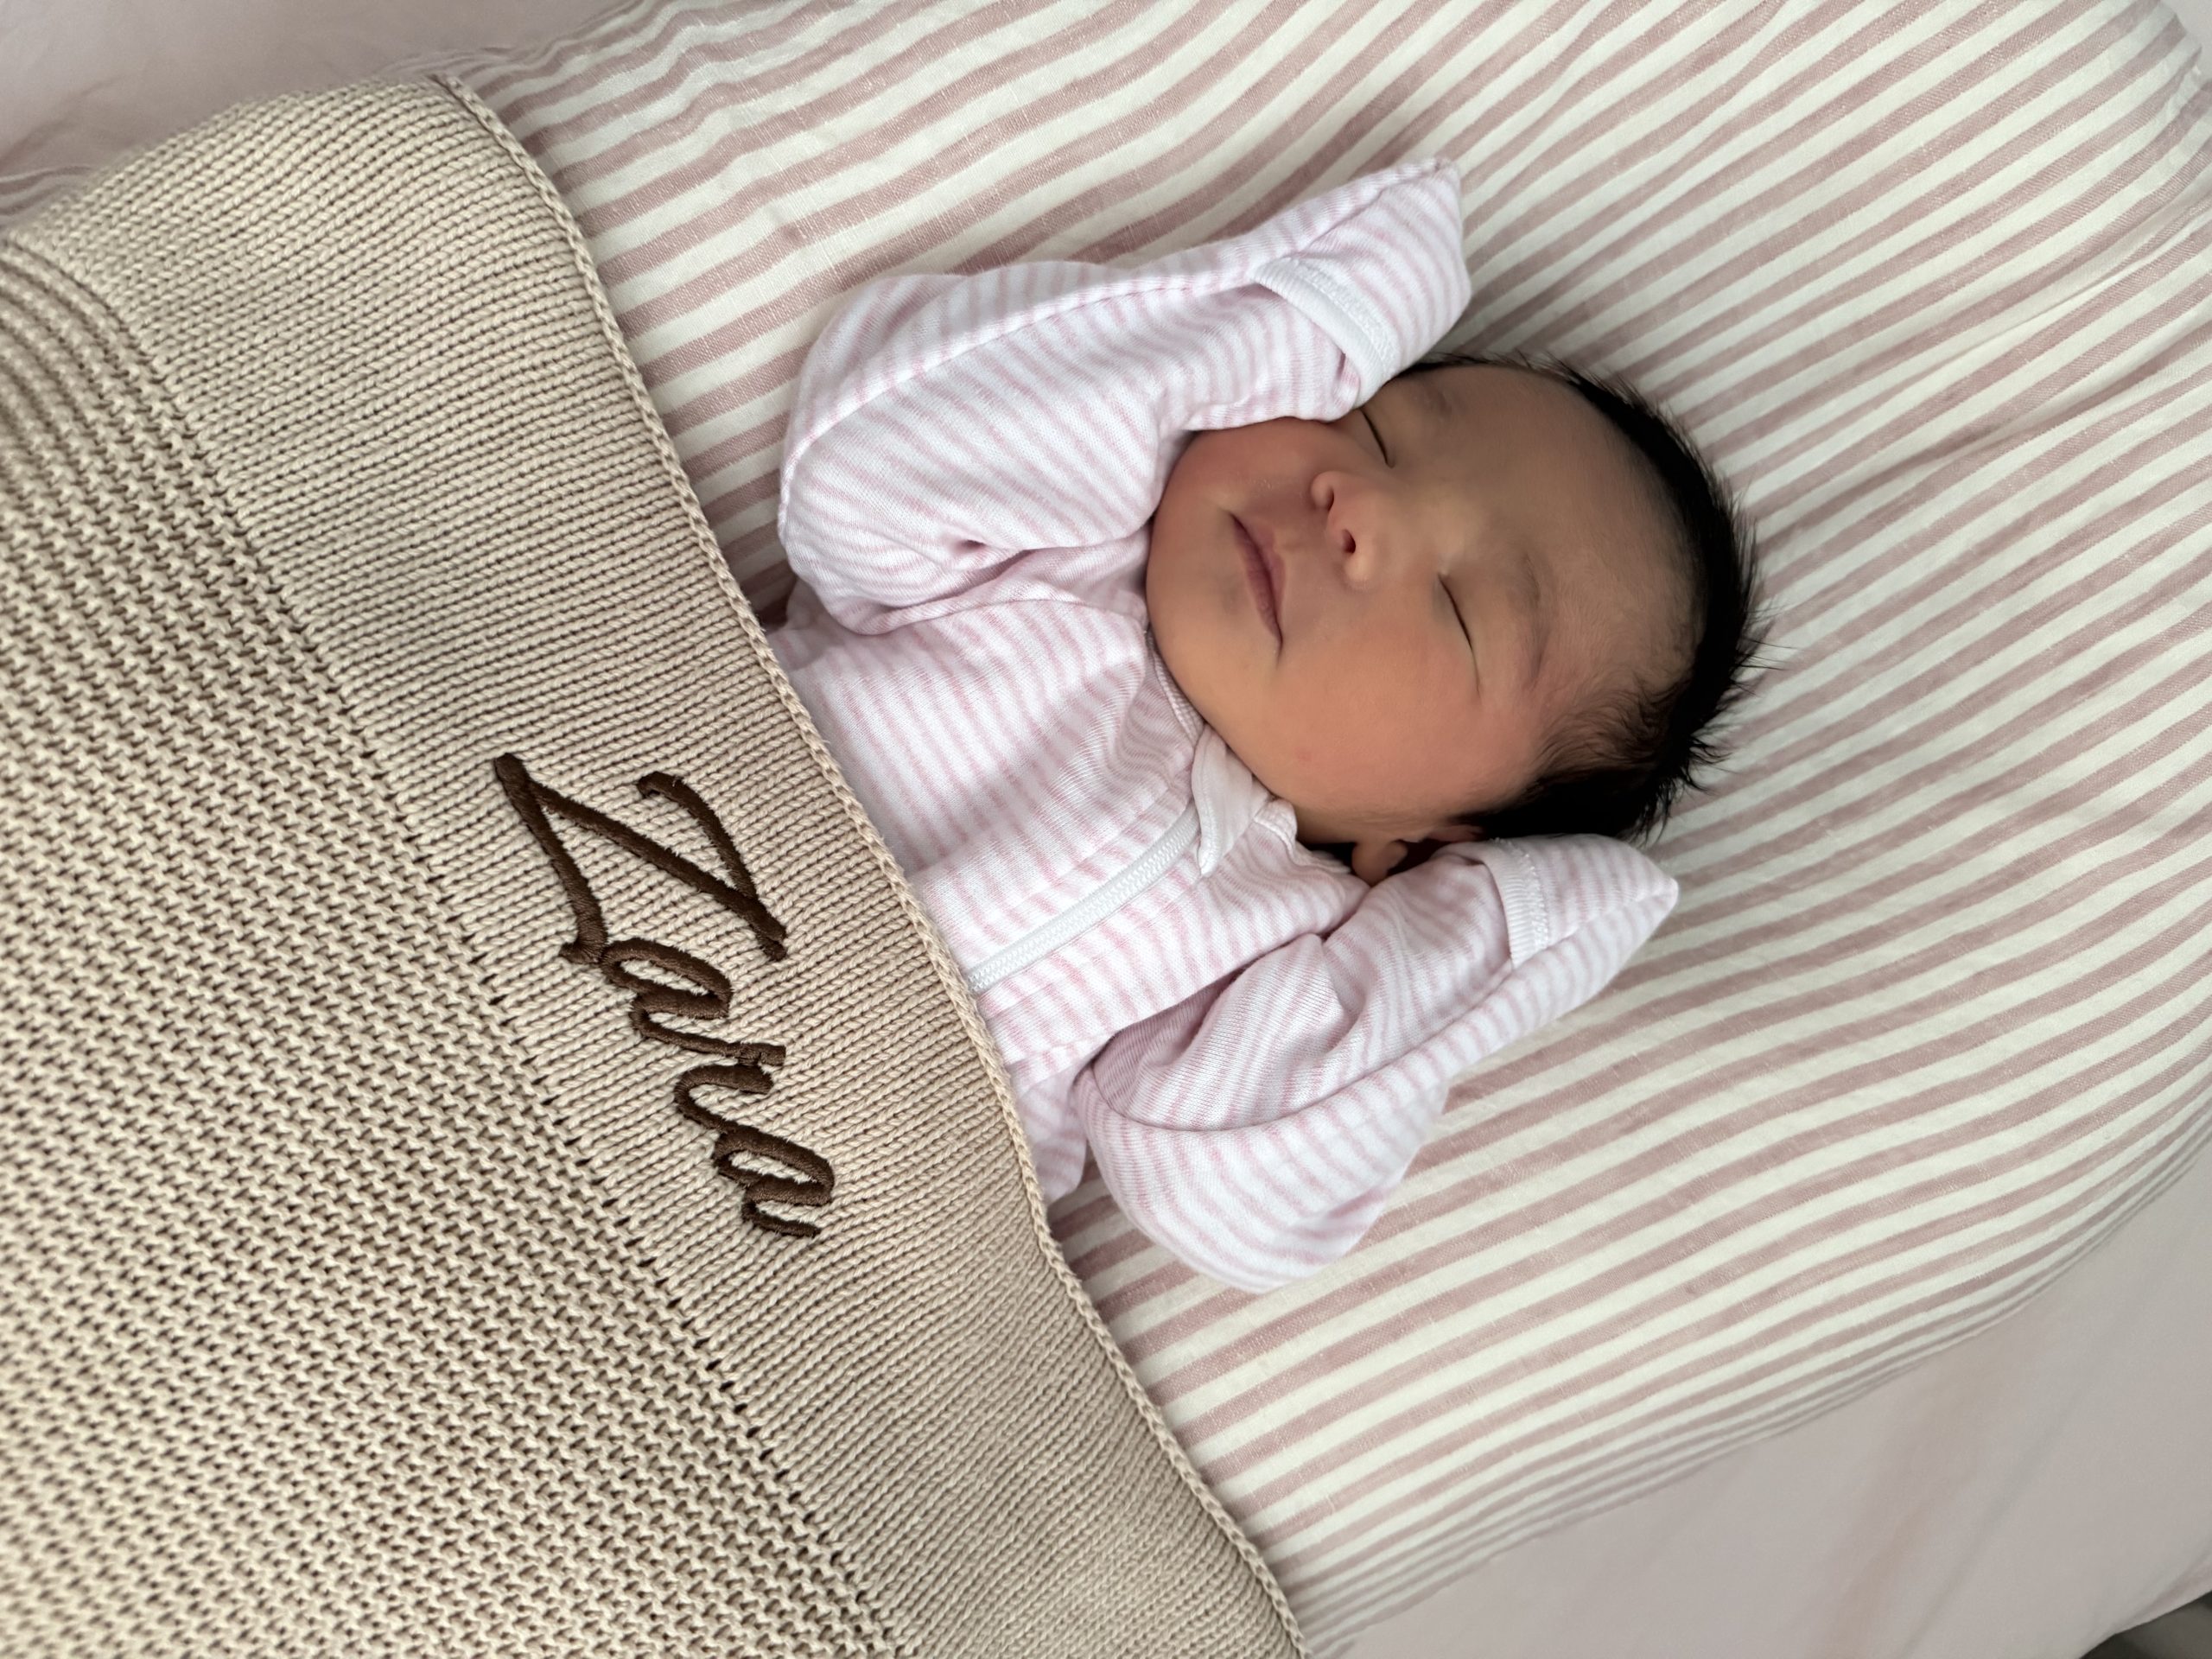
Powerhouse real estate couple Avi Khan and Kaylea Sayer welcome their daughter while balancing record-breaking careers, proving success and family can grow side by side.
From the shacks of yesterday to the sculptural sanctuaries of today, Australia’s coastal architecture has matured into a global benchmark for design.