Wrigley Gum Heir’s Porsche and a Pristine Ferrari Spyder to Highlight Miami Car Auction

 5 min
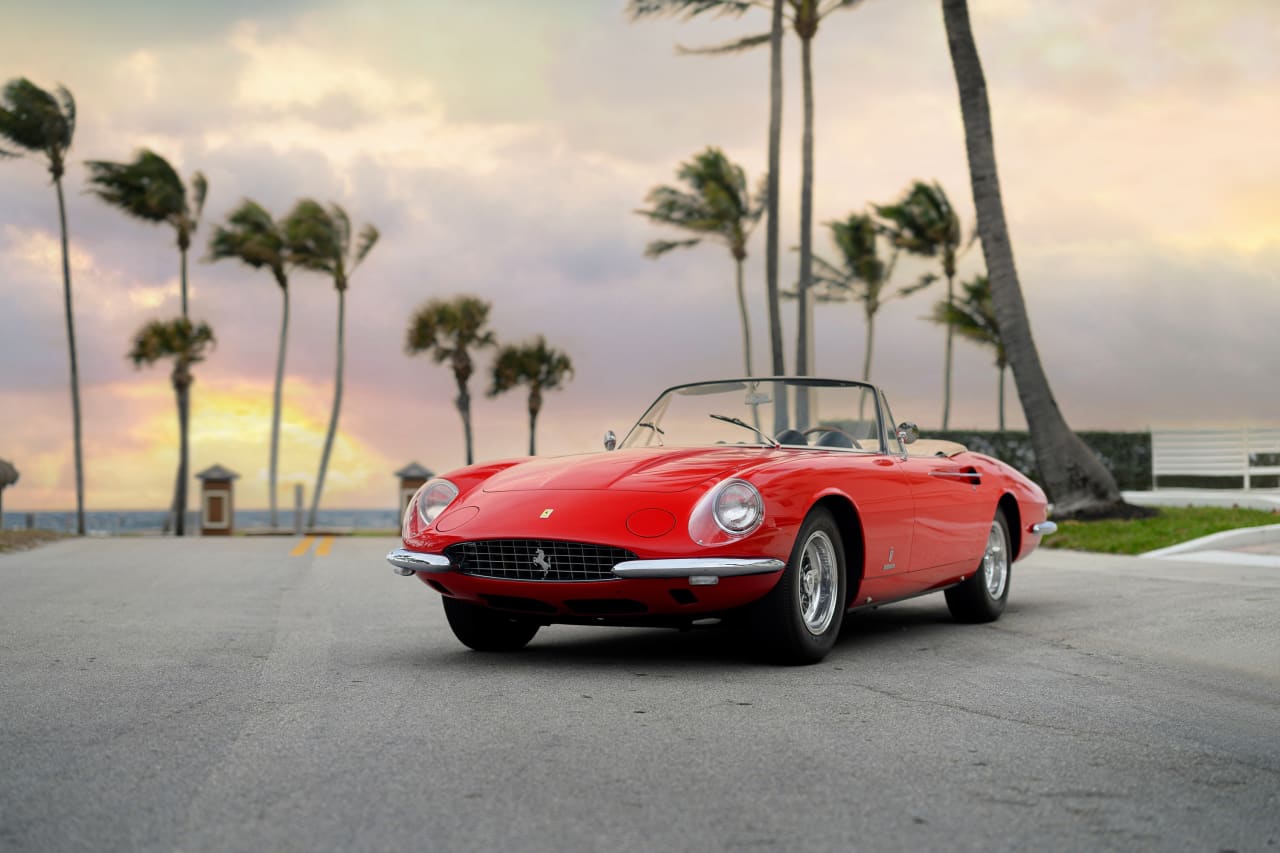
An exceptionally rare 1967 Ferrari 365 California Spyder by Pininfarina, the ninth of just 14 built, will highlight an auction of classic cars and other vehicles in Miami next month.
RM Sotheby’s will conduct a two-day auction from March 1-2 with 119 motor vehicle lots at the first ModaMiami extravaganza. On offer will be boats, motorcycles, and a plane, too.
The Spyder is in exceptionally original condition, with certification from Ferrari Classiche that it retains its matching-numbers chassis, engine, transmission, rear axle, and body. The car is chassis number 9935, completed in May 1967 and in the hands of two long-term owners (four owners total). It was specified with China Red paint and a white-leather interior that matched the Los Angeles-based first owner Nancy Tewksbury’s 275 GTS. The coach-built car was bought by Donald Grove, a Princeton physicist, in 1971. Grove restored the car and kept it for 27 years. The Spyder is estimated to achieve between US$4 million and US$4.5 million.
RM Sotheby’s
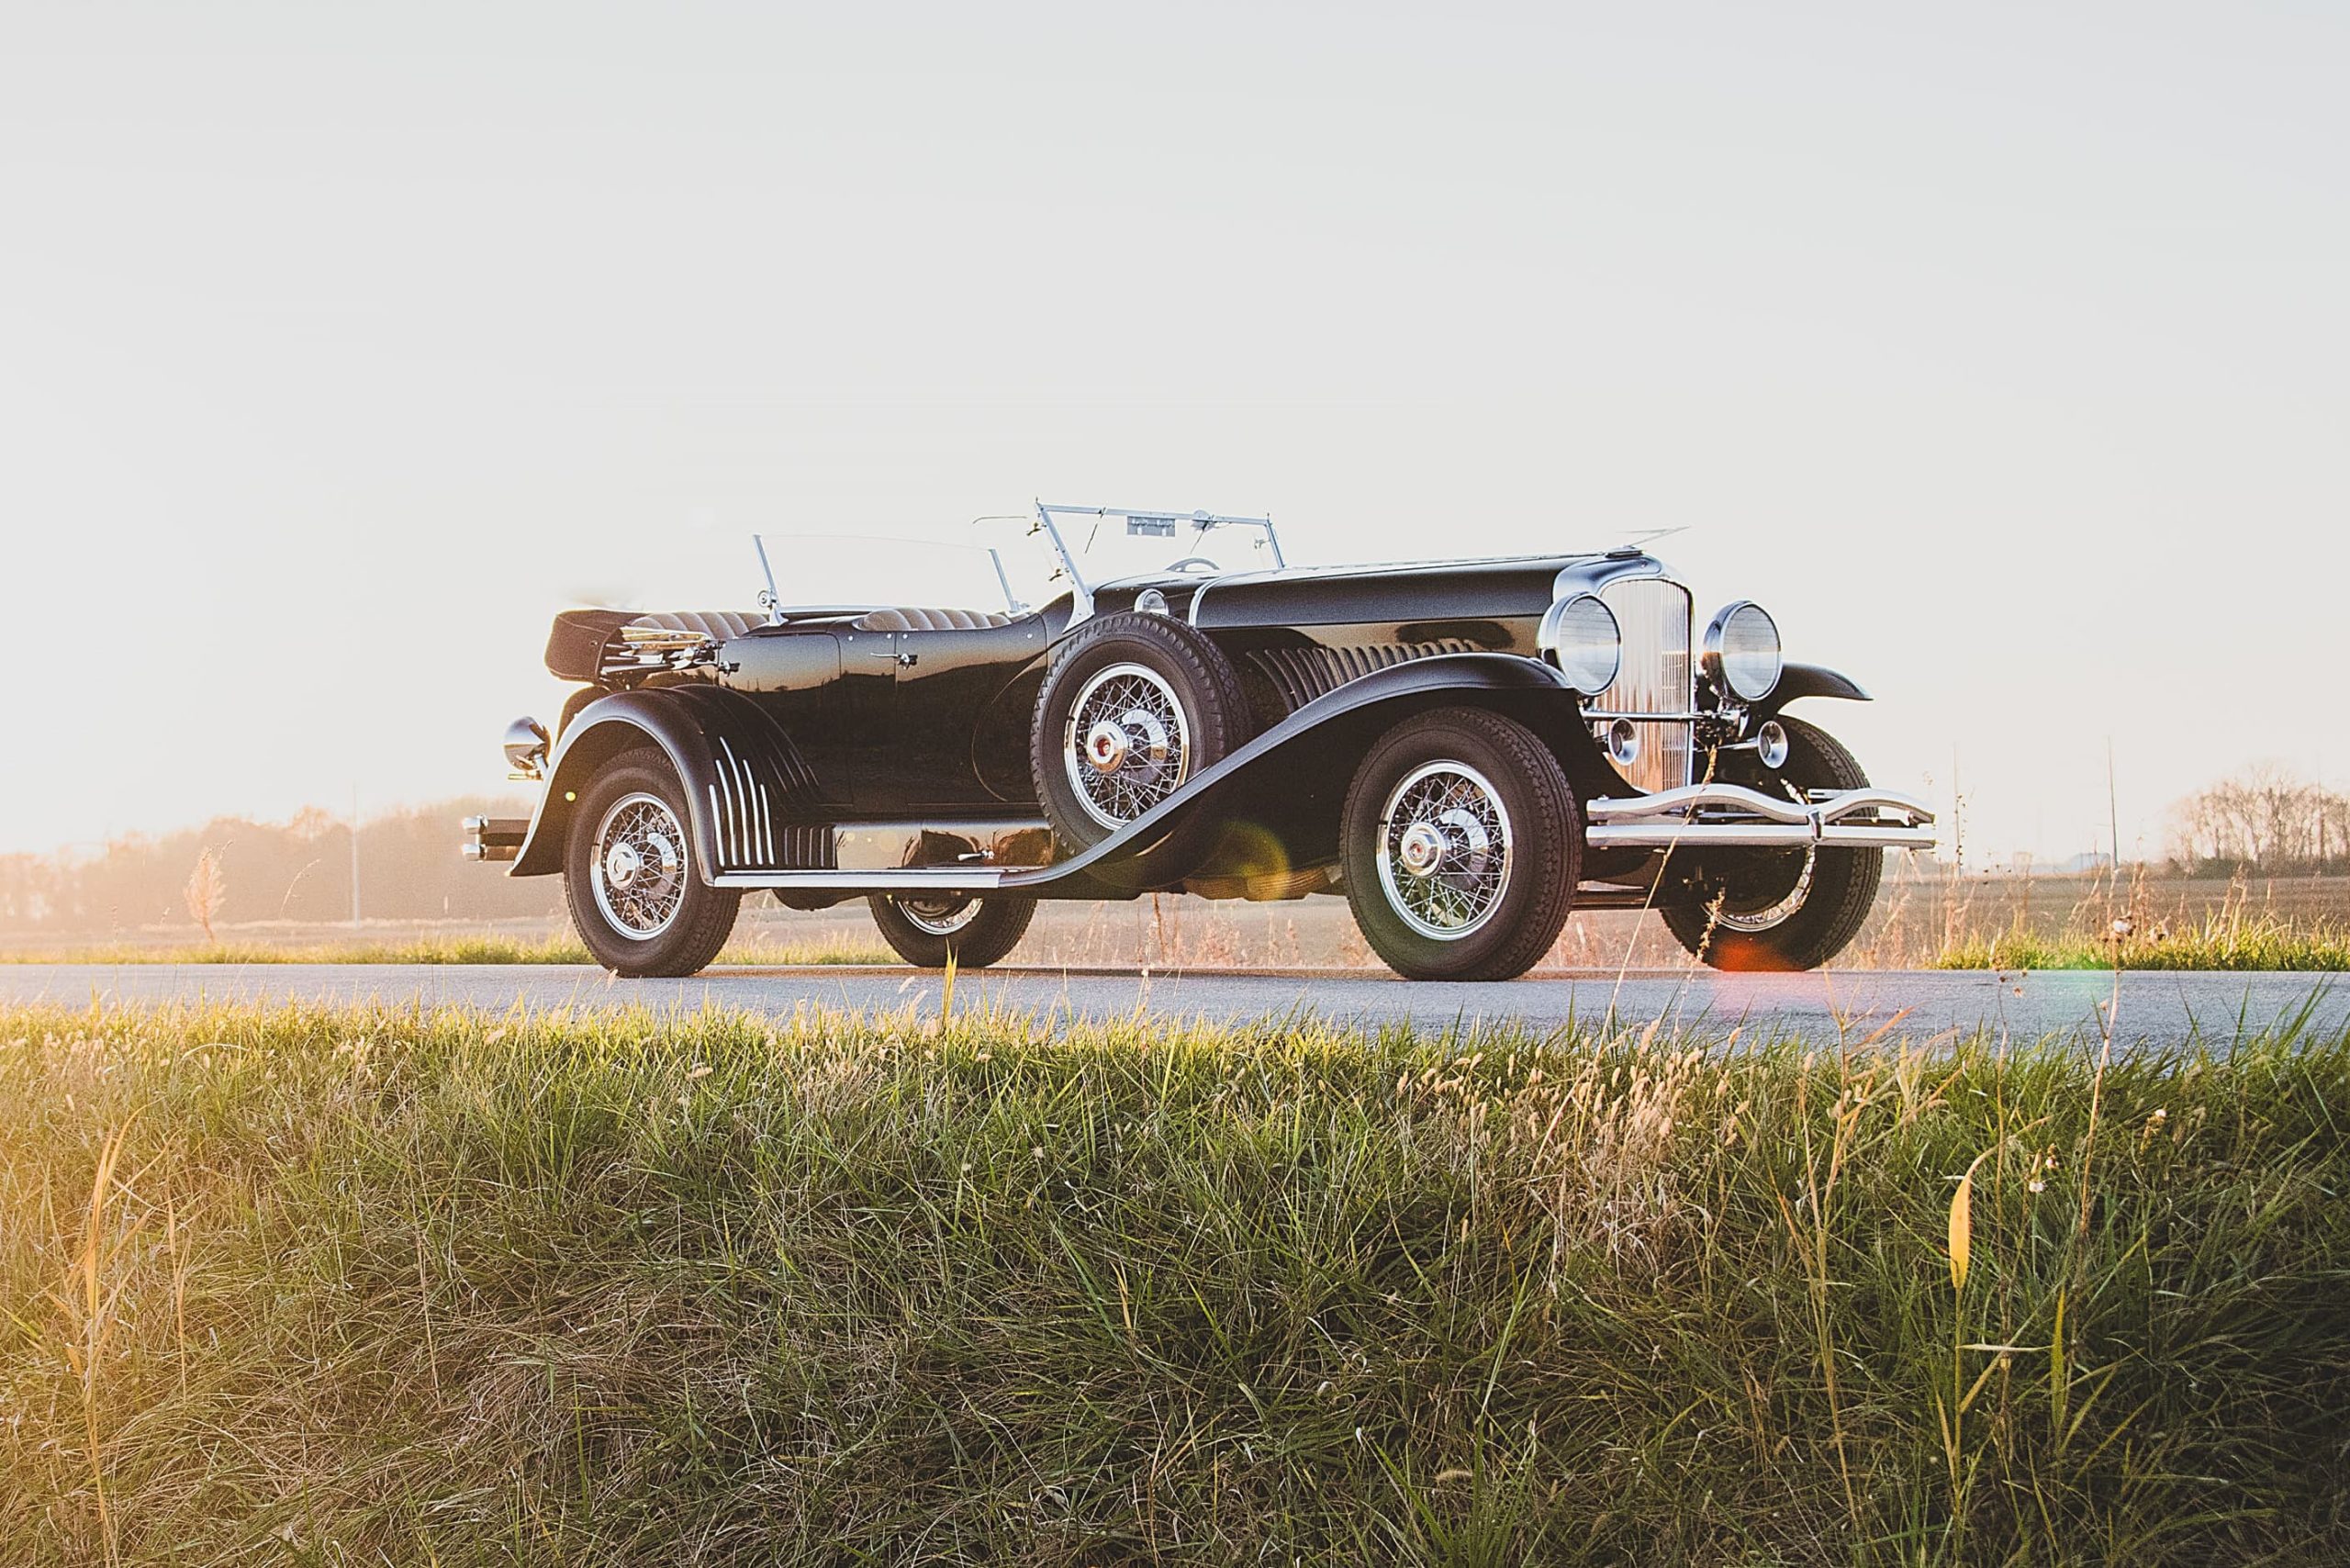
Another notable car at the auction will be a 1929 Duesenberg Model J “Sweep Panel” dual-cowl phaeton with coachwork by LeBaron. The car’s original owner was Phillip K. Wrigley, who took over the famous chewing gum company (and the Chicago Cubs) from his father, William Wrigley, Jr. The younger Wrigley traveled to the Duesenberg factory in Indiana to see his car being built. It is chassis 2177 with engine J-121, originally with a Murphy body.
After a year and 10,400 miles, Wrigley decided he preferred the dual-cowl LeBaron phaeton body on a friend’s car better, and so he retained his original chassis but swapped on the LeBaron body. It was the kind of thing that was possible on cars with body-on-frame construction. The Duesenberg is estimated to achieve between US$2.65 million and US$2.85 million.
RM Sotheby’s
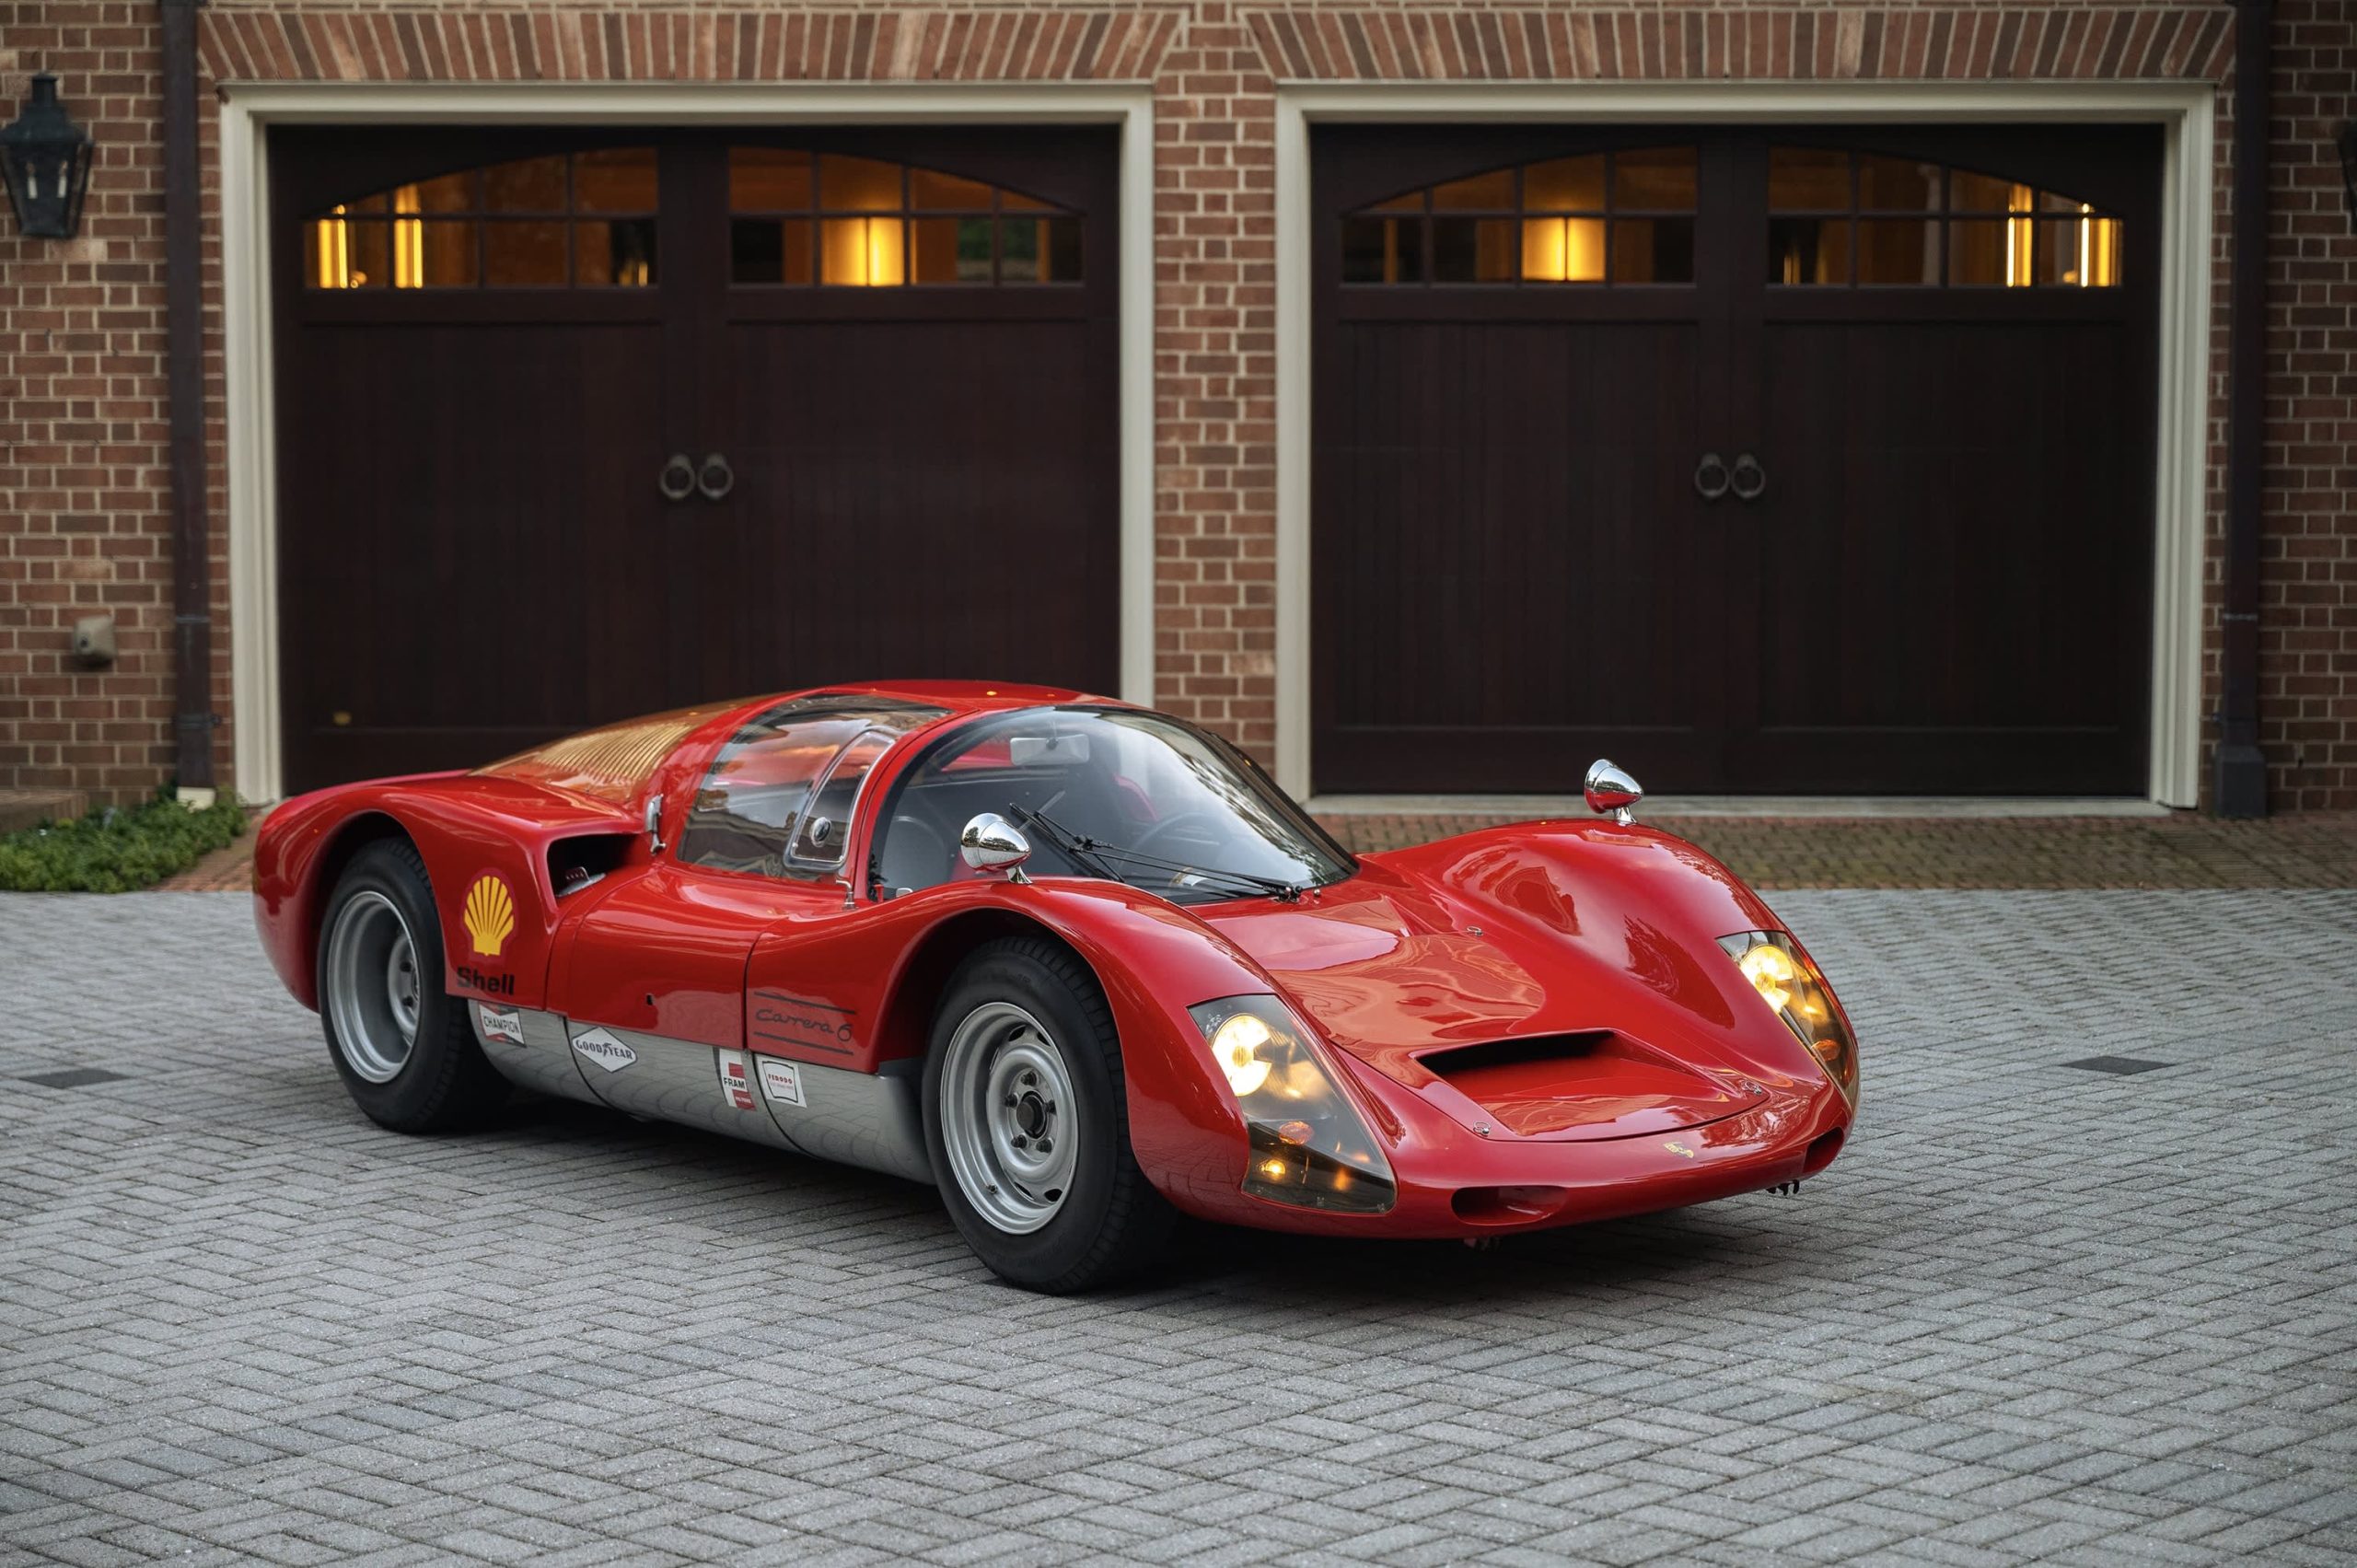
From the racing side of things comes a 1966 Porsche 906 Carrera S with competition history, initially driven by first owner Josef “Sepp” Greger. The car ran to victory in the two-litre class at the European Hillclimb Championship in 1966 and the European Mountain Championship in 1968. Under new owners, it competed in other German races in 1971 and 1972, then went to Macau, where it also raced but did not finish. It took part in some 80 races (achieving more class wins than any other 906) and was even used briefly as a road car. Under New York owner Jean Goutal, who bought the car in 2003, it was finally fully restored by Porsche racing specialist Kevin Jeanette’s Gunnar Racing. After three years of work, the Carrera is now virtually as-delivered, with many period details. The estimate is between US$1.8 million and US$2.8 million.
RM Sotheby’s
Other special cars in the RM Sotheby’s Miami auction include:
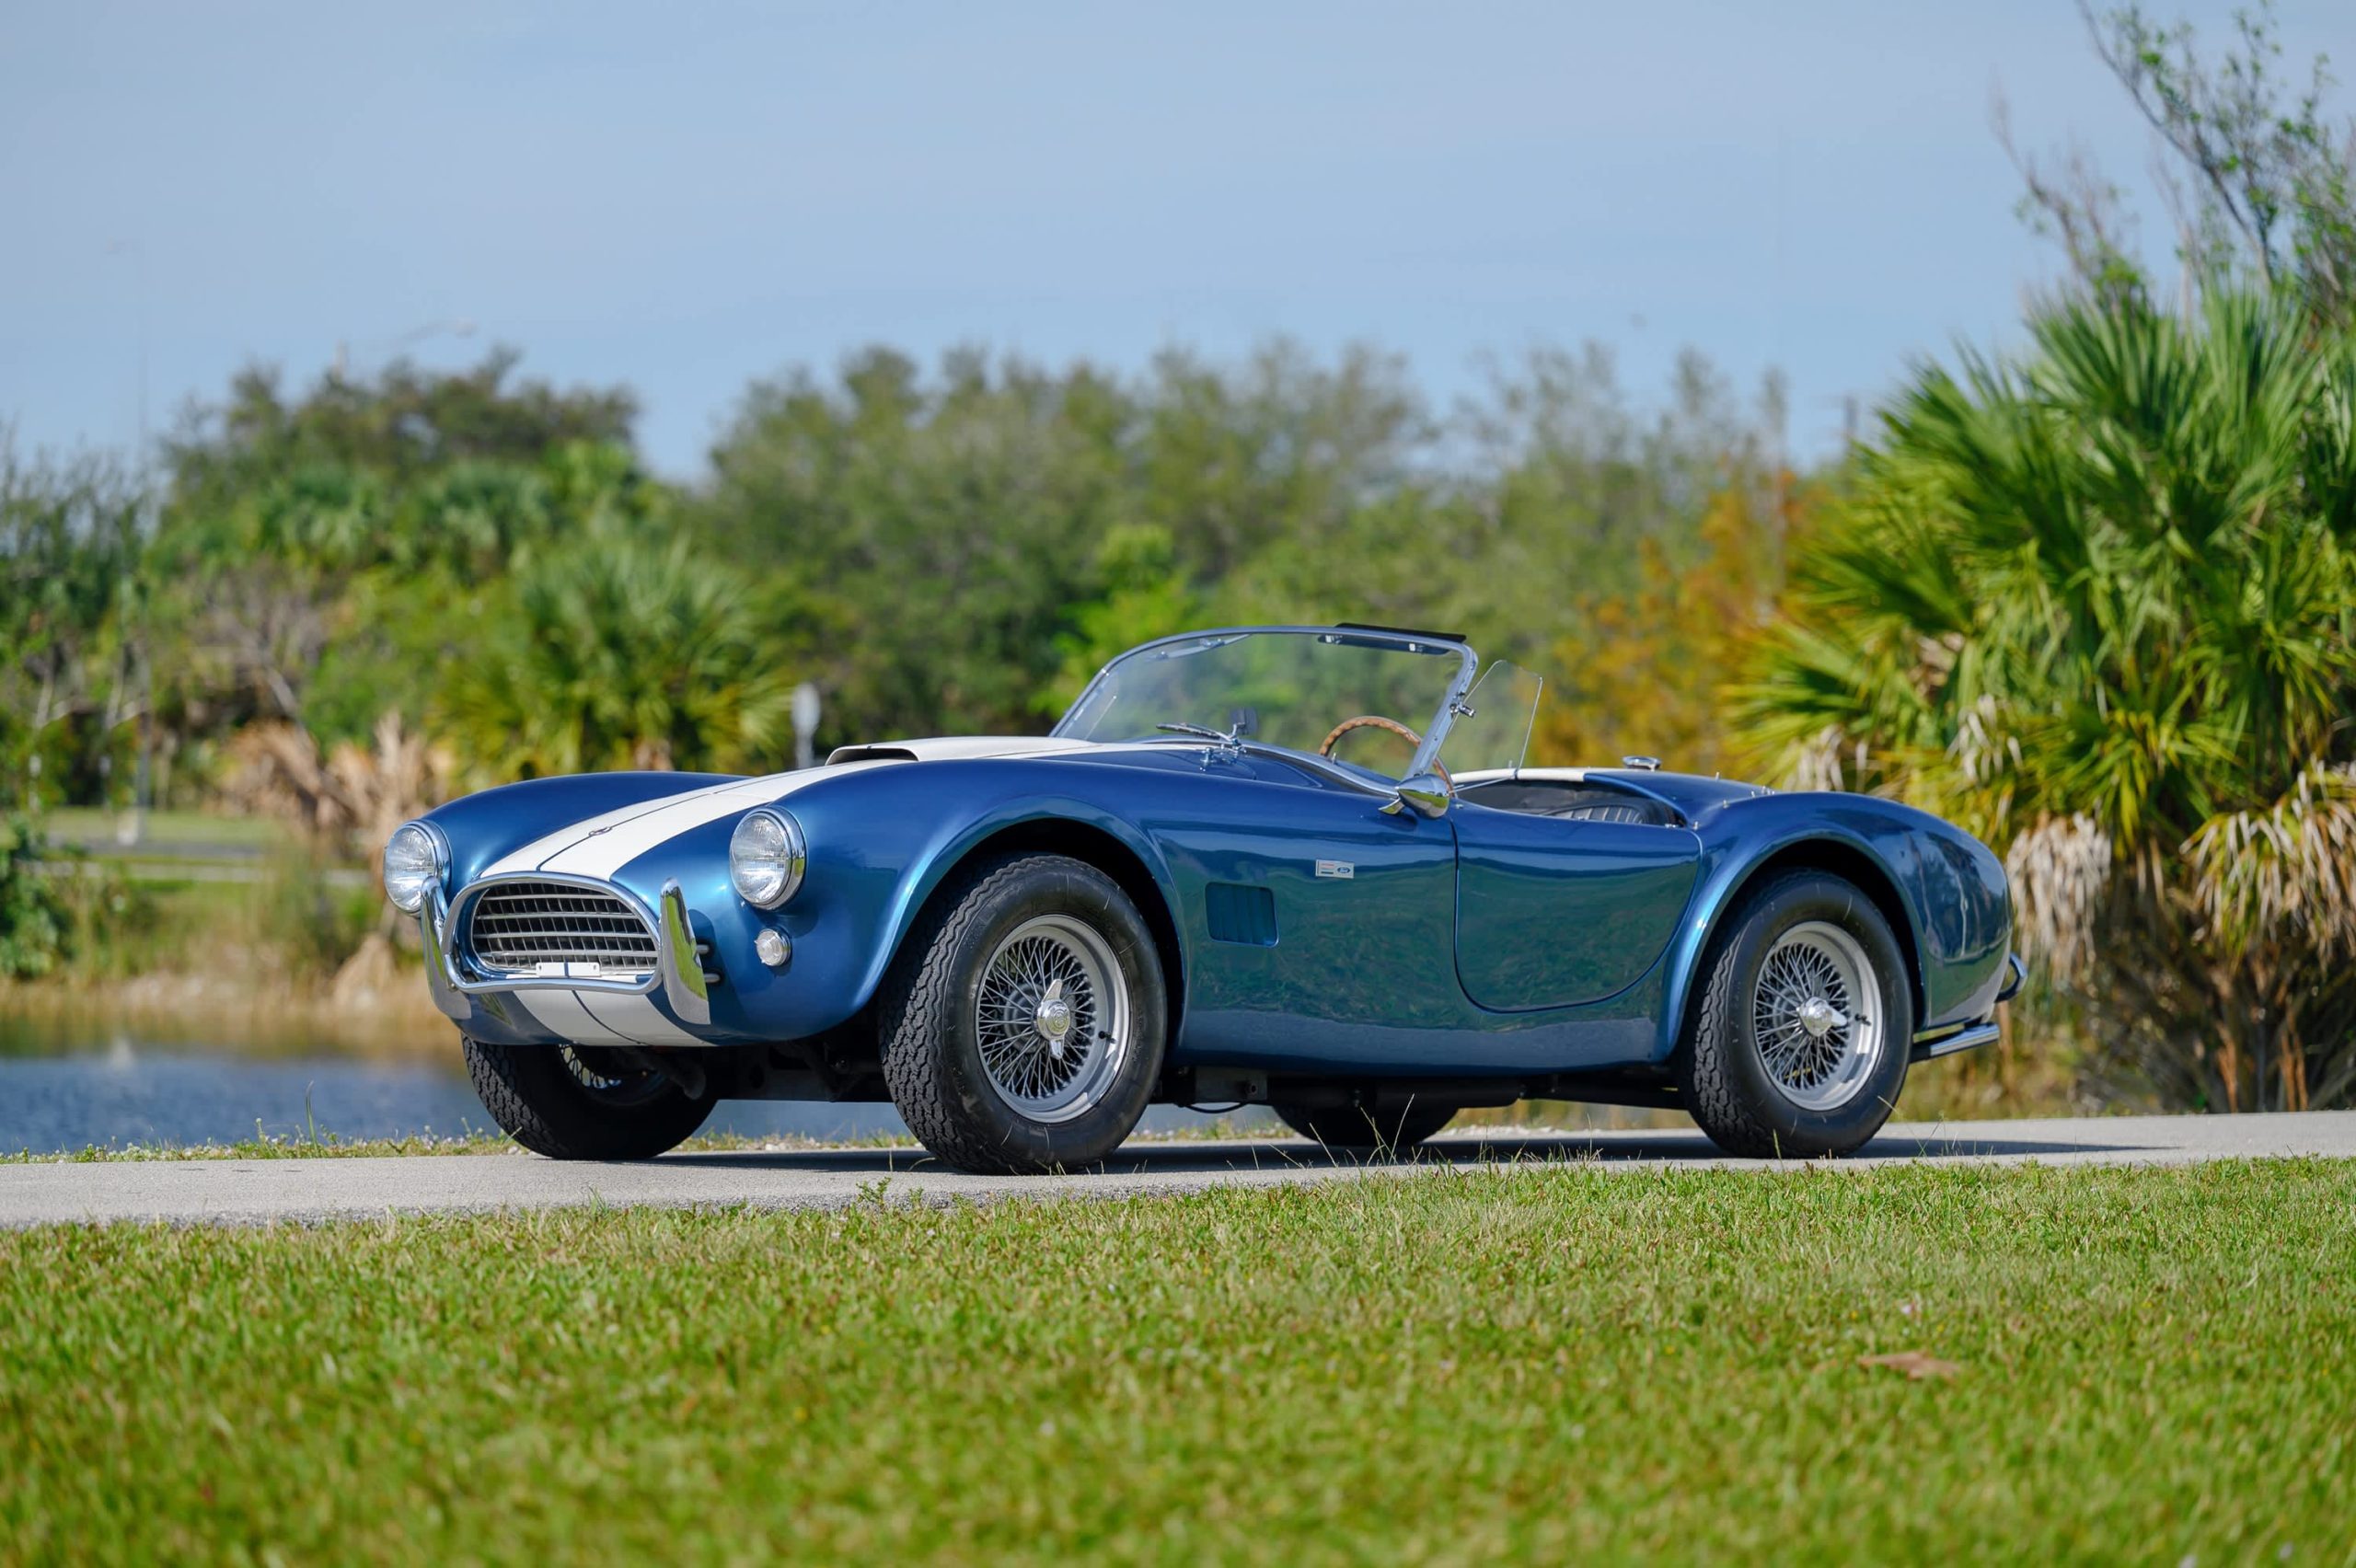
— The 1964 289-powered Mark II AC Cobra is a late production model with rack-and-pinion steering and a pair of dual-barrel carburetors from the factory. The car retains its original engine, which offers 271 horsepower. Originally sold in Illinois and then Ohio, the car was on the cover of the first Cobra World Registry in 1974. The Cobra was repainted in the 1980s in its current classic blue with white stripes. After extensive service in 2022 by Cobra specialist Rare Drive in New Hampshire (including a rebuild of the brakes and suspension) it is ready for the road. The car has never been in an accident or had extensive modifications. It’s estimated at US$1.1 million to US$1.3 million.
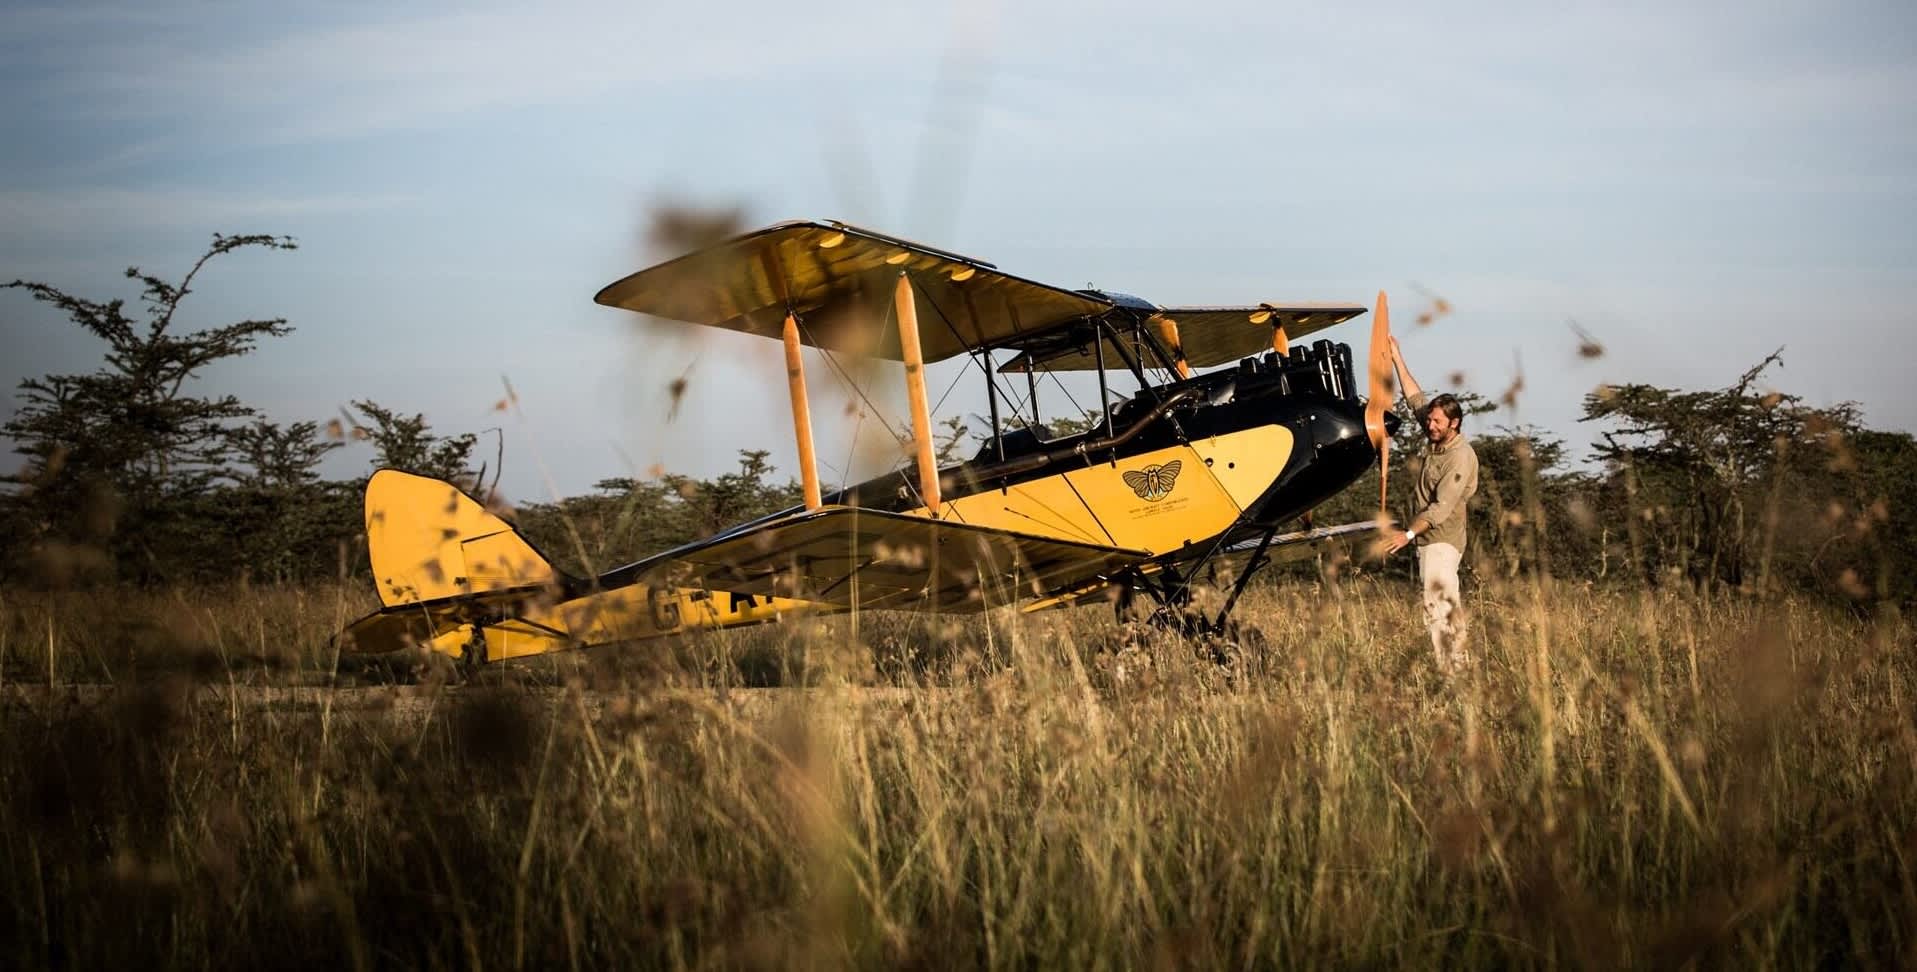
— The 1929 De Havilland DH60GM Gipsy Moth is a restored airplane from the early days of aviation that was used in the making of the 1985 hit film Out of Africa. In keeping with that history, the plane’s sale benefits a rhinoceros sanctuary in Kenya. This all-metal Gipsy Moth was built under a De Havilland license in the U.S. in 1929. It was then shipped to the UK, where it was eventually registered G-AAMY to celebrate the career of British aviatrix Amy Johnson, the first woman to fly solo from England to Australia in her own Gipsy Moth. In 1985, the plane was dismantled and shipped in two crates to Nairobi by way of Germany. It subsequently appeared in numerous scenes in Out of Africa , which starred Meryl Streep and Robert Redford and is based on the 1937 autobiography of that name by Isak Dinesen (a pseudonym for Karen Blixen). The plane has been regularly maintained and now has an uprated De Havilland Gypsy II engine that makes 135 horsepower, and is said to be eminently air-worthy. The plane is projected to bring US$140,000 to US$220,000.
RM Sotheby’s
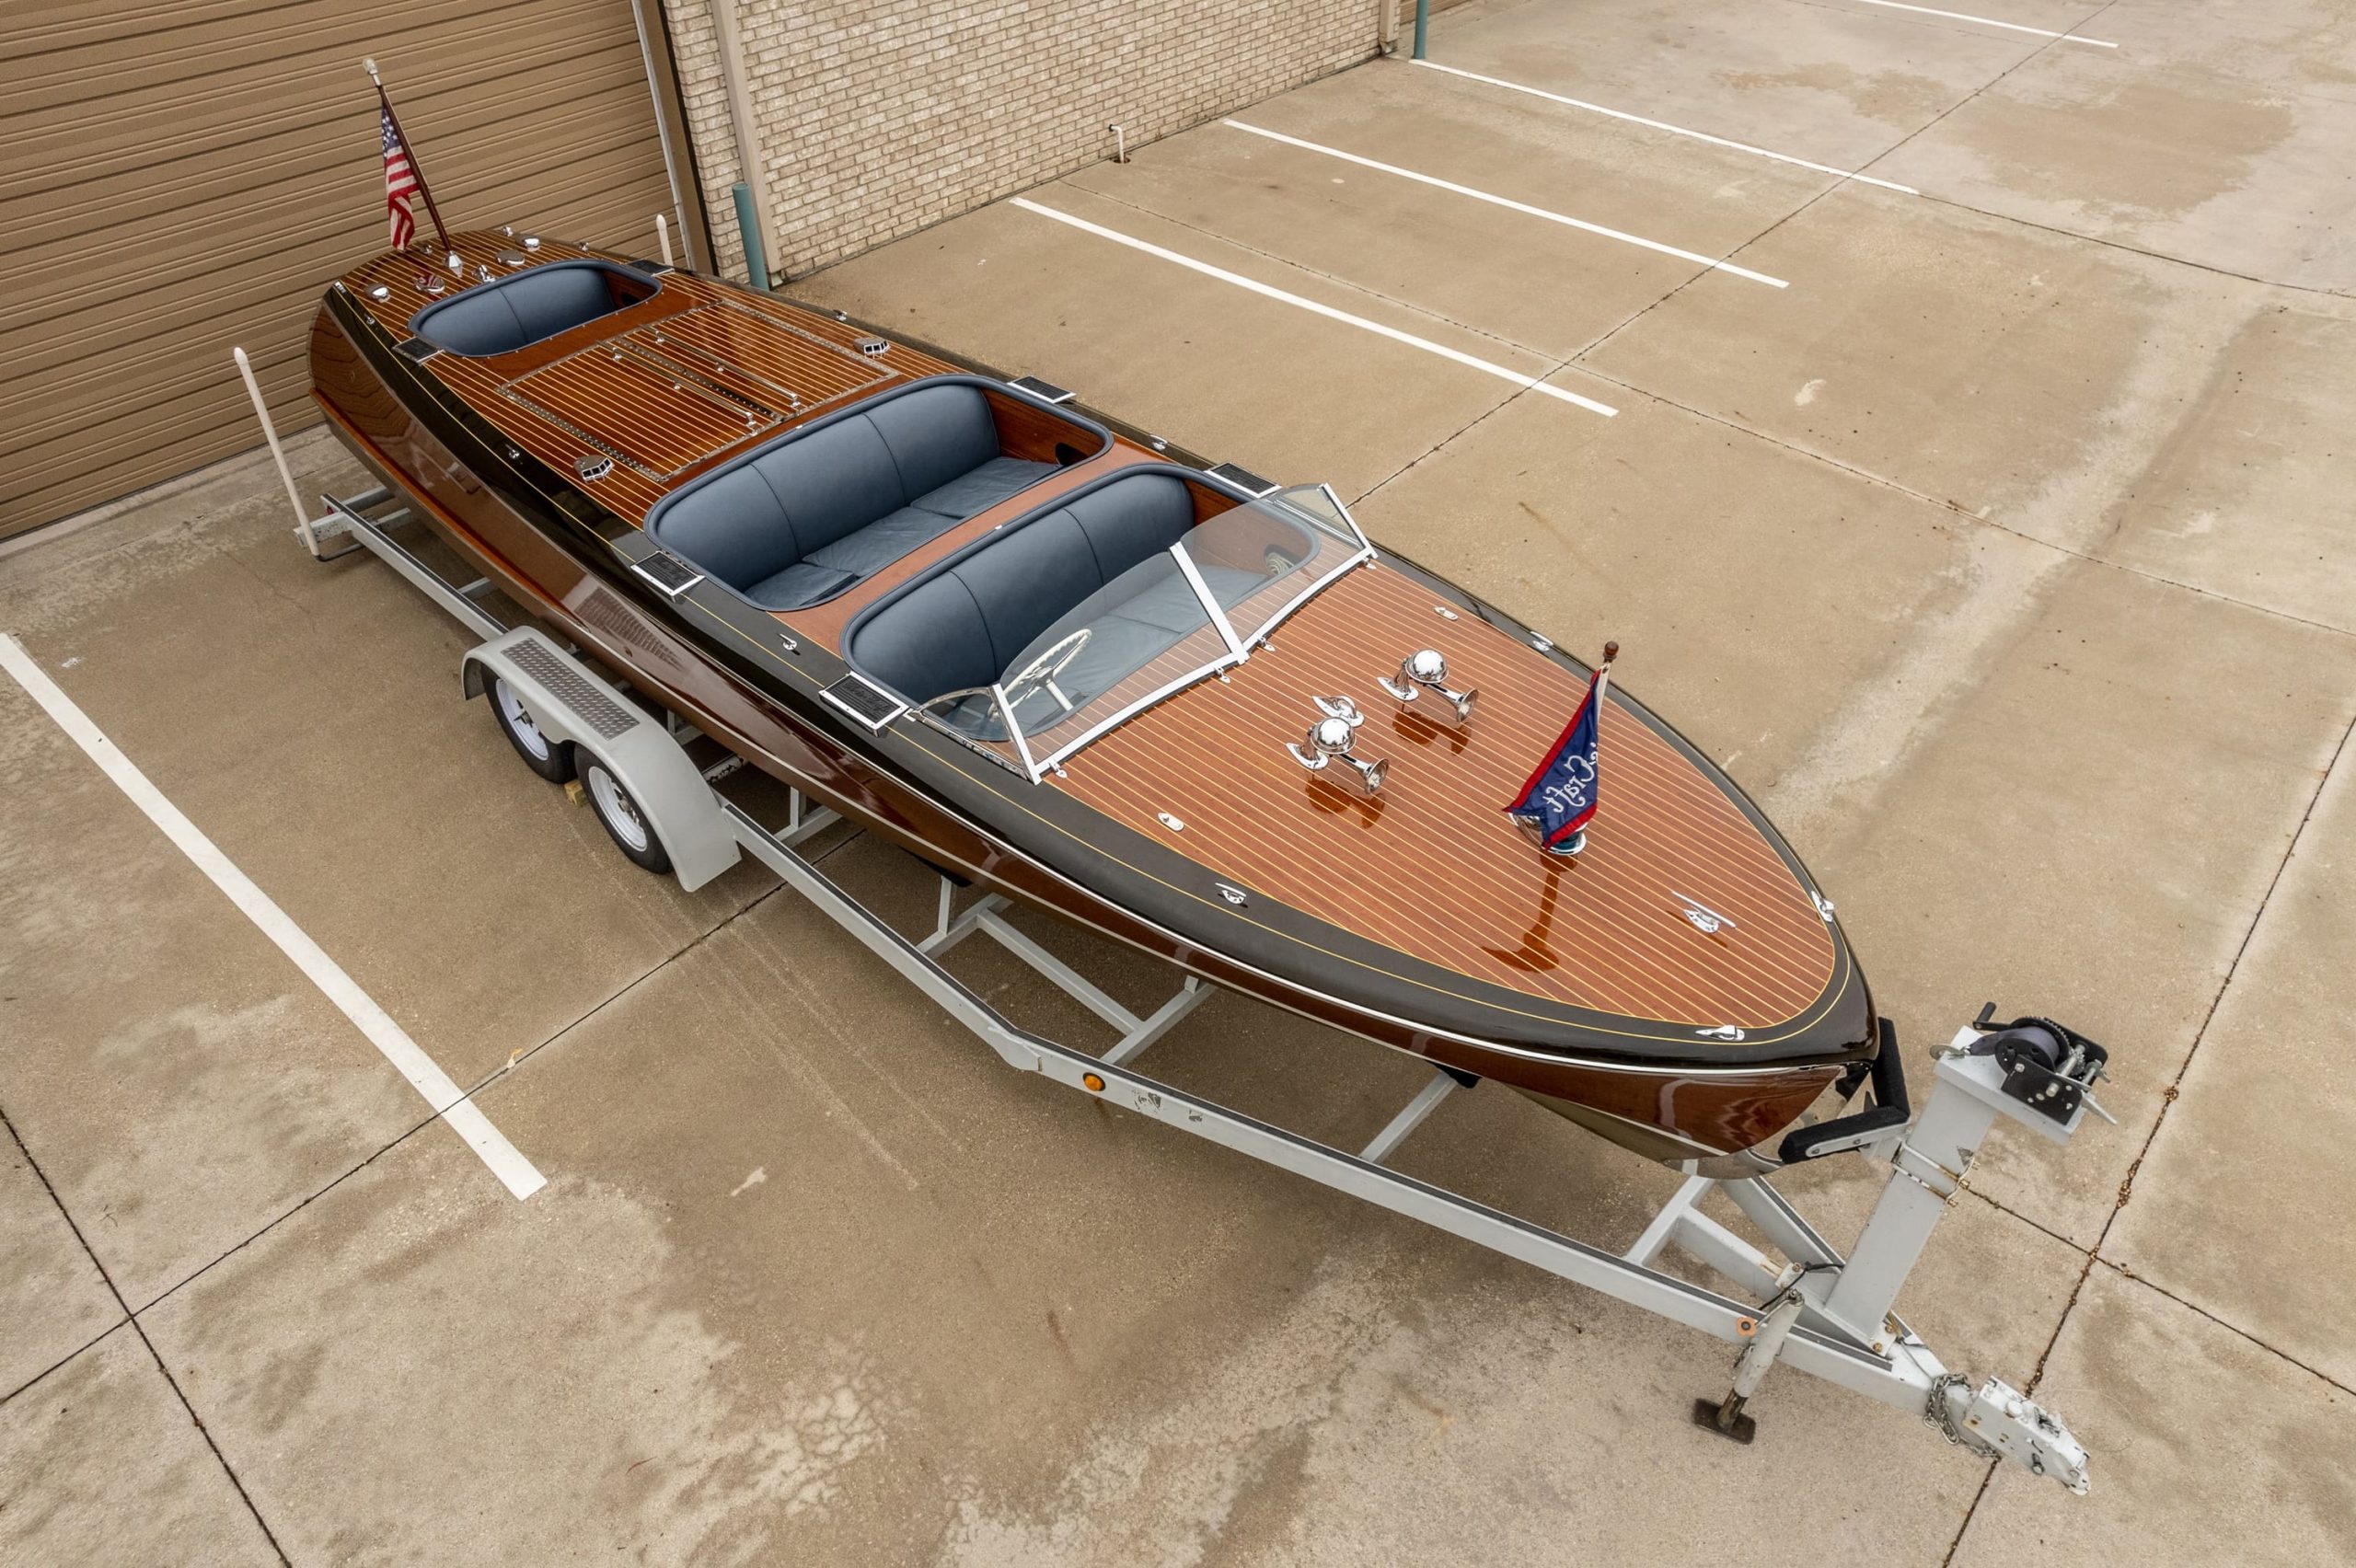
— The 27-foot 1941 Chris-Craft Model 115 Custom Runabout “Runaway Jane” is the only survivor of three of these triple-cockpit wooden boats built that year. It was restored by Michigan experts in 2002 and has been sympathetically maintained since then. Power now comes from an 8.2-liter Mercruiser V8 with more than 300 horsepower, considerably enlivening the original performance. Only 62 examples of this 27-foot craft were built over a 10-year period.The low estimate is US$175,000 and the high US$225,000.
RM Sotheby’s
There are, of course, many other vehicles being sold, including a series of BMW M cars, and classic Mercedes, including examples of the 540K, the 770K, and the 300SL.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
Odd Culture Group brings a new kind of after-dark energy to the CBD, where daiquiris, disco and design collide beneath the city streets.

The sports-car maker delivered 279,449 cars last year, down from 310,718 in 2024.