Central Banks Are Stuck in a Rinse-and-Repeat Cycle of Crises
Central banks’ efforts to keep markets stable may be creating unintended risks. Emergency lending and market backstops have encouraged highly leveraged government bond trades, potentially lowering borrowing costs while increasing financial vulnerabilities that could require further intervention during the next crisis.

 4 min
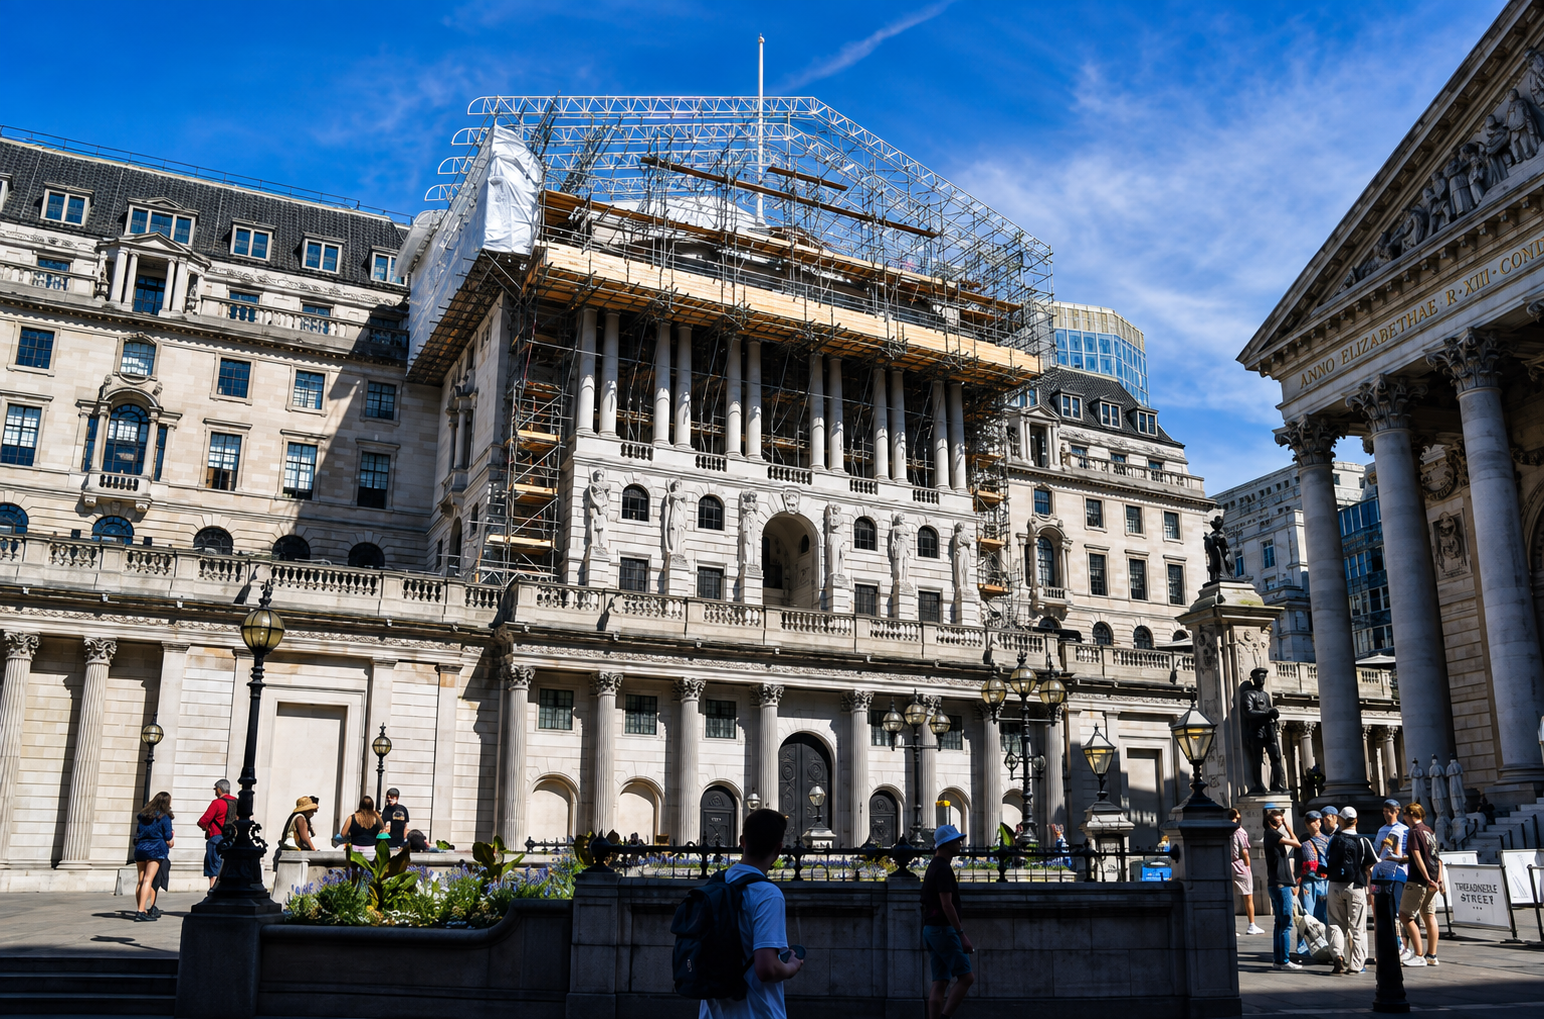
Central banks may be accidentally subsidizing government borrowing through their efforts to prevent a repeat of past market blowups, and policymakers are starting to worry that anticrisis lending facilities could even be interfering with their own monetary policy.
The source of the problem is the switch from central banks being the lender of last resort to, in 2008 and 2020, also being market makers of last resort, ensuring corporate—and government—debt markets keep functioning. During a crisis, support is often essential to prevent a downward spiral that destroys the financial system.
But backstopping markets removes a key risk and encourages more borrowing—especially for the hedge funds that now own trillions of dollars of U.S. Treasurys.
“Ironically, vulnerability is created by mechanisms that were introduced to reduce vulnerability,” said Huw Pill, the Bank of England’s chief economist, one of those growing concerned, in an interview. “So, it’s a bit like a whack-a-mole kind of story.”
Offering either an explicit or implied guarantee that government-funding markets will remain open and liquid means hedge funds have less risk of being unable to finance highly leveraged trades. This is particularly true for the overnight repurchase, or repo, market, where borrowers pledge bonds for cash. The result has been a huge expansion of two popular government bond trades, arbitraging Treasurys or British gilts against bond futures or swaps.
The scale is extraordinary: The Dallas Fed estimates hedge funds ended last year with $2.4 trillion of Treasurys, up from $600 billion a decade earlier. Because the profits on each trade are tiny, hedge funds have to leverage as much as 100 times to get worthwhile returns, creating new risks.
This might sound abstruse. But in 2020, it was the Treasury basis trade blowing up that forced the Fed to intervene. In 2025, signs of trouble in the swap trade pushed President Trump to retreat from his tariff plan.
Pill worries that the reassurance central-bank policy provides bleeds into monetary policy by boosting borrowing. This, in turn, keeps government-debt yields lower than they otherwise would be.
“There’s lots of gilts to be bought,” he says. “How do you support that buying of gilts? You make it attractive. How do you make it attractive? Well, there are some imperfections in the market. So those imperfections create profit opportunities, but they’re not very big. So how do you make them more meaningful? You allow leverage to build up.”
“That’s good for the government because it gets to sell the gilts at a lower [yield] than it otherwise would. It’s good for the financial sector because they’re able to extract these rents effectively. And it’s good for the central bank because the market seems to be liquid and functioning. But all of those things are true until they’re not true.”
When it goes wrong, the more leverage, the worse the problem. And the worse the problem, the more likely it becomes that central banks have to create yet more special tools to address it. That then spurs the next buildup of leverage.
Pill thinks more effort is needed to come up with a modern version of the Bagehot Doctrine. Walter Bagehot, the 19th-century editor of the Economist magazine, summed up the role of the central bank as being to lend to banks freely, against good collateral, at a penalty rate. Access to instant cash helps banks withstand runs. The fact the central bank is offering a backstop should make the run less likely, and shareholders are penalized, through the penalty rate, if it is used.
Tools for saving markets from drying up are more haphazard. In 2020 the Fed, BOE and others just bought lots of government debt to inject liquidity into markets. That worked because, even though quantitative easing is also a monetary policy tool, they also wanted easier money.
Unfortunately, that created what Pill described as a tinderbox, ignited by the energy crisis after Russia invaded Ukraine. The excess money creation from left over from emergency QE then fanned the flames of inflation. This made it much harder to calibrate monetary policy when central banks decided to tighten (although policymakers were also, in my view, far too slow to recognize inflation).
Pill points to the “temporary, targeted” BOE buying of gilts amid the forced selling by leveraged pension funds after Britain’s botched tax-cut plan in September 2022 as a successful model. At a time when the BOE was trying to tighten monetary policy, it intervened in a way that stopped the pension fund selling spiral and stabilized gilts. Yet the central bank maintained tight monetary policy.
Bagehot would recognize the goal: Reduce the encouragement to take risk, known as moral hazard, that offering guarantees in advance creates, but retain the ability to mount a rescue in a crisis.
Unfortunately, much of central banking is going backward on this. Moral hazard is increasing, even for banks. In the 2023 bank bailout, the Fed accepted less-than-full collateral, recognizing Treasury bonds at face value rather than their (much lower) market value.
The emergency rescue facility then became a funding facility that even healthy banks chose to tap—in effect easing monetary policy by the back door and prompting the Fed to tighten the terms before it ended. Something similar could be under way with Japan’s plans to use an emergency Fed loan facility to raise cash to prop up the yen without having to sell its hoard of Treasurys.
I don’t know how to break the cycle of crises needing rescues that lead to more leverage and new crises. And I’m concerned we’re firmly into the added-leverage phase of the latest cycle.
At least central bankers are still thinking about it, even if they don’t, so far, have good answers.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
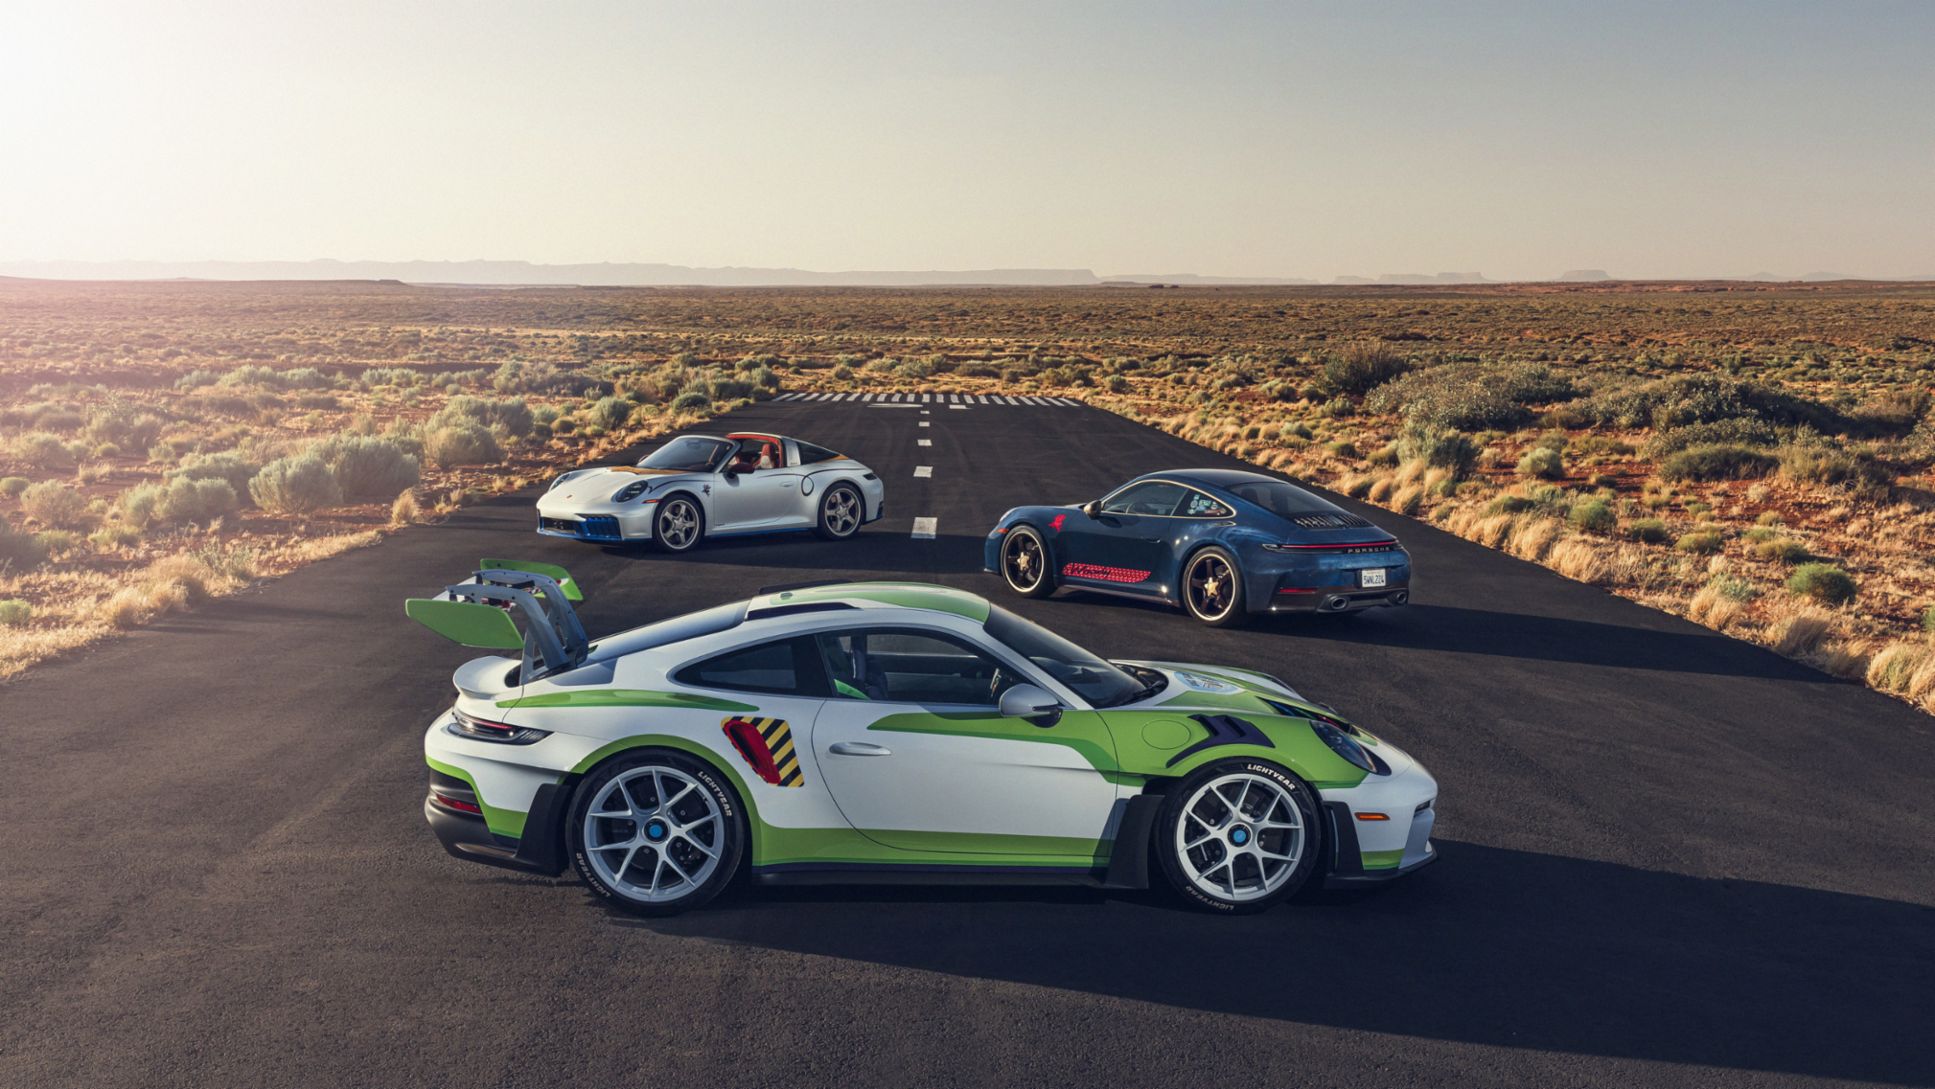
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations
5 min
Reporting season has once again reminded investors that a strong profit does not guarantee a rising share price, and a large loss does not always trigger a sell-off. What matters most is how each result compares with expectations and, increasingly, what management says about the year ahead. During the August 2026 season, companies offering credible turnarounds or unexpectedly strong guidance were rewarded handsomely, while those flagging weaker margins, slowing demand or greater uncertainty were punished.
The following ranking draws on Morningstar’s review of 164 ASX-listed companies and measures each company’s share-price movement on the day it reported. This captures the market’s immediate response to the earnings announcement, before subsequent economic developments, dividends and company-specific news cloud the picture. Here are the five biggest winners, and the five hardest-hit losers, of the season so far.
The five winners
1. Bapcor (ASX:BAP): +41.0%
Bapcor delivered reporting season’s largest relief rally after presenting early evidence that its troubled automotive-parts business was stabilising. Although underlying revenue fell 1.8% to $1.92 billion and underlying NPAT collapsed 85% to $10.8 million, underlying EBITDA of $152.5 million exceeded guidance.
More importantly, working-capital initiatives released $68.5 million in the second half, lifting cash conversion to 109.4% and reducing net debt by 63% to $135 million. The statutory loss was $431.6 million, largely because of non-cash impairments. Investors focused on improving operational momentum, stronger liquidity and management’s expectation of modest FY27 revenue growth.
2. Zip Co (ASX:ZIP): +18.2%
Zip comfortably surpassed its FY26 targets, sending the buy-now-pay-later provider’s shares sharply higher. Transaction volume rose 23% to $16.7 billion, while cash earnings before tax, depreciation and amortisation jumped 58% to a record $268.9 million. Statutory profit climbed 46% to $116.4 million, and the cash operating margin expanded by 4.2 percentage points to 20%.
The strongest signal was guidance for FY27 cash earnings of $340 million—around 26% growth and above analysts’ forecasts. US transaction volume increased 42.5% and now represents three-quarters of group volume, offsetting weaker customer activity in Australia.
3. CSL (ASX:CSL): +17.3%
CSL’s result was hardly spectacular in isolation, but it cleared a market bar that had fallen dramatically following earlier downgrades and restructuring announcements. Underlying NPATA was US$3.1 billion, down 2% in constant-currency terms, while operating cash flow reached US$3.51 billion.
CSL maintained its full-year dividend at US$2.92 per share and completed a A$1 billion buyback. The real catalyst was FY27 guidance for approximately 5% underlying profit growth, compared with market expectations closer to 2%. After an extended period of earnings disappointments, investors interpreted the outlook as evidence that CSL’s core plasma business was approaching a sustainable recovery.
4. Judo Capital (ASX:JDO): +16.9%
Judo Capital demonstrated strong operating leverage as its specialist business-lending franchise expanded. Full-year profit before tax rose 34% to $168.1 million, while pre-provision profit increased 42%. Gross loans and advances grew 18% to $14.7 billion, reaching the top of the bank’s guidance range and comfortably exceeding broader system growth.
Deposits increased 24% to $12.2 billion, return on equity improved by 1.1 percentage points to 6.4%, and earnings per share rose 29% to 9.9 cents. Reaffirmation of the FY27 outlook gave investors confidence that loan growth could continue without sacrificing margins or credit quality.
5. Super Retail Group (ASX:SUL): +15.8%
The owner of Supercheap Auto, rebel, BCF and Macpac reported record sales of $4.2 billion, up 3.2%, despite cautious discretionary spending. Profitability went backwards: normalised profit before tax fell 7% to $306 million and normalised NPAT declined 2.8% to $226 million as transformation spending weighed on margins. Nevertheless, the result exceeded subdued expectations, online sales grew 5.3% and membership across the group’s loyalty programs reached 13.1 million. Investors were also encouraged by positive early FY27 trading, stable gross margins and continued market-share gains. A fully franked 33-cent final dividend added to the appeal.
The five losers
1. Hansen Technologies (ASX:HSN): –21.2%
Hansen’s historic result met expectations, but investors recoiled from its outlook. The utility and communications software provider achieved an underlying EBITDA margin of 31%, exceeding its 30% target, while generating strong cash flow. However, management designated FY27 an “investment and transition year”, signalling a roughly five-percentage-point margin contraction as spending on products, sales capabilities and organisational changes increased.
Revenue had already been broadly flat, leaving investors concerned that the investment program would depress earnings before new growth appeared. Leadership changes, including the chief executive’s departure, added uncertainty. Management expects revenue growth and margins above 30% to return in FY28, but the market was unwilling to wait.
2. Life360 (ASX:360): –19.4%
Life360’s headline growth was impressive: quarterly revenue rose 38% to US$159 million, subscription revenue increased 31%, and adjusted EBITDA climbed 53% to US$31.1 million. Monthly active users reached 102.4 million and paying circles grew 27% to 3.2 million. The sell-off reflected expectations rather than a collapsing business.
Net income fell 18%, the net margin contracted from 6% to 3%, hardware shipments dropped 18%, and full-year EBITDA guidance was merely maintained. After a strong valuation run, investors wanted a larger upgrade and clearer evidence that heavy investment in advertising, international expansion and artificial intelligence would generate additional earnings.
3. PEXA Group (ASX:PXA): –17.0%
PEXA reported a 7% increase in continuing-operations revenue and 12% EBITDA growth to $152 million, accompanied by a two-percentage-point margin expansion. Free cash flow increased 39%, suggesting the core Australian electronic-conveyancing platform remained highly profitable. Investors instead concentrated on management’s warning that property-transfer volumes could decline, alongside regulatory uncertainty surrounding the fees PEXA can charge.
The company is also continuing to invest heavily in its loss-making international expansion. Morningstar considered the market reaction excessive, arguing that structural transfer-volume assumptions had not materially changed, but the combination of softer near-term activity and regulatory risk overwhelmed the respectable headline numbers.
4. SEEK (ASX:SEK): –14.3%
SEEK produced solid FY26 figures, including 10% revenue growth to $1.20 billion, a 15% rise in EBITDA and 28% growth in adjusted earnings per share. It also lifted its fully franked annual dividend by 13% to a record 52 cents. Those achievements were overshadowed by falling paid job-ad volumes and cautious FY27 assumptions.
The statutory accounts included a $201 million loss from the SEEK Growth Fund and $377 million of significant items, making the headline result considerably less attractive. Investors were particularly concerned that economic weakness could limit volumes while the company continued investing in platform integration and artificial-intelligence products.
5. JB Hi-Fi (ASX:JBH): –12.3%
JB Hi-Fi’s full-year result was broadly respectable, with group sales rising 5% to $11.1 billion and underlying earnings per share increasing 6% to $4.48. The damage came from its current-trading update. Australian sales were almost flat during the June quarter and deteriorated further in July, while earnings in the core Australian electronics business fell 3.6%.
Housing-related categories were particularly weak as higher living costs and interest rates constrained household budgets. With JB Hi-Fi entering the season on a demanding valuation, an in-line historic result was not sufficient: the loss of sales momentum prompted investors to rapidly reduce their expectations for FY27.
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations. Bapcor was rewarded for being less troubled than feared, while several fundamentally profitable companies were punished because their outlooks failed to justify elevated valuations.

Travellers are swapping traditional sightseeing for immersive experiences, with Africa emerging as a must-visit destination.

The megamansion was built for Tony Pritzker, heir to the Hyatt Hotel fortune and brother of Illinois Gov. JB Pritzker.