More Than 40% of World’s Electricity Came From Zero-Carbon Sources in 2023
Investments in renewables continue to outpace fossil fuels, a BloombergNEF report finds

 2 min
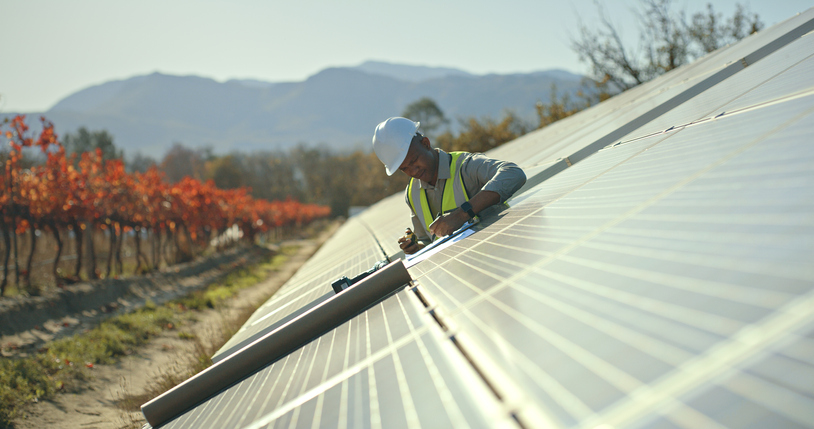
Zero-carbon technologies comprised more than 40% of global electricity generation for the first time in 2023, according to a report released Tuesday from BloombergNEF.
Renewable energy sources like wind and solar made up 17% of total electricity generation, and hydroelectric and nuclear power contributed 24%. Fossil fuels including coal and natural gas produced 57% of global electricity last year.
“We’ve consistently seen the penetration of renewables rising every year, and this year we hit quite a few milestones that had felt harder to reach in past years,” said Meredith Annex, head of clean power at BNEF.
One such milestone: Solar and wind represented more than 90% of global energy capacity additions last year, a step up from 2022. Global wind capacity also crossed the one-terawatt threshold. And Brazil, the country with the cleanest power mix of the G-20 economies, hit 88% renewable power generation in 2023.
“It just shows the momentum that the space is having. A lot of that does tie into the investment story, where you’ve got rising—skyrocketing, honestly—investment into solar,” Annex said.
Mainland China accounted for almost a third of total renewable energy output last year. The country recently reached its 2030 target for wind and solar energy six years early, according to a statement from its National Energy Administration, and it has pulled back on permits for new coal-fired power plants. The country’s rapid deployment of renewables has some analysts wondering if it will reach peak fossil fuel consumption this year. Declining emissions in China would signal a turning point because it is the world’s largest polluter, comprising nearly a third of global greenhouse gas emissions, according to the International Energy Agency.
Despite rapid growth in renewables, countries’ current commitments aren’t sufficient to limit global warming to 1.5 degrees Celsius, the goal outlined in the 2015 Paris Agreement, according to the IEA. Advanced economies would need to slash emissions by 80% by 2035 to meet the goal.
At last December’s COP28, a global climate conference hosted by the United Nations, participating countries agreed to triple renewable energy capacity by 2030. BNEF has forecast that achieving this goal would require investments in renewables to increase to 1.6 times 2023 levels from 2024 to 2030.
So far, that increase hasn’t materialised. Global investments in renewables are roughly on par with 2023 levels, at $313 billion in the first half of 2024, according to the new BNEF analysis. “We’re expecting steady growth, but steady growth does not get you to net zero,” Annex said.
The topline numbers obscure bigger changes under the surface. Average spending in the U.S. is up by about 63% compared with levels before the 2022 Inflation Reduction Act, which offers generous subsidies and tax breaks to promote decarbonisation. And while Chinese investment is actually down 4% from the same period in 2023, Annex said the dip is due to cheaper equipment for wind and solar, not a decline in demand.
The second half of this year will be a “defining moment,” for the investment landscape, Annex said. Steady growth “is definitely a positive, and it could be a sign that the industry as a whole is reaching a new kind of status quo, but we need to help expand even faster if we’re going to be in line with net zero.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.


Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
4 minA sharp technology sell-off has exposed a new anxiety on global markets: whether the enormous borrowing behind the artificial-intelligence infrastructure boom can generate sufficient returns as interest rates rise and Chinese competition intensifies.
The artificial-intelligence investment boom has powered technology shares, semiconductor manufacturers and data-centre operators to extraordinary heights. Last week, investors were given a reminder that much of this expansion is being built with borrowed money.
The technology-heavy Nasdaq Composite fell 4.5 per cent over the week ended October 16, its weakest performance since late June. Semiconductor shares suffered an even deeper correction, with the Philadelphia Semiconductor Index losing about 11.4 per cent.
The selling spread quickly through global markets. Micron Technology fell 14.6 per cent over the week, while South Korea’s Samsung Electronics and SK Hynix dropped approximately 18 per cent and 24 per cent respectively.
This was more than a routine bout of profit-taking. Investors were reassessing three interconnected risks: higher interest rates, the rapidly expanding debt burden attached to AI infrastructure and the prospect of stronger competition from Chinese memory-chip manufacturers.
The debt behind the AI build-out
Artificial intelligence requires a physical infrastructure network of enormous scale. Data centres must be built, advanced processors purchased, power supplies secured and cooling systems installed before customers begin generating meaningful revenue from them.
Technology companies are increasingly supplementing their own cash with corporate bonds, syndicated loans, equipment leases, private credit and project-level financing.
JPMorgan describes the emerging funding model as a combination of conventional corporate borrowing and project finance tied to individual data-centre assets. In Australia, the Reserve Bank estimates that syndicated loans accounted for approximately three-quarters of data-centre financing during 2025 and 2026 to date.
The numbers are becoming large enough to affect broader credit markets. The Federal Reserve Bank of Dallas has cited Wall Street estimates suggesting AI-related investment-grade bond issuance could approach US$300 billion in 2026 alone.
That borrowing is not automatically problematic. Debt can be an efficient way to finance long-lived infrastructure when future revenue is sufficiently predictable. The concern is that AI technology, customer demand and computing economics are changing much faster than the repayment schedules attached to the assets.
A data centre financed today may carry debt for years. Investors must therefore make assumptions about future utilisation rates, electricity prices, chip performance, customer concentration and the amount businesses will ultimately pay for AI computing.
When interest rates rise, those assumptions become less forgiving.
Inflation changes the calculation
September’s US inflation data intensified the pressure. Consumer prices increased 3.7 per cent over the year, ahead of market expectations and up from 3.4 per cent in August.
The hotter reading reduced confidence that interest rates would fall quickly and pushed bond yields higher. That matters particularly for companies whose valuations depend on profits expected well into the future, as well as highly leveraged infrastructure operators that may need to refinance.
CoreWeave has emerged as a closely watched test case. The specialist cloud-computing company has accumulated substantial debt and lease obligations to build AI capacity, while relying on a concentrated group of large technology customers.
Its shares fell sharply during the sell-off, while the cost of insuring its debt against default climbed. CoreWeave has argued that its contracted backlog more than covers its obligations and that financial markets do not always understand its business model. Nevertheless, its securities have become a proxy for investor confidence in debt-funded AI infrastructure.
Oracle, another major investor in AI computing capacity, fell 8.8 per cent in Friday trading, while CoreWeave dropped 15.5 per cent.
The question is shifting from how much AI infrastructure can be built to how profitably it can be operated.
China adds another source of pressure
Interest rates were not the only catalyst. Reports of advances by Chinese memory-chip producer ChangXin Memory Technologies raised concerns that lower-cost Chinese products could increase competition across the global semiconductor industry.
Memory chips are essential to AI systems, but the industry is historically cyclical. Periods of tight supply and high pricing can encourage rapid investment, eventually producing oversupply and falling margins.
The prospect of a well-funded Chinese competitor expanding its technological capabilities unsettled investors in Samsung, SK Hynix and Micron. It also demonstrated that AI-related demand does not insulate chipmakers from conventional competitive pressures.
That combination—slower rate cuts, more expensive financing and potentially cheaper supply—challenged the assumption that every company exposed to AI would enjoy continually expanding margins.
A reset rather than the end of the boom
The sell-off does not establish that the AI boom is ending. Demand for computing power remains strong, the largest technology companies continue to generate formidable cash flows and many infrastructure projects are backed by long-term customer contracts.
What has changed is the market’s willingness to overlook the price and financing structure of that growth.
The most resilient companies are likely to be those able to fund investment from operating cash flow, secure long-duration customers and demonstrate that new capacity will earn returns comfortably above its financing costs.
More speculative operators may face greater scrutiny, particularly where debt is expensive, customers are concentrated or expected revenue depends on demand that has not yet materialised.
For Australian investors, the lesson extends beyond US technology shares. Local data-centre operators, infrastructure funds, electricity suppliers and property groups are increasingly exposed to the same investment cycle.
Artificial intelligence may remain one of the defining growth themes of the decade. But last week’s correction showed that enthusiasm for the technology does not eliminate financial discipline.
The next stage of the AI boom will be judged not only by computing power, model performance or demand for chips, but by something more traditional: whether the assets being financed can generate enough cash to repay the money borrowed to build them.
Fact box
Nasdaq Composite: Down 4.5 per cent for the week ended October 16, 2026
Philadelphia Semiconductor Index: Down approximately 11.4 per cent
Micron Technology: Down approximately 14.6 per cent
Samsung Electronics: Down approximately 18 per cent
SK Hynix: Down approximately 24 per cent
US September inflation: 3.7 per cent annually
Estimated 2026 AI-related investment-grade issuance: Approximately US$300 billion
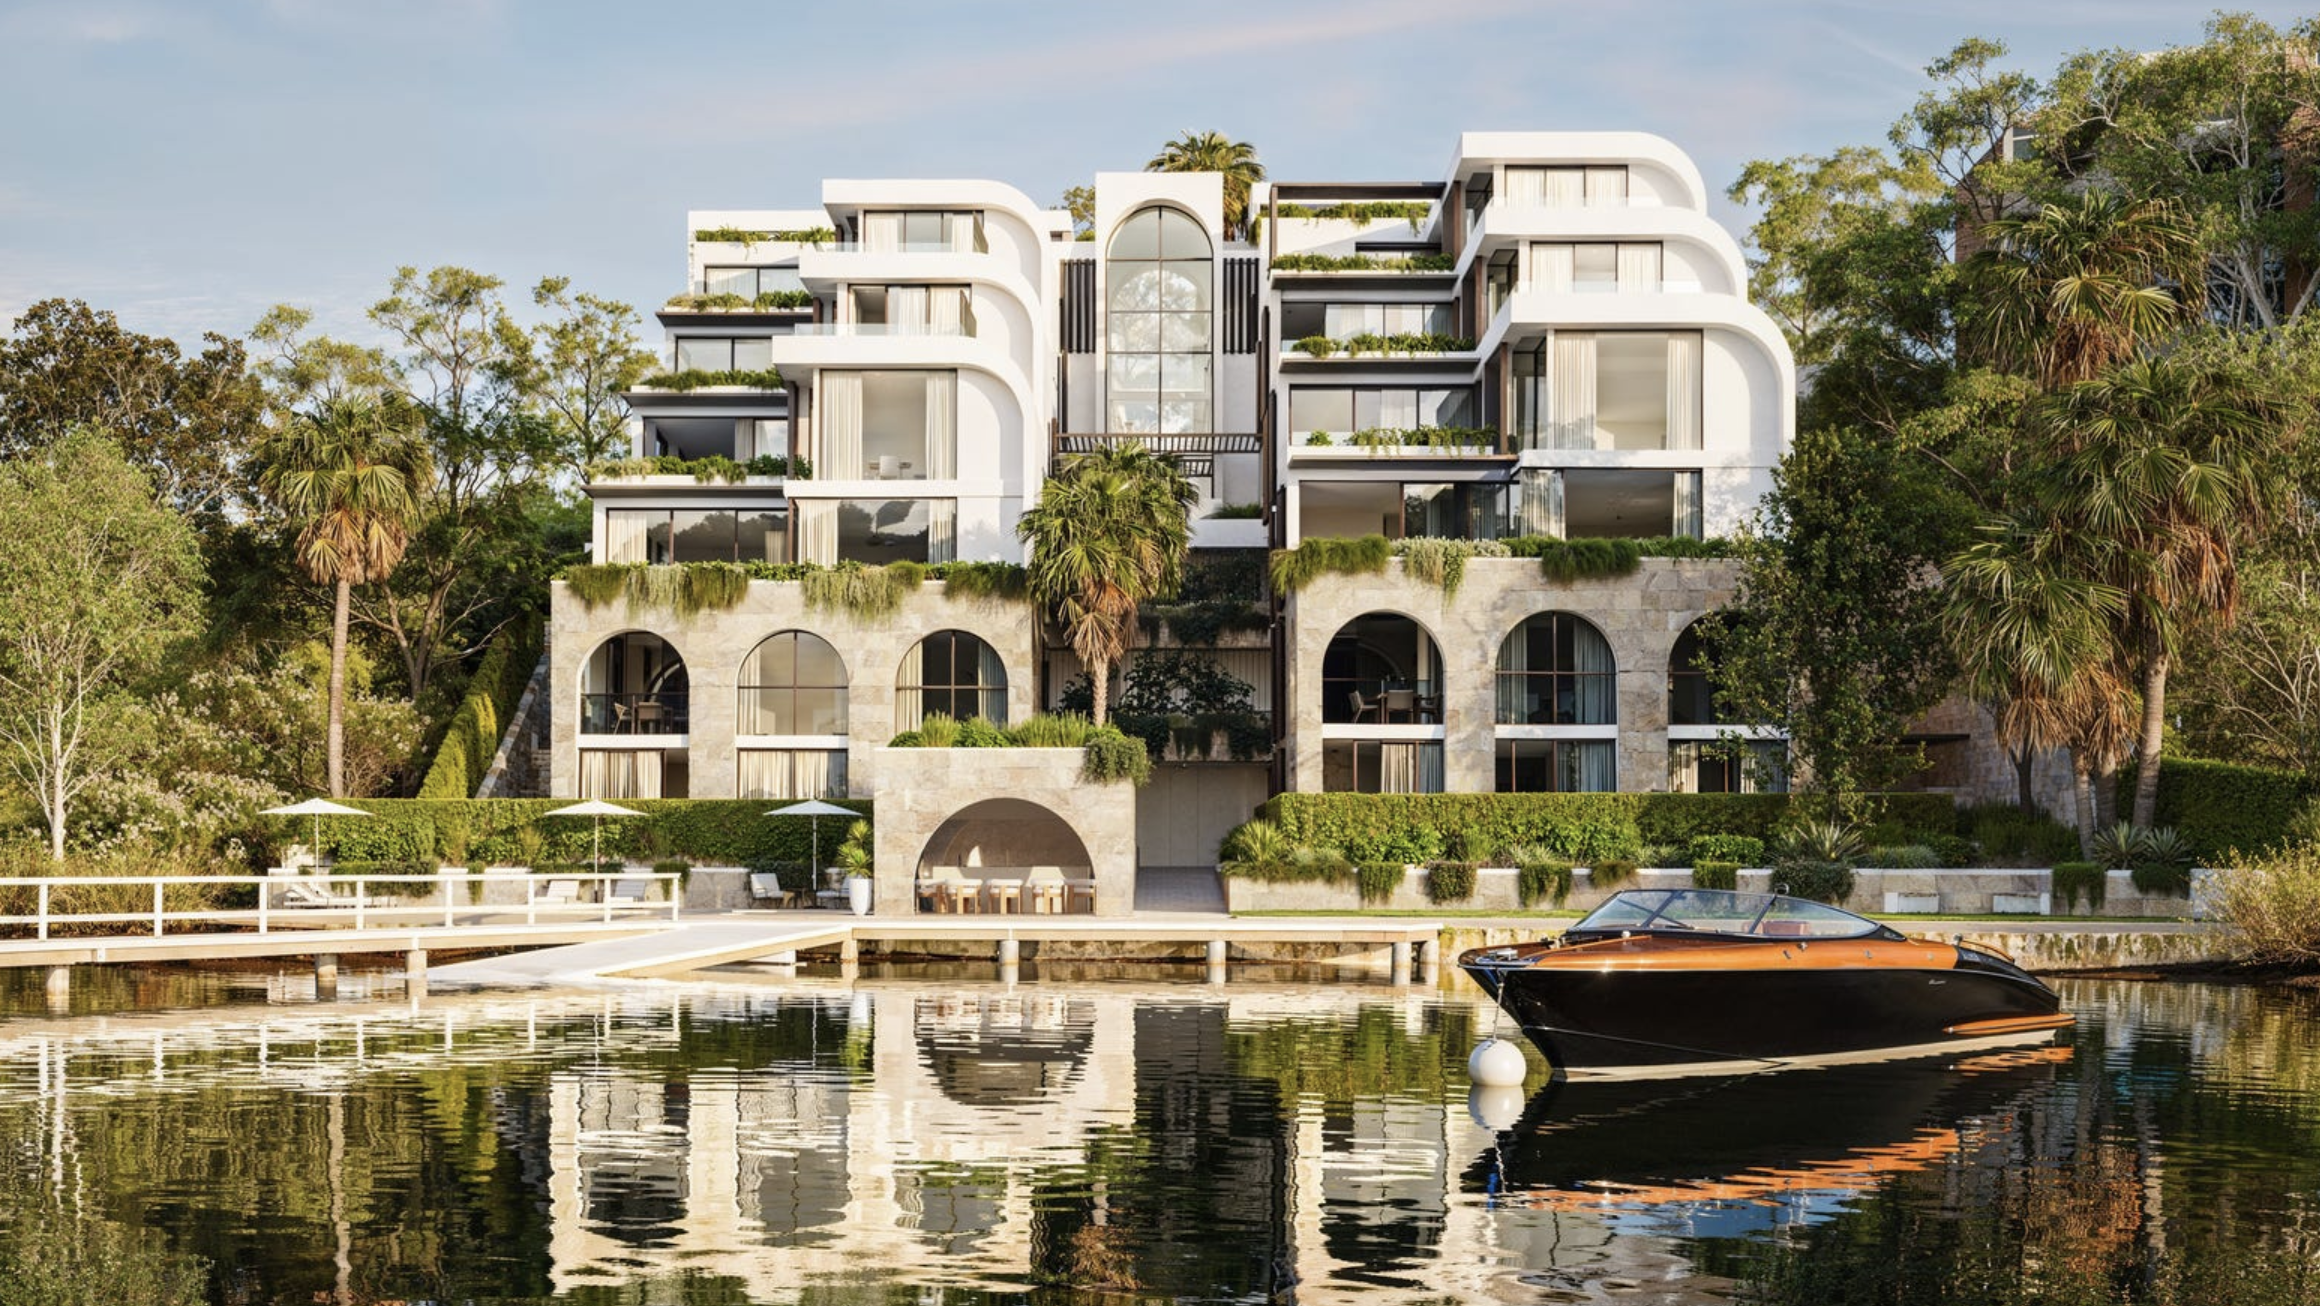
Advertising legend John Singleton unveils an exclusive 16-residence Caroline Bay development, marking his latest high-end property play on the Central Coast.

New research suggests that bonuses make employees feel more like a mere cog in a wheel.