The Biggest Mistakes People Make With Their Wills
The obvious one isn’t doing a will at all. But that is just one of many errors people make—often with potentially serious consequences.

 5 min
Everybody knows they should have a will, and not having one can leave heirs with a big mess. But just having a will isn’t enough. Big mistakes are common—from leaving decisions to the last minute and failing to update documents to mismatching beneficiary designations.
What follows are some of the biggest mistakes people make when doing their wills, according to attorneys who have seen these missteps far too often.
Procrastinating
Of course, thinking about death is uncomfortable, and planning for it can be costly. But to have a say in the distribution of your assets after you die—what each heir will receive, what charities to support and other matters—timely planning is critical. Yet many people either don’t create the proper documents, or they attempt to cobble something together on their deathbed. These last-minute efforts can lead to a host of problems for the simple reason that decisions made in haste leave less time to think through the multiple what-ifs.
Last-minute preparation also raises the likelihood that a disgruntled heir could claim the will was made under duress or in a diminished capacity, says Rebecca Hedaya-Heller, founding partner of Heller & Associates, a law firm in North Woodmere, N.Y.
Another reason not to procrastinate: A document known as a revocable trust, or living trust, can make it possible to distribute assets while you are still living and can be useful if you become incapacitated. A living trust can be especially important in states such as New York, California and Florida that have more restrictive probate laws. Living trusts have other uses as well, such as keeping things out of the public record since trusts are private documents, Ms. Hedaya-Heller says. This means that a family’s affairs can be kept private, including the value of the estate and to whom assets have been given.
Dropping large inheritances in heirs’ laps
When leaving significant money to heirs, people sometimes choose to bequeath it outright, all at once. This can be a mistake, says David Handler, a partner in the trusts and estates practice group at Kirkland & Ellis LLP. Children in their early 20s or 30s, or even later in life, may not be able to handle such windfalls. Giving them unfettered access to it, he says, can be imprudent.
A better option, Mr. Handler says, is to leave the assets to a trust to manage the assets after death. Such trusts also can offer tax and asset-protection advantages to the beneficiaries, he says. For example, they can be designed so that a divorcing spouse or creditor from a lawsuit cannot reach the trust assets. A trust also can be structured to avoid additional estate tax when the assets pass to siblings or children upon the beneficiary’s death, regardless of the trust’s value or the beneficiary’s net worth.
Forgetting digital assets
As more people invest in cryptocurrency and NFTs, it becomes critical to ensure someone will have the ability to navigate their digital wallets once they pass away, says Jonathan Forster, partner at Weinstock Manion in Los Angeles. “If you have a digital wallet and no one has that information, the crypto is lost,” he says.
Be sure to keep good records of your cryptocurrency and leave heirs instructions about how to access this information. Don’t store private keys—strings of letters and numbers that allow access to digital assets—on an old, offline computer, for instance, because the hardware could be inadvertently thrown out and the assets lost. Instead, consider using a special device known as a hardware wallet to manage your crypto assets, and make sure heirs know how to find and access the device.
Additionally, people should not include their passwords or private keys in a will itself, which becomes public through the probate process.
Not making regular updates
Write it and forget it is a common theme for wills. But the documents should be updated every five to 10 years because intentions and circumstances can change over time. “Life happens,” says J. Whitfield Wilks, director at Novare Capital Management, an investment management firm in Charlotte, N.C.
People who have made out their wills years earlier can change their minds about who should get what and which charities to support. Appropriate guardians for children, too, can change over time, which is why periodic reviews are critical. For instance, says Mr. Wilks, 20 years after a will is drawn up, a sibling who was named as executor could be dead or estranged, in a nursing home or otherwise incapacitated.
Mismatching beneficiaries
Even if they have an updated will or living trust, many people forget to update their beneficiary designations on other things—such as pension accounts, individual retirement accounts and other investments, and life-insurance policies. Because a beneficiary designation generally supersedes the terms of a will, there can be unintended consequences. These can include leaving substantial sums of money to an ex-spouse or failing to leave specific assets to a child or grandchild since an original designation may have been made before they were born. “It’s an ongoing process to make sure these things match and your wishes will be implemented,” Mr. Wilks says.
Not allowing for flexibility
Sometimes wills or living trusts are worded in ways that cause unintended consequences, such as leaving more or less money than desired to an individual or charity.
For example, Mr. Handler says, imagine a man with an estate worth $10 million whose will says to leave $1 million to charity and the rest to his children. Under that scenario, the children would get $9 million. But if the estate’s value drops and is now worth only $4 million, the charity would still receive $1 million and the children only $3 million.
People also have to be careful when leaving a particular stock or bank account to a particular child, he says. When the person dies, if the asset is no longer owned or has dropped precipitously in value, that child could unintentionally be left with nothing or significantly less than their siblings, he says.
Not heading off conflicts
Conflicts between heirs tend to happen more often when they are surprised by the contents of wills or trusts, says Mr. Forster, which is why the Los Angeles attorney says he recommends clients be upfront with beneficiaries about their intentions. While these conversations can be hard, having them in advance mitigates the risk of resentment, and possibly litigation, among heirs after a loved one dies.
Mr. Forster offers the example of a mother who was planning to leave a significantly larger share of her estate to her daughter, a teacher. This move would have left her son, a doctor, mostly disinherited. Although the mother loved both her children and was on good terms with both, her estate-planning decisions were based on their respective financials.
Acting on Mr. Forster’s advice, she spoke to the son before drafting the estate plan and was surprised to hear he felt snubbed and unloved, which wasn’t her intent. As a result, she amended her plans, still leaving the daughter more money than the son, but to a lesser extent.
Because the family discussed the situation, the son won’t “have to spend the rest of his life wondering if he did something wrong or whether his mom didn’t love him as much,” Mr. Forster says. “At least they got to have that conversation.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


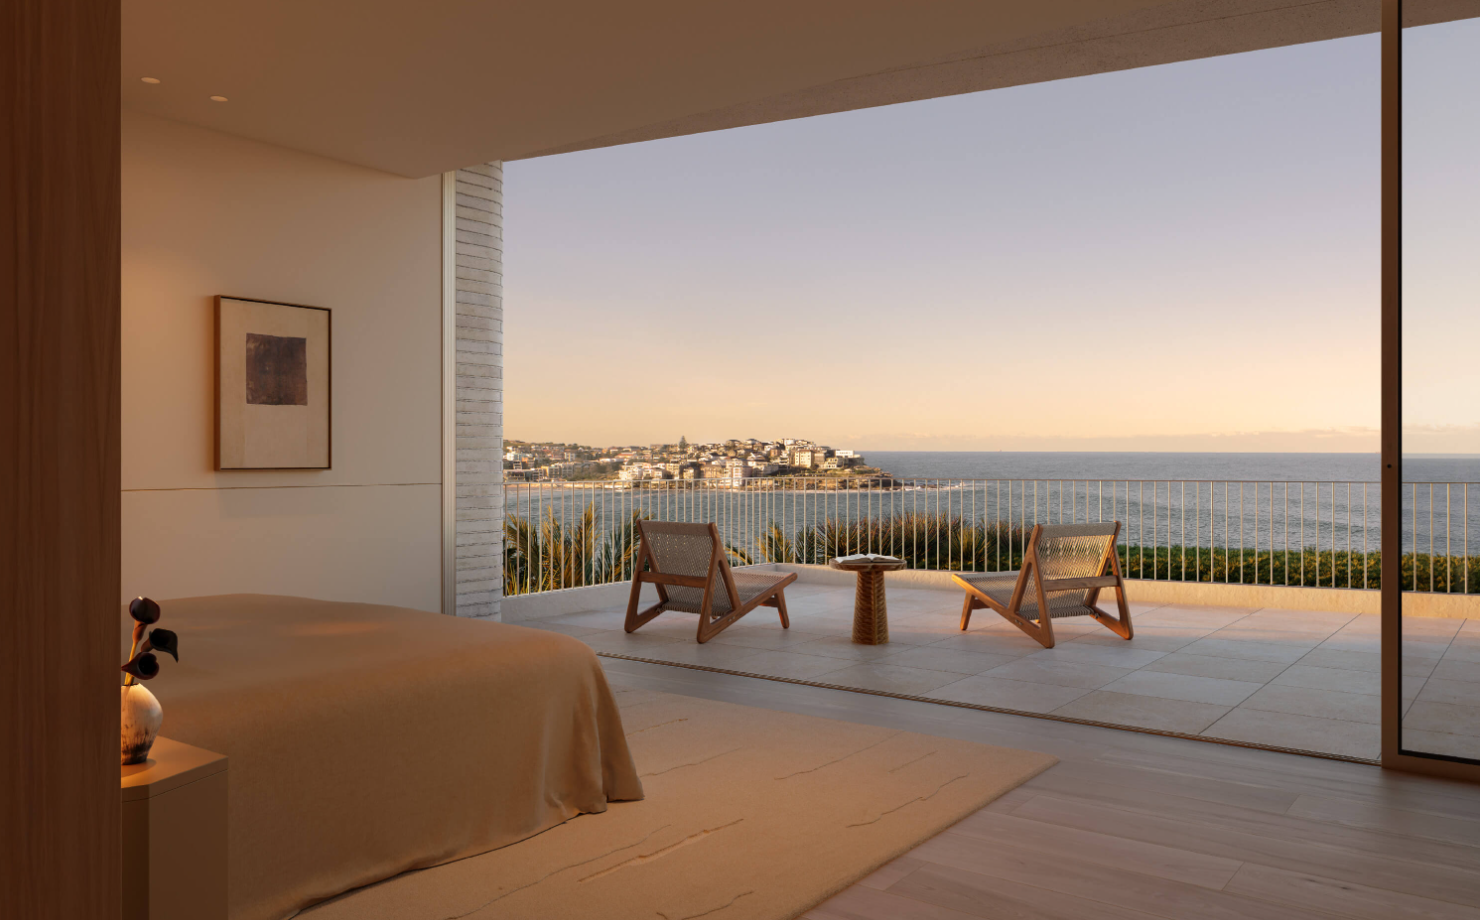
For Central Element, the start of work at Pearl represents another step in the company’s growing eastern suburbs pipeline.
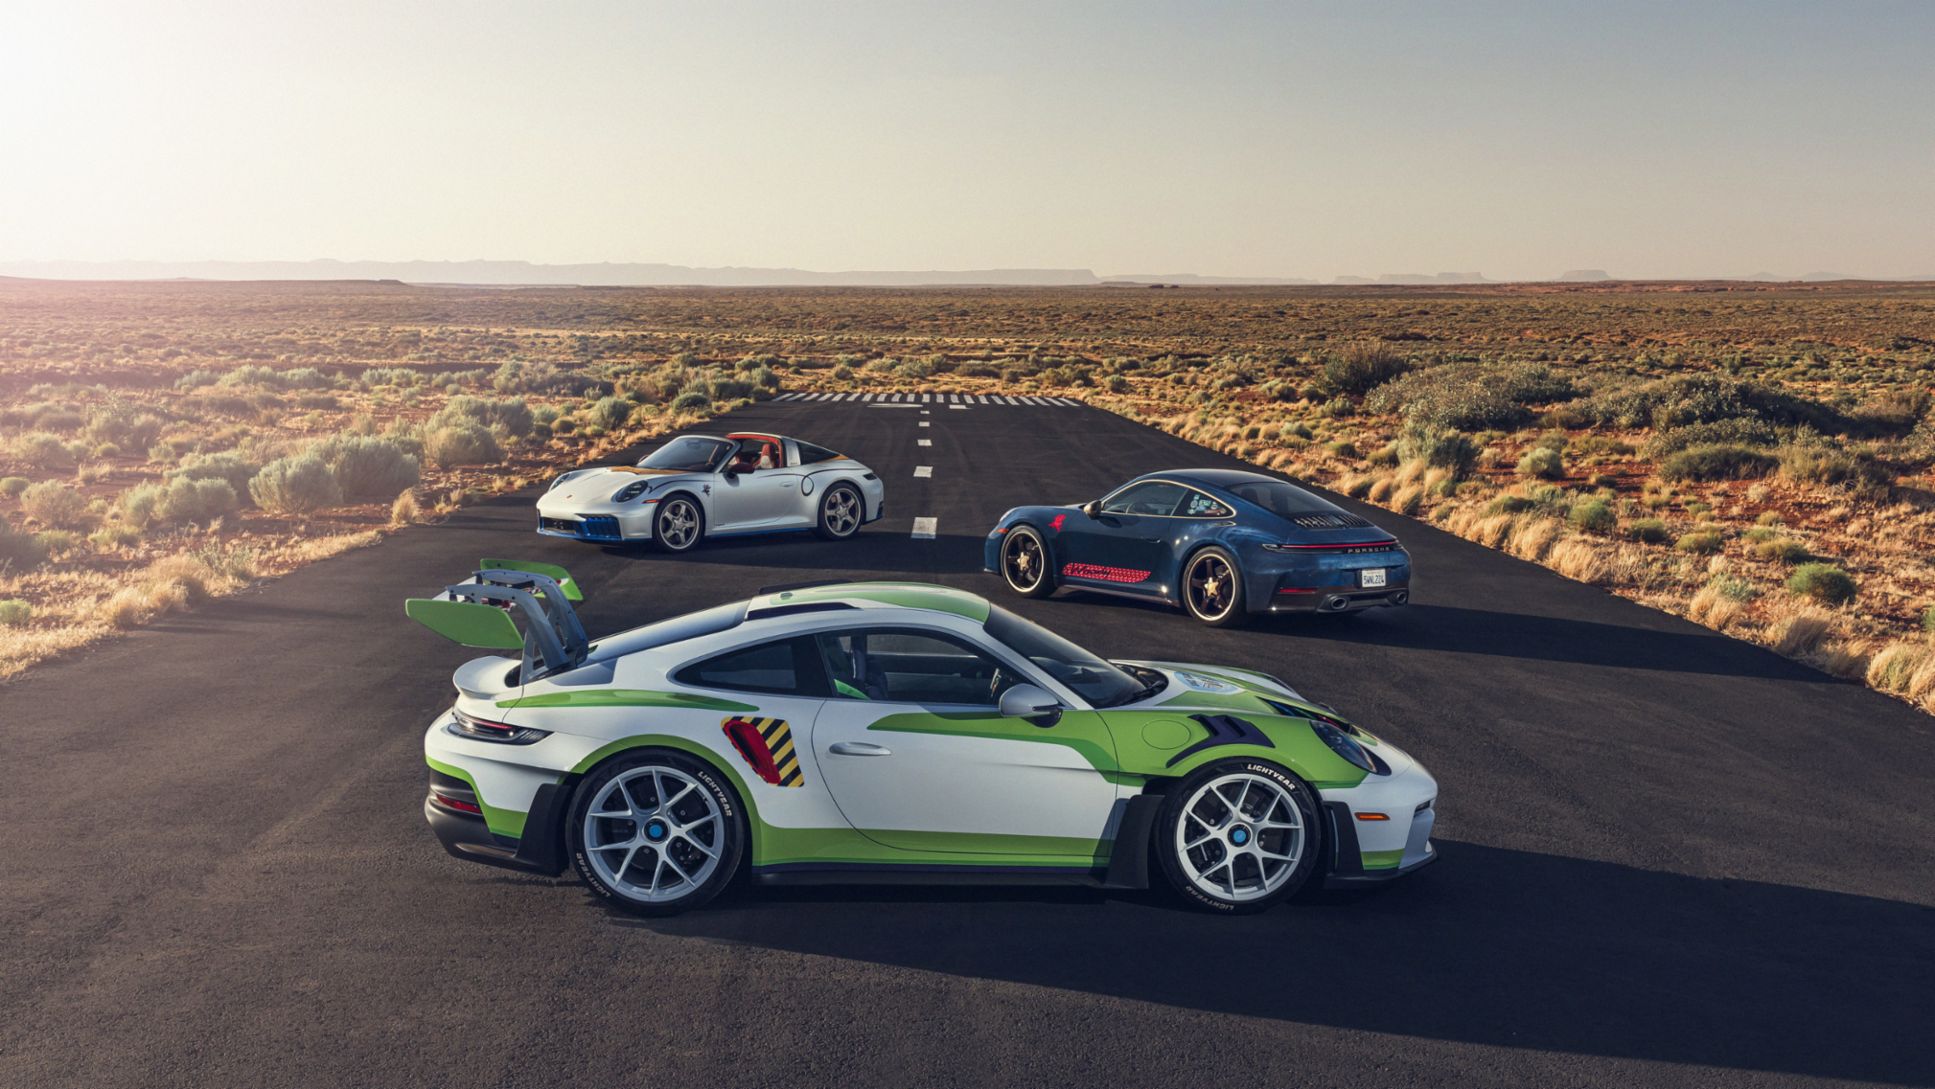
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations
5 min
Reporting season has once again reminded investors that a strong profit does not guarantee a rising share price, and a large loss does not always trigger a sell-off. What matters most is how each result compares with expectations and, increasingly, what management says about the year ahead. During the August 2026 season, companies offering credible turnarounds or unexpectedly strong guidance were rewarded handsomely, while those flagging weaker margins, slowing demand or greater uncertainty were punished.
The following ranking draws on Morningstar’s review of 164 ASX-listed companies and measures each company’s share-price movement on the day it reported. This captures the market’s immediate response to the earnings announcement, before subsequent economic developments, dividends and company-specific news cloud the picture. Here are the five biggest winners, and the five hardest-hit losers, of the season so far.
The five winners
1. Bapcor (ASX:BAP): +41.0%
Bapcor delivered reporting season’s largest relief rally after presenting early evidence that its troubled automotive-parts business was stabilising. Although underlying revenue fell 1.8% to $1.92 billion and underlying NPAT collapsed 85% to $10.8 million, underlying EBITDA of $152.5 million exceeded guidance.
More importantly, working-capital initiatives released $68.5 million in the second half, lifting cash conversion to 109.4% and reducing net debt by 63% to $135 million. The statutory loss was $431.6 million, largely because of non-cash impairments. Investors focused on improving operational momentum, stronger liquidity and management’s expectation of modest FY27 revenue growth.
2. Zip Co (ASX:ZIP): +18.2%
Zip comfortably surpassed its FY26 targets, sending the buy-now-pay-later provider’s shares sharply higher. Transaction volume rose 23% to $16.7 billion, while cash earnings before tax, depreciation and amortisation jumped 58% to a record $268.9 million. Statutory profit climbed 46% to $116.4 million, and the cash operating margin expanded by 4.2 percentage points to 20%.
The strongest signal was guidance for FY27 cash earnings of $340 million—around 26% growth and above analysts’ forecasts. US transaction volume increased 42.5% and now represents three-quarters of group volume, offsetting weaker customer activity in Australia.
3. CSL (ASX:CSL): +17.3%
CSL’s result was hardly spectacular in isolation, but it cleared a market bar that had fallen dramatically following earlier downgrades and restructuring announcements. Underlying NPATA was US$3.1 billion, down 2% in constant-currency terms, while operating cash flow reached US$3.51 billion.
CSL maintained its full-year dividend at US$2.92 per share and completed a A$1 billion buyback. The real catalyst was FY27 guidance for approximately 5% underlying profit growth, compared with market expectations closer to 2%. After an extended period of earnings disappointments, investors interpreted the outlook as evidence that CSL’s core plasma business was approaching a sustainable recovery.
4. Judo Capital (ASX:JDO): +16.9%
Judo Capital demonstrated strong operating leverage as its specialist business-lending franchise expanded. Full-year profit before tax rose 34% to $168.1 million, while pre-provision profit increased 42%. Gross loans and advances grew 18% to $14.7 billion, reaching the top of the bank’s guidance range and comfortably exceeding broader system growth.
Deposits increased 24% to $12.2 billion, return on equity improved by 1.1 percentage points to 6.4%, and earnings per share rose 29% to 9.9 cents. Reaffirmation of the FY27 outlook gave investors confidence that loan growth could continue without sacrificing margins or credit quality.
5. Super Retail Group (ASX:SUL): +15.8%
The owner of Supercheap Auto, rebel, BCF and Macpac reported record sales of $4.2 billion, up 3.2%, despite cautious discretionary spending. Profitability went backwards: normalised profit before tax fell 7% to $306 million and normalised NPAT declined 2.8% to $226 million as transformation spending weighed on margins. Nevertheless, the result exceeded subdued expectations, online sales grew 5.3% and membership across the group’s loyalty programs reached 13.1 million. Investors were also encouraged by positive early FY27 trading, stable gross margins and continued market-share gains. A fully franked 33-cent final dividend added to the appeal.
The five losers
1. Hansen Technologies (ASX:HSN): –21.2%
Hansen’s historic result met expectations, but investors recoiled from its outlook. The utility and communications software provider achieved an underlying EBITDA margin of 31%, exceeding its 30% target, while generating strong cash flow. However, management designated FY27 an “investment and transition year”, signalling a roughly five-percentage-point margin contraction as spending on products, sales capabilities and organisational changes increased.
Revenue had already been broadly flat, leaving investors concerned that the investment program would depress earnings before new growth appeared. Leadership changes, including the chief executive’s departure, added uncertainty. Management expects revenue growth and margins above 30% to return in FY28, but the market was unwilling to wait.
2. Life360 (ASX:360): –19.4%
Life360’s headline growth was impressive: quarterly revenue rose 38% to US$159 million, subscription revenue increased 31%, and adjusted EBITDA climbed 53% to US$31.1 million. Monthly active users reached 102.4 million and paying circles grew 27% to 3.2 million. The sell-off reflected expectations rather than a collapsing business.
Net income fell 18%, the net margin contracted from 6% to 3%, hardware shipments dropped 18%, and full-year EBITDA guidance was merely maintained. After a strong valuation run, investors wanted a larger upgrade and clearer evidence that heavy investment in advertising, international expansion and artificial intelligence would generate additional earnings.
3. PEXA Group (ASX:PXA): –17.0%
PEXA reported a 7% increase in continuing-operations revenue and 12% EBITDA growth to $152 million, accompanied by a two-percentage-point margin expansion. Free cash flow increased 39%, suggesting the core Australian electronic-conveyancing platform remained highly profitable. Investors instead concentrated on management’s warning that property-transfer volumes could decline, alongside regulatory uncertainty surrounding the fees PEXA can charge.
The company is also continuing to invest heavily in its loss-making international expansion. Morningstar considered the market reaction excessive, arguing that structural transfer-volume assumptions had not materially changed, but the combination of softer near-term activity and regulatory risk overwhelmed the respectable headline numbers.
4. SEEK (ASX:SEK): –14.3%
SEEK produced solid FY26 figures, including 10% revenue growth to $1.20 billion, a 15% rise in EBITDA and 28% growth in adjusted earnings per share. It also lifted its fully franked annual dividend by 13% to a record 52 cents. Those achievements were overshadowed by falling paid job-ad volumes and cautious FY27 assumptions.
The statutory accounts included a $201 million loss from the SEEK Growth Fund and $377 million of significant items, making the headline result considerably less attractive. Investors were particularly concerned that economic weakness could limit volumes while the company continued investing in platform integration and artificial-intelligence products.
5. JB Hi-Fi (ASX:JBH): –12.3%
JB Hi-Fi’s full-year result was broadly respectable, with group sales rising 5% to $11.1 billion and underlying earnings per share increasing 6% to $4.48. The damage came from its current-trading update. Australian sales were almost flat during the June quarter and deteriorated further in July, while earnings in the core Australian electronics business fell 3.6%.
Housing-related categories were particularly weak as higher living costs and interest rates constrained household budgets. With JB Hi-Fi entering the season on a demanding valuation, an in-line historic result was not sufficient: the loss of sales momentum prompted investors to rapidly reduce their expectations for FY27.
Overall, the season showed that share prices react less to whether profits rose or fell than to the gap between results and expectations. Bapcor was rewarded for being less troubled than feared, while several fundamentally profitable companies were punished because their outlooks failed to justify elevated valuations.
Odd Culture Group brings a new kind of after-dark energy to the CBD, where daiquiris, disco and design collide beneath the city streets.
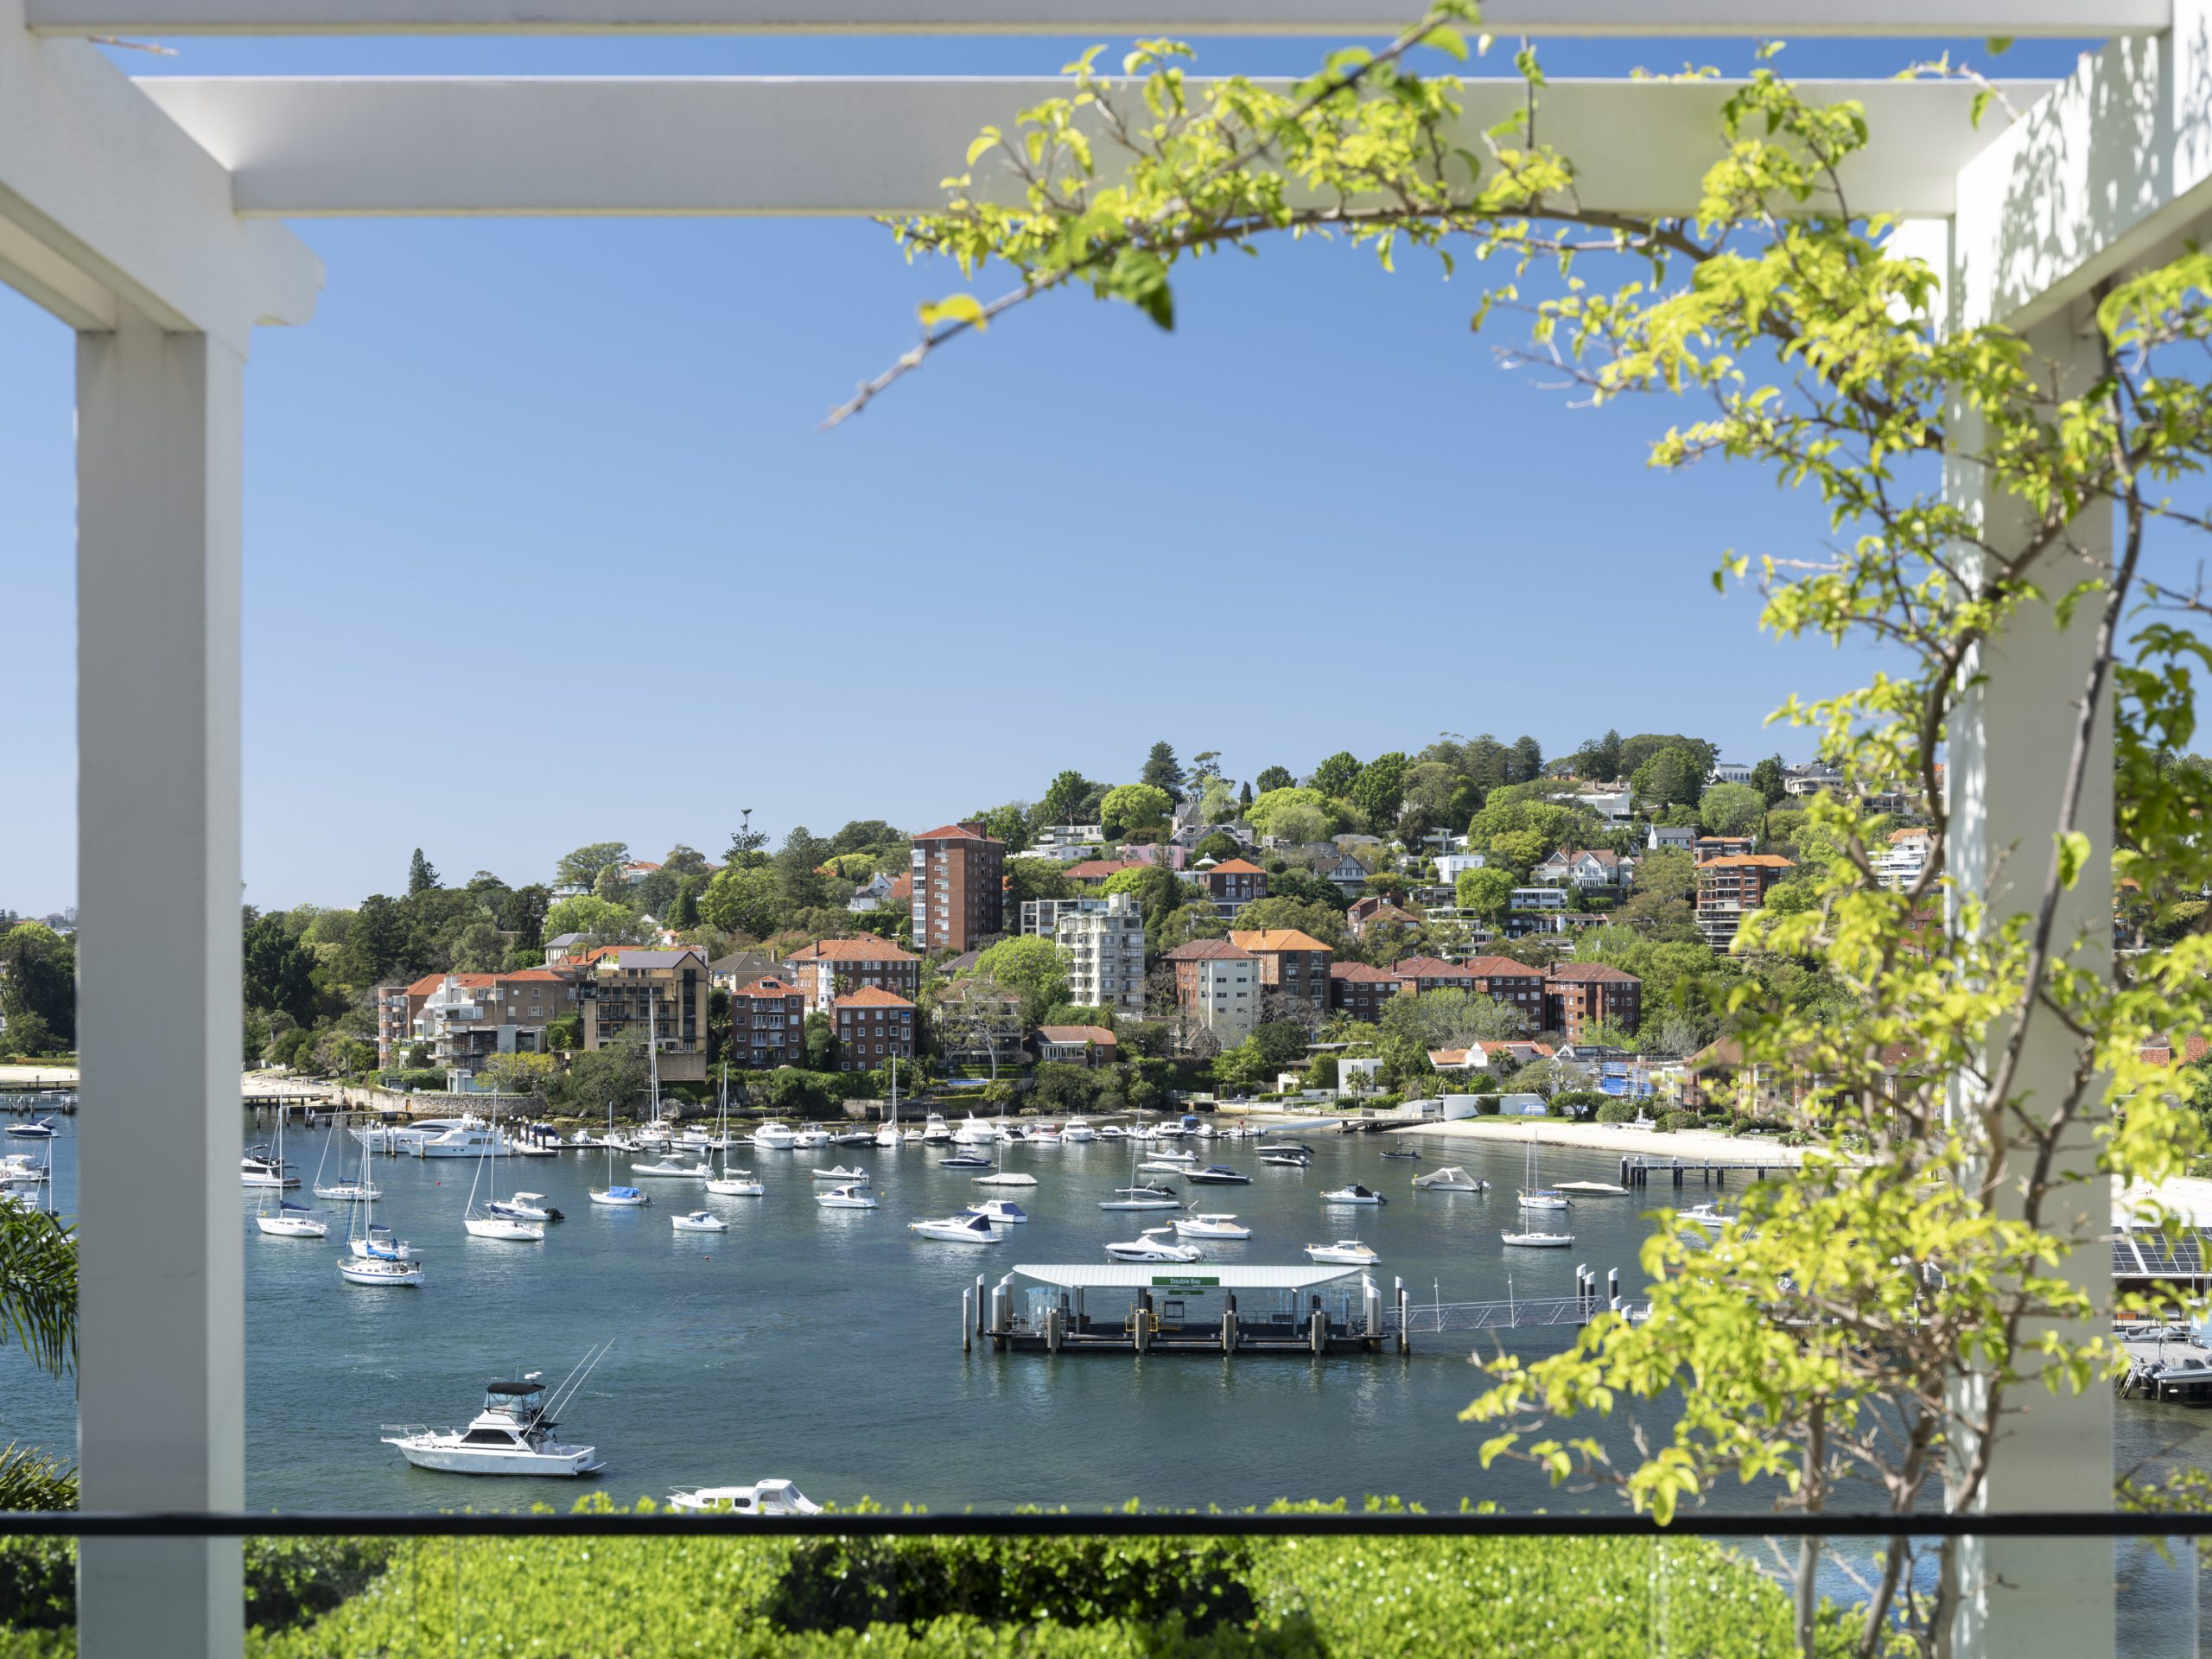
The grand harbourside residence combines sweeping Sydney Heads views, resort-style entertaining and refined designer finishes with a reported $36 million price guide.