‘Envy of the World’—U.S. Economy Expected to Keep Powering Higher
Economists lift their growth forecasts in latest Wall Street Journal survey

 4 min
It has been two years since forecasters felt this good about the economic outlook.
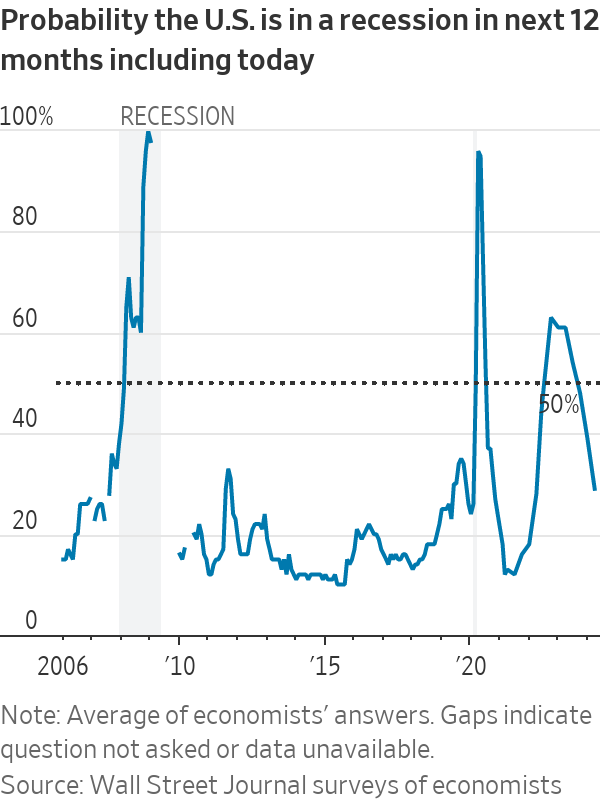
In the latest quarterly survey by The Wall Street Journal, business and academic economists lowered the chances of a recession within the next year to 29% from 39% in the January survey . That was the lowest probability since April 2022, when the chances of a recession were set at 28%.
Economists, in fact, don’t think the economy will get even close to a recession. In January, they on average forecast sub-1% growth in each of the first three quarters of this year. Now, they expect growth to bottom out this year at an inflation-adjusted 1.4% in the third quarter.
Just 10% of survey respondents think the economy will experience at least one quarter of negative growth over the next 12 months, down from 33% in January.
The Wall Street Journal survey was conducted from April 5 to 9, just before the release of March consumer-price index data showing inflation running hotter than economists had anticipated.
The U.S. economy has far outperformed expectations over the past year and a half. Instead of stumbling under the weight of the Federal Reserve’s most aggressive interest-rate-raising campaign in four decades, it has continued expanding at a robust clip.
Few think that the economy can do quite as well as last year’s 3.1% growth, as measured by the seasonally adjusted fourth-quarter change from a year earlier. That figure might have been boosted by one-time factors such as federal infrastructure and semiconductor legislation and an uptick in immigration , which also might not last.
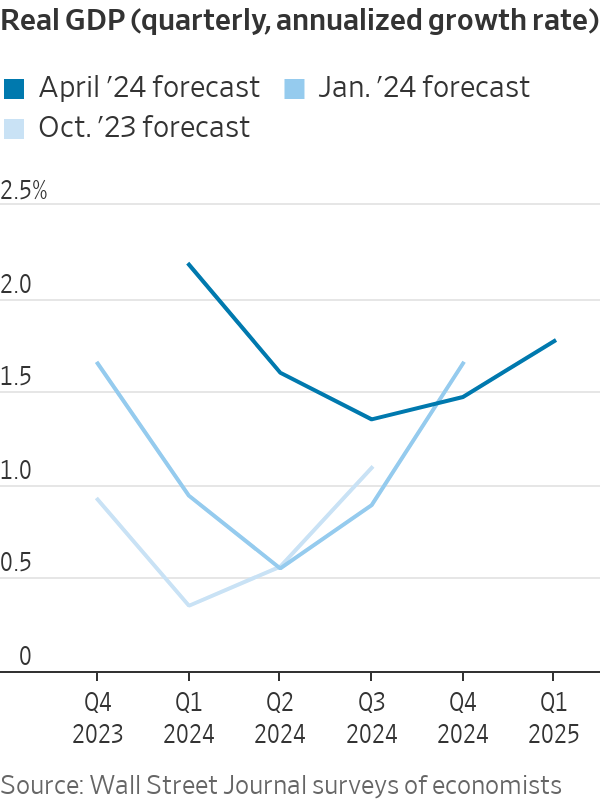
Still, economists have had to rethink forecasts for a major slowdown as more time has passed and one still doesn’t seem imminent. Economists on average think the economy grew at a 2.2% rate in the first three months of the year, up from a 0.9% forecast in January.
“The U.S. economy is performing very well,” EconForecaster economist James Smith said in the survey. “We’re truly the envy of the world.”
Much has changed since economists were last this optimistic. Two years ago, the Fed’s benchmark federal-funds rate was set between 0.25% and 0.5%. Inflation was high but economists still generally thought that it could come down without too much help from the Fed. They forecast steady growth and the midpoint of the range for the fed-funds rate topping out at just above 2.5%.
Now, the fed-funds rate is sitting between 5.25% and 5.5%, and economists don’t see a bunch of cuts coming soon. Many analysts trimmed their rate-cut forecasts after last week’s hot inflation report. But even before the report, survey respondents predicted that rates would end the year at 4.67%, implying three cuts. In January, their responses suggested that they thought four or five cuts were likely.
Economists now think the economy can withstand higher rates than they did not long ago.
They expect the 10-year Treasury yield—a key borrowing benchmark that was around 4.4% at the time of the survey—to end 2024 at 3.97%. Looking further into the future, they expect the yield to end 2026 at 3.78%. That is slightly above even their forecast last October, when the yield was higher than it is now.
Many economists have long thought that the economy can handle higher interest rates when it is capable of growing faster, and particularly when worker productivity has increased.
To that end, economists expect the Labor Department’s measure of productivity to rise at an annual rate of 1.9% over the next decade. That matches the annual increase in productivity over the last 40 years. But it is above the 1.2% pace of the 2010s, when the 10-year Treasury yield was typically stuck between 1.5% and 2.5%.
Some economists are now enthusiastic about the economy’s longer-term potential.
“We think that the American economy has entered a virtuous cycle where strong productivity results in growth above the long-term trend, inflation between 2% and 2.5% and an unemployment rate between 3.5% and 4%,” RSM US chief economist Joe Brusuelas said in the survey.
Many aren’t quite as optimistic. One downside of a better growth outlook is that a stronger economy could make it harder for inflation to fall all the way back to the Fed’s 2% target.
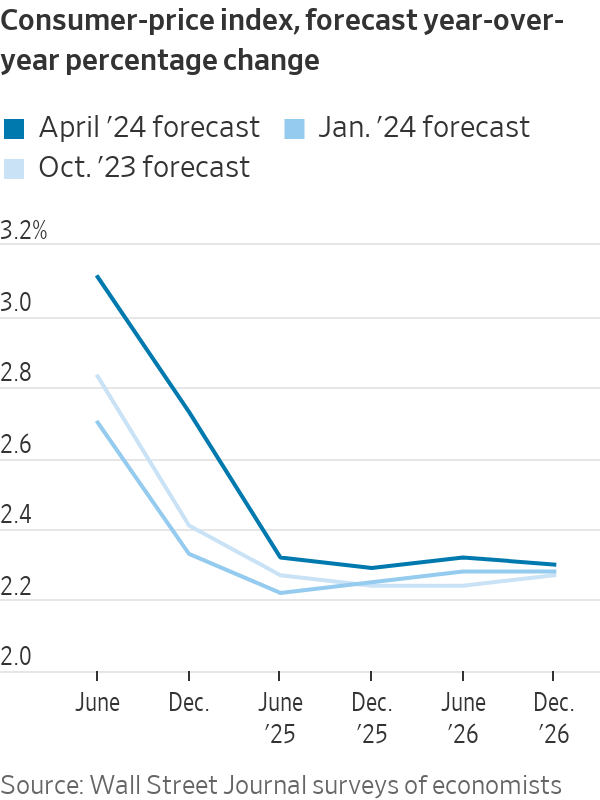
An inflation gauge that is closely watched by the Fed, the core personal-consumption expenditures price index, was 2.8% in February, its most recent reading. Economists now expect it to end the year at 2.5%, after having forecast 2.3% in January.
Economists, on average, believe that core PCE inflation will fall to 2.1% by the end of next year without a recession. However, their projections might already have ticked higher after last week’s price data, and some continue to worry that the Fed’s efforts to control inflation still present a major threat to the economy.
“The risks are clearly skewed toward more hawkish Fed outcomes, which could drag on our growth forecasts,” Deutsche Bank economists Brett Ryan and Matthew Luzzetti said in the survey.
The Wall Street Journal survey was answered by 69 economists. Not every economist responded to every question.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

 2 min
Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market.
The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index.
Energy was the notable exception, gaining more than one per cent as Brent crude traded above US$103 a barrel. Oil had moved higher amid uncertainty surrounding potential US diesel-export restrictions and broader geopolitical supply risks. The move supported energy producers but renewed concern about inflation inputs across transport and the wider economy.
Gold shares were weak even as spot bullion remained historically elevated. The All Ordinaries Gold index fell about 2.25 per cent, showing that equity performance can diverge from the commodity because of valuation, currency, operating and company-specific factors.
Zip was a prominent loser, falling 11.38 per cent after the company reported short sales after the previous close. Nine Entertainment also weakened after UBS analysts warned of near-term revenue challenges associated with its advertising-supported subscription tier.
Premier Investments led larger winners despite caution about the retail environment. Breville, in which Premier owns a significant stake, also appeared among leading movers. In the broader ASX 300 screen, Myer gained 11.43 per cent and MAAS Group rose 7.93 per cent, while Lotus Resources fell 10.53 per cent. These percentage moves should be checked against company announcements and trading liquidity before attributing causes.
The Australian dollar was broadly flat at US70.38 cents. Spot gold was around US$4,280 an ounce, Brent crude approximately US$103.08 a barrel and iron ore near US$96.90 a tonne late in the session.
The rate outlook remains the central domestic catalyst. Labour-market weakness has not eliminated the possibility of an RBA increase next week, leaving banks, listed property and other rate-sensitive sectors exposed to changing expectations.
Market dashboard
S&P/ASX 200: 8,702, down 0.72 per cent.
All Ordinaries: 8,897, down 0.66 per cent.
Best sector: Energy, up more than one per cent.
Weakest areas: Real estate and materials were the major drags; confirm final sector percentages before publication.
Material winner: Premier Investments led the large-company gainers. Confirm its final closing move from the ASX before publication.
Material loser: Zip, down 11.38 per cent.
ASX 300 percentage leader: Myer, up 11.43 per cent.
ASX 300 percentage laggard: Zip, down 11.38 per cent.
AUD/USD: Approximately US$0.7038, broadly flat.
When the Writers Festival was called off and the skies refused to clear, one weekend away turned into a rare lesson in slowing down, ice baths included.
Powerhouse real estate couple Avi Khan and Kaylea Sayer welcome their daughter while balancing record-breaking careers, proving success and family can grow side by side.