A Rare Chance for Ferrari Aficionados to Own a Classic Model With Virtually No Miles

 3 min

If you like your Ferrari purchases to have only delivery miles on them, this sale might be for you.
What RM Sotheby’s is calling the Factory Fresh Collection includes 17 Ferraris, many barely driven, as well as a rare Jaguar XJ220 supercar, a highly desirable E-Type roadster, and a Bentley Turbo R Drophead Coupé. The auction takes place at Marlborough House in London on Nov. 4, coinciding with the famous London to Brighton run for pre-1905 veteran cars the next day.
OneSavage/sgcarshoot, courtesy of RM Sotheby’s
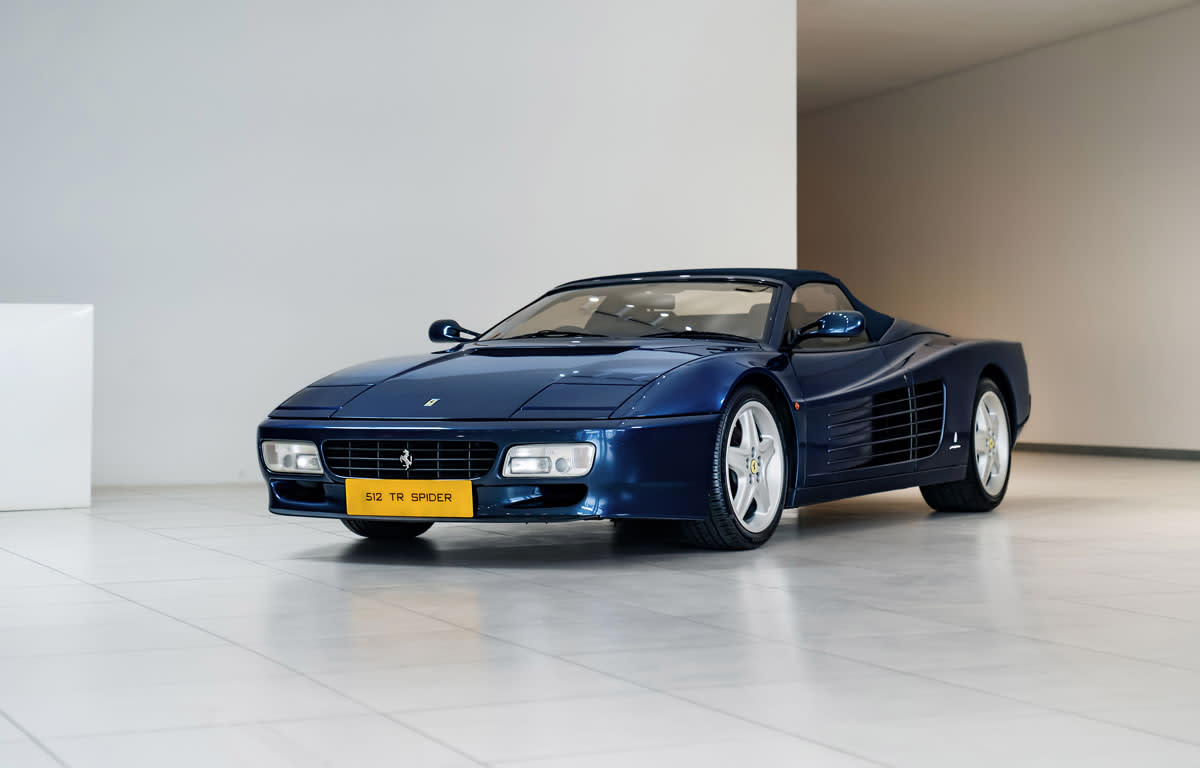
The star of the collection is probably the 1994 Ferrari 512 TR Spider, just one of three built that year, and the only one in its combination of Blu Cobalto paint and Blu Scuro Connolly leather interior. The odometer shows just 570 kilometres (354 miles). In keeping with the as-delivered theme, the car comes with its service book, technical manual, and a spare key. Provided it’s been serviced for the road, the owner will in effect be getting a new car. The estimate is £2.1 million to £2.7 million (US$2.56 million to US$3.3 million).
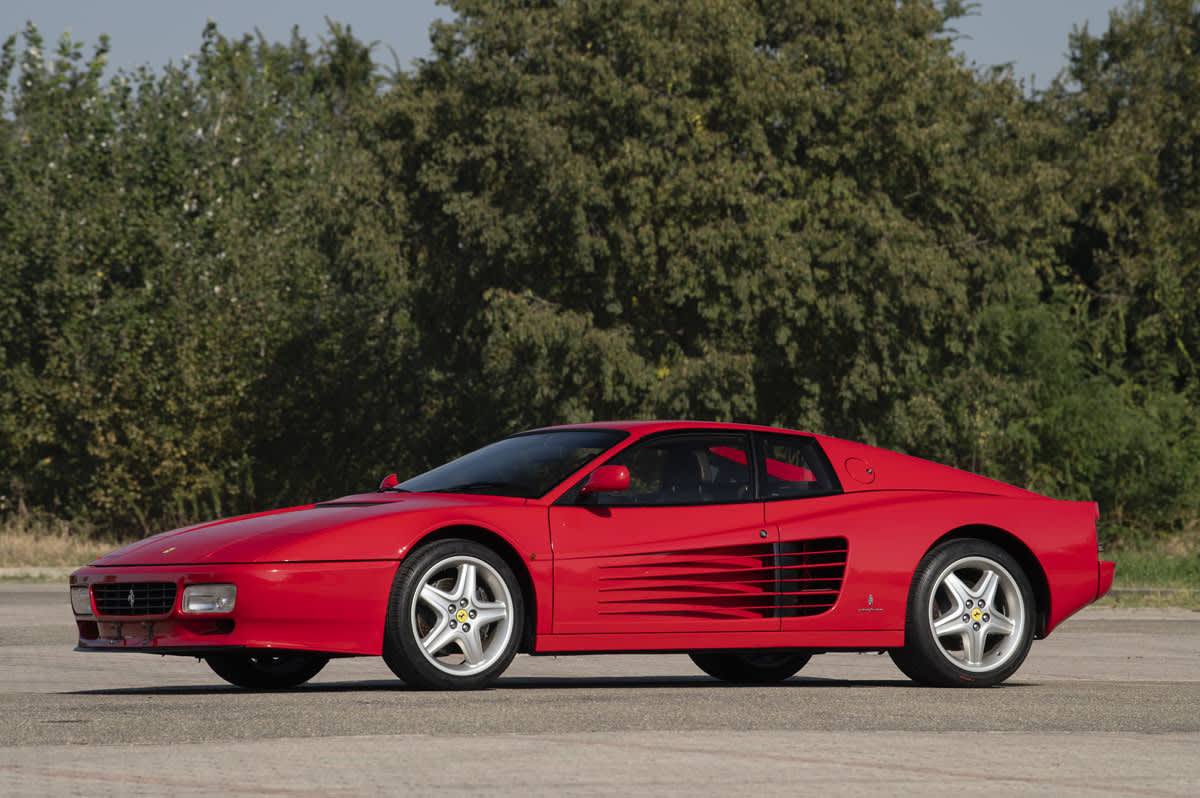
“This a truly remarkable collection,” Peter Haynes, RM Sotheby’s marketing and communications director for Europe, the Middle East, and Africa (EMEA), tells Penta. “There are some very rare cars in their own right, but the standout feature across the majority of the cars is the very low mileage—barely driven in some cases. My personal highlights include the 1994 Ferrari 512 TR Spyder which is one of just three in existence, in addition to the 1992 Ferrari Mondial T, which reads a hardly believable one kilometre on the odometer.”There are two other 512 TRs in the collection, a 1992 (also blue) and a second 1992 in U.K. specification (right-hand drive) with only 3,904 miles recorded. The first of these has a high estimate of £275,000 and the second £320,000.
Courtesy of RM Sotheby’s
The 1990 Ferrari Testarossa has a surreal 160 kilometres, and is one of just 438 built in right-hand drive. The high estimate is £200,000. The 2001 Ferrari 550 Barchetta Pininfarina (high estimate £350,000) was one of 48 built with drive on the right side, and has traveled only 220 kilometers. One of the two 2008 599 GTB Fioranos has covered only 267 kilometers—making it one of the lowest-mileage in existence. Its high estimate is £180,000.
Robert Cooper, courtesy of RM Sotheby’s
Other Ferraris in the collection with their recorded mileage: 1994 Mondial T Coupé (one kilometre); 1992 348 TS (130 kilometres); a second 1992 348 TS (179 kilometres); 2007 F430 (104 kilometres); 1994 348 GTB (181 kilometres); 1983 400i (2,743 miles). A highly admired earlier Ferrari is a numbers-matching 1973 Dino 246 GTS by Scaglietti. Its high estimate is £450,000.
(sgcarshoot, courtesy of RM Sotheby’s)
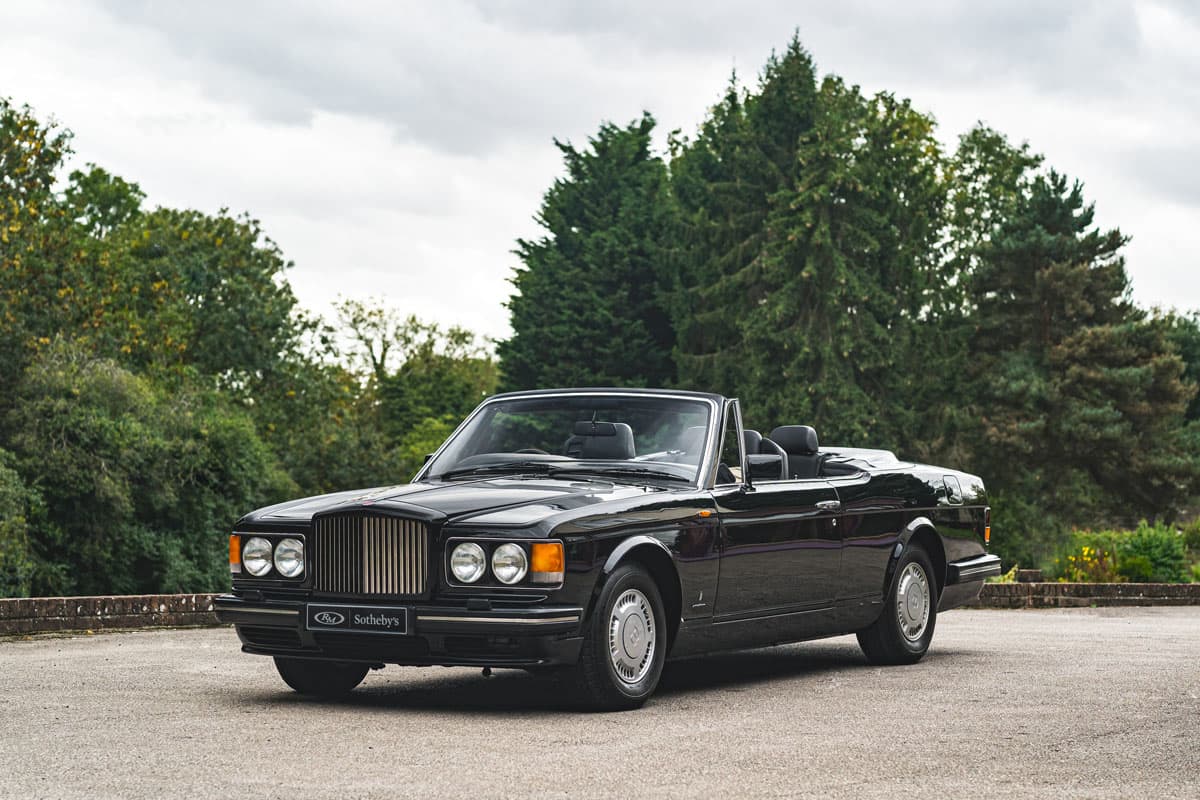
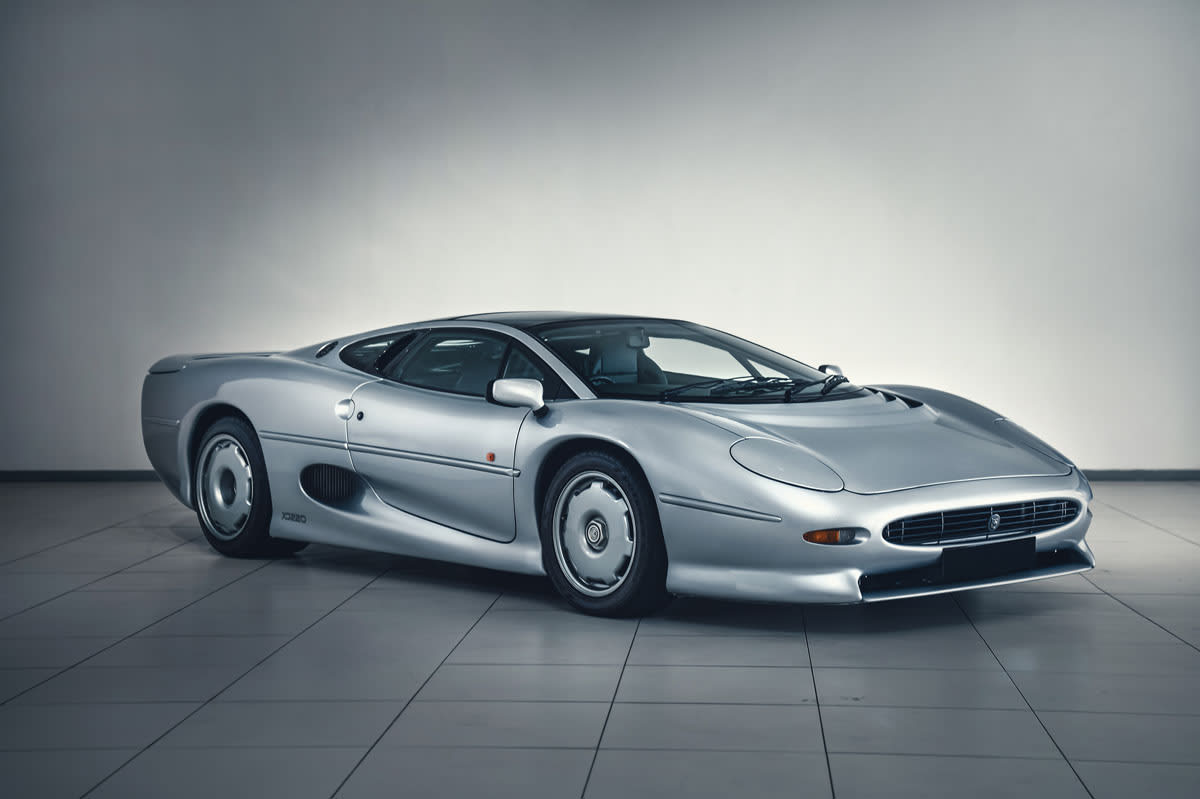
Non-Ferraris include a very rare 1993 Jaguar XJ220, one of 282 produced. In keeping with the sale, it shows only 46 miles on the odometer. It’s been recently recommissioned for spirited driving, and is high-estimated at £425,000. A 1969 Jaguar Series 2 E-Type Roadster is also being auctioned, as is a 1991 Bentley Turbo R Drophead Coupé. The Bentley convertible, which is just out of extensive refurbishment by London specialist P&A Wood, has a high estimate of £475,000.
Buyers have the choice of keeping these cars in the garage—and preserving their low-mileage status—or forgetting about all that and driving them with alacrity.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.
Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min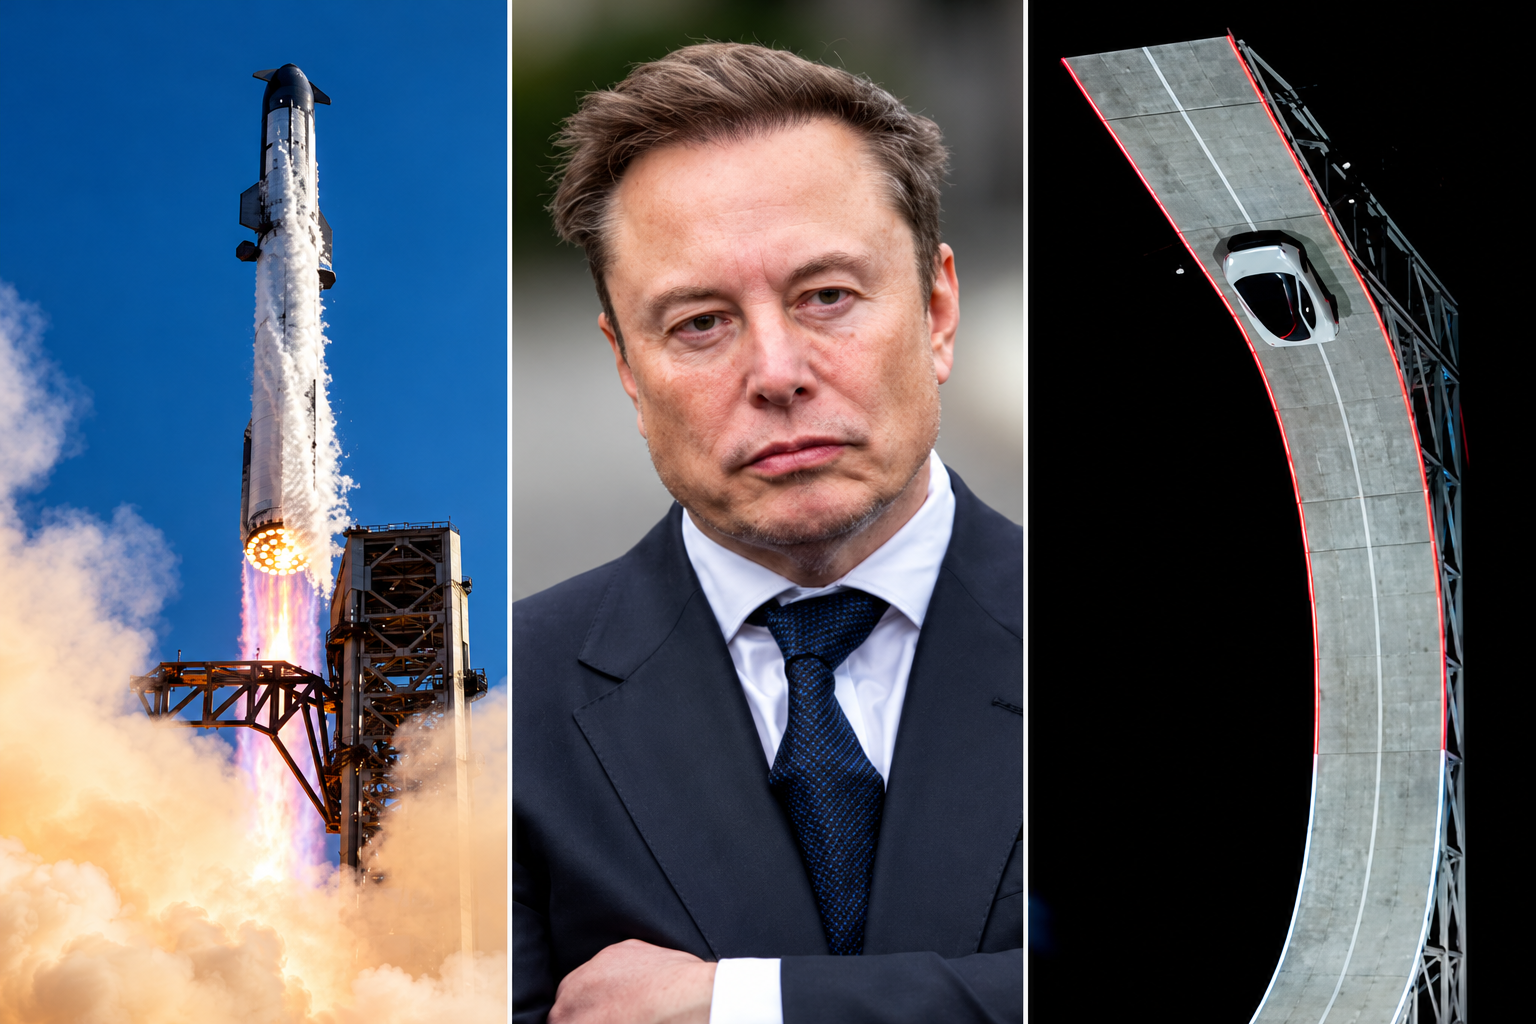
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.
As housing drives wealth and policy debate, the real risk is an economy hooked on growth without productivity to sustain it.

Travellers are swapping traditional sightseeing for immersive experiences, with Africa emerging as a must-visit destination.