Bats, Asbestos, a Leaky Roof: This English Estate Proved to be the Ultimate Fixer-Upper
Nobody wanted to buy Harpsden Court. But Ian and Gigi Wason took the ‘complete disaster zone’ head on, working little by little to turn it into a liveable home.

 6 min
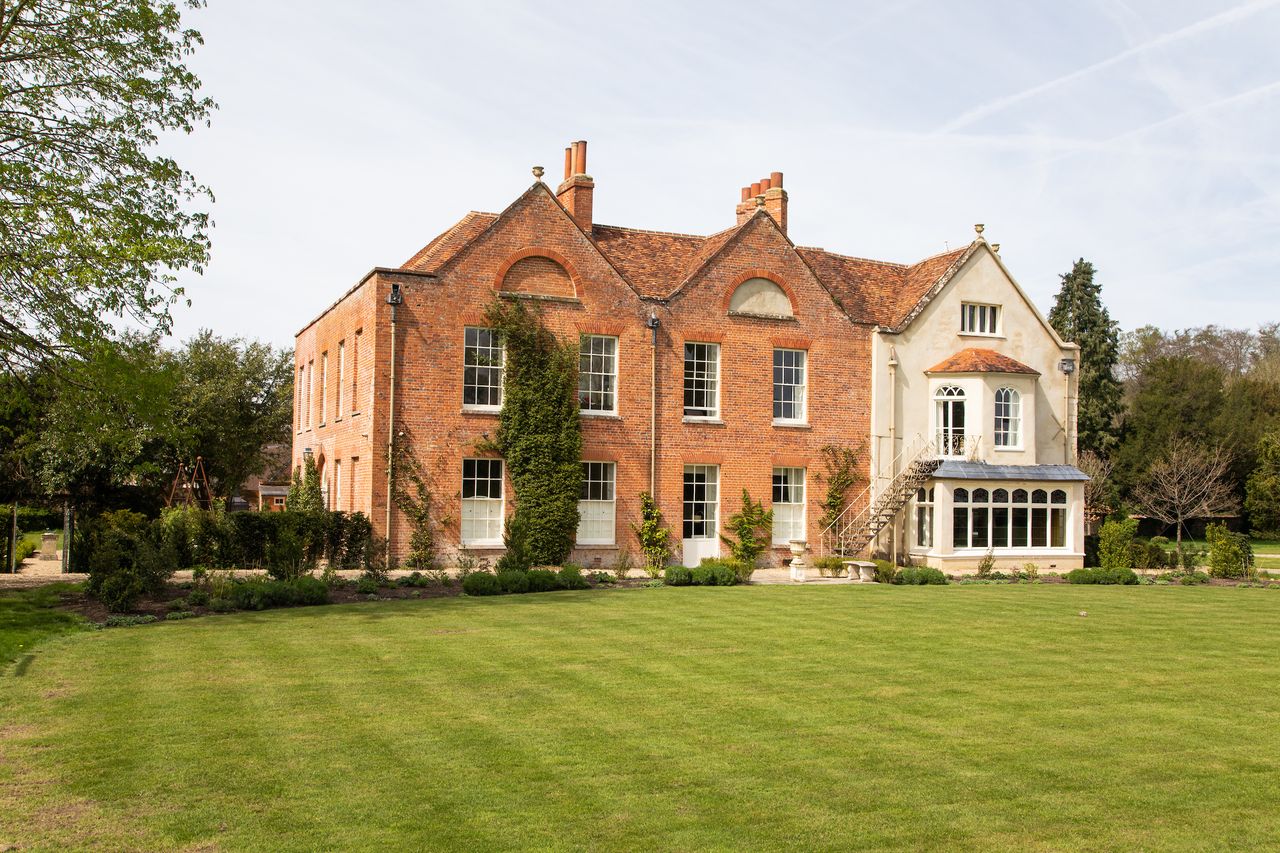
Growing up, Ian Wason often wondered what lay behind the tall stone walls surrounding Harpsden Court, a 400-year-old country estate close to his childhood home. It was many years before he discovered the answer: a beguiling but badly rundown, 17,000-square-foot landmark property in need of a multimillion-dollar restoration.
Despite the overwhelming scale of the project, he and his wife, Gigi Wason, fell for the charms of Harpsden Court, took on the project, and have reinvented it as a classic country home for their young family.
“It was basically semi-derelict when we first saw it,” said Ian. “Parts of it literally hadn’t been touched for almost 100 years and it had been on the market for four years. It was this complete disaster zone, which is why nobody bought it. We were the first and only people to put in an offer.”
Ian, 46, was raised 5 miles away from Harpsden Court, in the village of Medmenham, some 35 miles west of central London. After training as an accountant in London, he moved to Cape Town, South Africa, where he set up a debt counseling and financial-education company, and met Gigi, a 42-year-old interior designer.
In 2015, on a visit home to Ian’s parents, who were still living in Medmenham, he noticed that Harpsden Court was up for sale, listed for $16.43 million. He persuaded Gigi to go and have a look just to ease his curiosity.
What they discovered terrified them.
“It was overwhelming,” said Gigi. “It was obviously going to be such a mammoth project. You could see the sky through the roof, there was a whole zoo in the house—bats, crows, rats and mice—and it was dark and freezing cold.”
In 2017, Ian, Gigi and their daughters, Clementine, now 11, and Josephine, 9, returned to the U.K. They bought a house in London’s Notting Hill neighborhood, and welcomed another child, Madeline, now 5. But, over the next couple of years, Gigi started to hanker for more space than a London townhouse could offer. When Ian, who had always hoped to live in the country close to his family, mentioned the house was still for sale, and that its list price had been slashed to $11.42 million, Gigi agreed to another visit. This time around she was ready to appreciate the Gothic-style house.
Harpsden Court dates from the 17th century, according to Historic England, Britain’s official heritage organization. New sections were added to the house in the 18th and 19th centuries. According to the Henley Archaeological and Historical Group, the house was originally home to Lords of the Manor of Harpsden and, according to an ancient map of the area, there has been a house was on the site as far back as 1586.
It had been used as a location for a series of movies including “Quantum of Solace,” starring Daniel Craig, “The Woman in Black” with Daniel Radcliffe, and “Jude” starring Christopher Eccleston and Kate Winslet.
Outside, its 30 acres of gardens, woodland and fields easily outshone the tiny Astroturfed backyard of the Wasons’ London house. “It was like I saw the house with completely different eyes,” she said. “It was magical, and I was obsessed.”
In 2019, the couple paid $7.29 million for Harpsden Court, which came with three cottages and stables. The main house was habitable but not comfortable. Most of it had no central heating, the roof leaked, and Gigi describes the kitchen, fitted in the 1960s, as “unspeakably awful.” The property had 14 bedrooms, but only two bathrooms.
The Wasons hired the architect Ben Pentreath, who has worked for high-profile clients including King Charles and the Prince and Princess of Wales, and asked him for a light-touch modernisation plan.
“We did not want to lose the character of the house,” said Gigi. “I like designs which are timeless and I think that if you create something modern at some point it will tire.”
Pentreath suggested replacing the 1960s kitchen and adjacent open courtyard with a new, enlarged kitchen. The servant’s wing of the house, built in the Victorian era, was cramped and gloomy. “It was just a long corridor with loads of rooms off it, like the hotel in ‘The Shining,’ ” said Ian.
Pentreath recommended removing part of the first floor ceiling to create a galleried, double-height hallway with walls of painted brick and the original stone floors. To make the house more balanced, the number of bedrooms has been reduced to 10, and the number of bathrooms upped to six. Outside, the gardens needed re-landscaping, and the Wasons wanted a sauna and a swimming pool.
Work on the house began later in 2019. Alterations to landmark buildings in Britain require special building permits, which can take several months to obtain from local government planning departments, but they were permitted to get on with basic repairs such as the removal of carcinogenic asbestos insulation, installing a new roof, and restoration of the windows.
Removing asbestos from the roof was particularly difficult. “It was a very painful process,” said Ian. Before removal work could even begin, he had to commission an $14,000 report to determine whether there were any protected species of bats nesting in the roof space. These bats had to be carefully removed before a section of the roof was removed. “The asbestos removers then put on their hazmat suits and spent six weeks carefully removing the asbestos lagging from the heating pipes in the roof,” said Ian. This part of the work ate up $190,000, said Ian.
The backyard presented another challenge. It had been infested with highly invasive Japanese knotweed. The previous owners had tried to tackle the problem, said Ian, and had purchased a roughly $6,300, 10-year insurance policy to tackle any recurrence. Since the plant’s root network is notoriously hard to eradicate, contractors have to visit the property twice a year to spray and remove any new plants.
Back in the house, all the windows had to be removed, renovated, and reinstalled, adding another roughly $127,000 to the final bill. “We saved most of them, and where we couldn’t they were completely replaced with new oak windows,” said Ian.
Ian, who managed the construction himself, also oversaw the dredging of the ornamental lake in the grounds, and the installation of a ground source heat pump and central heating.
Then the electrics were tackled. “From the plans we had it had last been rewired in 1936,” said Ian.
Ian estimates that around a third of the total $7.6 million renovation budget was spent on these structural upgrades, carried out while the family remained living in London. Building permits were issued in spring 2020 for the alterations Pentreath had designed, and another third of the money was spent here. The final third went on decoration and finishes, overseen by Gigi who has created a comfortable country-house style home, with a soft and neutral color scheme.
Where possible the fabric of the house has been preserved. The flagstone floors, taken up when the new heating system was installed, were carefully re-laid. The decorative tiles around the range cooker in the kitchen were taken out of one of the original bathrooms, and as much of the original wallpaper as possible has been salvaged and restored. This, said Gigi, involved an artist spending six weeks at the house carefully redrawing patterns on water-damaged sections of the walls, and repainting them so that they blend seamlessly with the surviving sections of paper. The cost? Around $15,200, said Ian.
The first floor has a series of living rooms, a formal dining room, and a well-preserved original kitchen complex. Gigi now uses the main room of this complex for flower arranging and children’s arts and crafts, and there is also a hanging larder for preserving game birds, a pastry room, and a wine cellar.
There are three staircases leading to the second floor, the grandest of which is lighted by a stained-glass window depicting St George, the patron saint of England, battling a dragon. undefined One bedroom is dubbed the “Queen Mary” room, named by a previous owner for Queen Mary, who is rumored to have been a guest at the house.
This room has a four-poster bed, pretty tiled fireplace, and an exceptionally lavish en suite bathroom, with a free-standing wooden bathtub and wallpaper featuring oriental-style blossom trees. The principal bedroom is equally splendid with its bespoke hand-painted wallpaper by de Gournay featuring swans and white peacocks, a gilded French-style bed, and soft green silk moiré drapes.
The house contains many surprises; a bookshelf in Ian’s office is a hidden door leading to the original gun room, and if you look closely at the restored wallpaper in an upstairs hallway, a confection of fruit, berries and birds, there is a tiny naked nymph added by a previous resident, plus three miniature fairies Gigi had painted in honor of her daughters.
By Christmas 2021, two years after the reconstruction began, the family, plus dogs Tess and Charlie, were able to move into the Victorian wing, which was completed first. They have kept their London property for when Ian needs to be in London for work and for family trips.
Since then, Ian’s parents have moved into one of the cottages. Gigi’s cousin and her husband live in another.
Ian estimates that although $7.6 million has been spent on the renovation so far, more than the house cost to buy, that sum will keep going up. At the start of the year, for example, a section of the decorative domed ceiling in the music room—a second-floor reception area—collapsed unexpectedly and awaits repair. Work to shore up the stone walls in the garden is ongoing. And Gigi hasn’t got around to designing several of the guest bedrooms to her satisfaction.
“This project is going to go on forever,” she said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



Porsche’s Cayenne Turbo Electric produces up to 1,156PS and reaches 100km/h in a claimed 2.5 seconds.

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
Rising Australian bond yields are putting pressure on listed property and the cost of capital. Here’s why A-REITs can signal changes in property valuations before the direct market moves.
4 min
Most property investors spend considerably more time watching interest rates than bond markets.
That makes sense. The Reserve Bank cash rate has an obvious relationship with mortgage repayments, borrowing capacity and investor sentiment, while government bonds can seem far removed from what someone will pay for an apartment in Sydney or an office building in Melbourne.
But the bond market can provide one of the earliest indications that the price investors are willing to pay for property is changing.
That became evident last Thursday, when Australian shares suffered their worst trading session in months. The S&P/ASX 200 fell almost two per cent, with property among the rate-sensitive sectors caught in the sell-off as government bond yields moved sharply higher.
Australia’s 10-year government bond yield pushed to around 5.4 per cent, close to its highest level in 15 years, against a backdrop of rising global yields and renewed concern about inflation and the direction of interest rates.
For property investors, that matters because the government bond yield is effectively one of the reference prices for money.
An investor buying an Australian government bond is receiving a return while taking comparatively little credit risk. Property comes with tenants, vacancies, maintenance, leasing costs, illiquidity and the possibility that the underlying asset falls in value, so investors generally expect to be compensated for accepting those additional risks.
A property yielding five per cent therefore looks considerably more attractive when a 10-year government bond yields three per cent than when that same bond is yielding more than five per cent.
That does not mean property values automatically fall every time bond yields increase. Rental growth, scarcity, lease structures and the quality of an asset can all outweigh movements in rates, but it changes the return investors require and therefore what they may be prepared to pay.
SG Hiscock & Company made that point in an ASX Investor Update, arguing that real, or inflation-adjusted, bond yields can be particularly relevant to property because real estate is fundamentally a long-duration investment whose value is derived from future income.
The first place investors can often see that repricing is the sharemarket.
A house or commercial building does not have a price that changes every few seconds. An Australian real estate investment trust does.
A-REITs can own billions of dollars of shopping centres, offices, warehouses and other property, but their securities trade continuously on the ASX. When expectations around interest rates and bond yields change, investors can immediately alter what they are willing to pay for those property earnings.
That can create a situation where the value attributed to a portfolio on the sharemarket falls even though the underlying buildings have not changed hands and their independent valuations remain unchanged.
The two markets simply move at different speeds.
Mark Ferguson, Head of Charter Hall Maxim Property Securities, has previously described direct property valuations as lagging the listed market. Writing for Charter Hall during an earlier period of rising interest rates and bond yields, Ferguson noted that listed property was already pricing increases in capitalisation rates and falls in underlying property values before those adjustments had fully emerged in direct-market valuations.
The effect can be substantial.
Consider a commercial property producing $1 million a year in net operating income. At a five per cent capitalisation rate, that income implies a value of $20 million.
If investors subsequently require a 5.5 per cent return while the property’s income remains unchanged, the implied value falls to around $18.18 million. At six per cent, it falls again to roughly $16.67 million.
Nothing necessarily happened to the building. It could have the same tenant paying the same rent under the same lease. What changed was the return required by the person buying it.
That is also why income growth becomes so important.
A well-located property with constrained supply and strong rental growth can increase its earnings quickly enough to absorb some of the pressure from higher required returns. An ageing office building facing vacancies, refurbishment costs and an approaching debt refinancing could instead be hit from several directions at once.
Debt adds another dimension because property is one of the economy’s most capital-intensive asset classes.
Higher market rates can increase the cost of financing an acquisition or refinancing existing debt while simultaneously increasing the return investors expect from the property itself. For developers, the consequences can be even more pronounced because higher construction finance costs can coincide with lower anticipated end values.
If that happens, a project can be squeezed from both directions: it becomes more expensive to deliver at precisely the time investors become less willing to pay yesterday’s price for the finished asset.
The direct property market generally takes longer to reveal that adjustment.
An A-REIT can lose five per cent of its market value in a trading session. An office building may not transact for another year. Owners can reject lower offers, transactions can be withdrawn and valuers must wait for comparable sales to establish new evidence.
That lag is one reason listed property can be useful even for investors who have no intention of buying a REIT.
The same principle eventually extends to residential property, although houses and apartments are generally valued using comparable sales rather than capitalisation rates.
Residential property is particularly sensitive to credit. Higher bond and swap rates can influence bank funding and fixed mortgage pricing, while higher borrowing costs reduce the amount households can service.
If prospective buyers can borrow less, the number of people capable of paying yesterday’s price can shrink. Vendors may initially resist that adjustment, resulting in fewer transactions rather than immediate price falls, before motivated sales eventually establish new comparable values.
For investors, rental growth can provide an important buffer. Rising rents can help offset higher financing costs, just as increasing commercial rents can compensate for some expansion in capitalisation rates. Investors relying primarily on capital growth while accepting a low rental yield have considerably less protection when the cost of money rises.
That is why movements in listed property and bond markets deserve attention beyond the trading floor.
They provide a constantly updating view of how investors are pricing interest rates, debt, future income and property risk, often months before those changes become obvious in direct transactions.
For an A-REIT investor, that means looking at gearing, debt maturity, hedging, interest cover and the discount or premium to net tangible assets rather than simply chasing the highest distribution yield.
For a commercial property investor, it means testing what happens to valuations if capitalisation rates move 25, 50 or 100 basis points higher.
For residential investors, it means understanding mortgage costs, borrowing capacity, realistic rental income and how much of the investment case relies on future capital growth.
The cash rate will continue to attract most of the attention in Australian property. But investors looking for an earlier indication of how the market is repricing risk should also be watching the bond market.
Property prices might take months to respond to a changing financial environment. The price of money moves considerably faster.

Hand-built in Melbourne and limited to just 10 cars a year, the Zeigler/Bailey Z/B 4.4 is reshaping what a modern collector car can be.
As housing drives wealth and policy debate, the real risk is an economy hooked on growth without productivity to sustain it.