

When good debt turns bad
For the first time since the GFC, the fragility of the global banking system has come into question as the 16th largest bank in the US collapsed, and one of Europe’s premier investment banks, Credit Suisse, sought rescue from the Swisse National Bank.
How is it that a bank with a 166-year history, managing $1.6 trillion only a year ago, rapidly came crashing down?
 8 min
OPINION:
The Beginning of Our Troubles
As a response to the emergency financial and health environment caused by COVID-19, central banks around the world dropped interest rates to an all-time low and provided generous fiscal programs to businesses on a scale we have not previously witnessed. Quantitative easing (‘QE’) was applied to buy existing bonds and provide market liquidity, whilst governments issued new Treasury Bonds to raise the much-needed capital for these emergency COVID-19 programs.
The sheer scale of this coordinated global economic response completely dwarfs the measures used by governments during the GFC (approximately 6.5x in size and scale across developed countries). In the aftermath, we Australians now find ourselves fighting the steepest inflation in over three decades. It is my belief that this period will be studied by economic historians with the tagline and conclusion – “Excess money supply equals high inflation” – affirming the late Milton Friedman’s own body of work into this subject matter.
As the old saying goes – “There is no such thing as a free lunch”; we are certainly paying for it now. We are paying for dinner as well – WITH dessert.
Banks Buying up Treasury Bonds
The COVID-19 stimulus packages led to banks around the world seeing increased deposits. With the banks needing to invest this surplus money somewhere, and the lending environment not being favourable to them, the banks resorted to purchasing newly issued government bonds at near-zero coupon rates. Buying treasury bonds was encouraged by regulators and was seen as prudent practice given that the treasury bond is one of the least risky assets to hold on your balance sheet amid a financial crisis. This low risk is due to the government essentially being a guarantor of the capital – in other words, the government will give you back your money with certainty. Buying treasury bonds also has the benefit of meeting the capital adequacy requirement imposed by regulators.
It has surprised everyone that the economy recovered so rapidly, fuelled by pent-up demand and surplus savings. Unfortunately, this fast-paced recovery unleashed inflation, leading to the fastest and most consecutive interest rate increases in Australia’s modern economic history.
Now, let us shift our focus back to the so-called “risk-free” treasury bonds. Most government bonds have a fixed income stream linked to the official interest rates at the time of issue. As the official cash rate increases, these assets diminish in value. The S&P/ASX Australian Government Bond Index has shown a greater than 10% fall since August 2021, with some of individual bonds falling in value up to 20%
If the income stream for a government bond is say, 1%, this would be less attractive than the current cash rate of 3.60%. Therefore, the face value (price) falls as the cash rate rises, allowing the bond to be traded with the appropriate numbers. Despite this, government bonds are still safe and secure. The government’s sovereignty backs the income stream. It is easily traded in the money market and considered as good as liquid cash for banks, with regulators requiring significant exposure to these instruments as part of the credit creation function performed by banking institutions. For example, every dollar held in bonds, allows four dollars to be lent to borrowers.
The Misleading Safety of Government Bonds
Here comes the iceberg. The only asset on the bank’s balance sheet that does NOT reflect actual value is government bonds. This is due to accounting standards and reporting requirements; that is, we do not know the exact scale or concentration of government bonds held on the balance sheet of any particular bank. There are now two issues at hand here: profitability and liquidity. Poor profitability relates to the fact that the bank has poorly performing returns on assets relative to returns available on other similar assets in the market. As a result, it will need to squeeze this extra profit from somewhere else, most likely from the borrower, thus increasing the cost of capital.
While this occurs, banks are increasingly concerned about the borrower’s side of the ledger. Banks must be wary of loan arrears picking up at an alarming pace due to the higher interest rates, cost of living pressures and asset prices falling due to rising interest rates. Therefore, there is ‘credit rationalising’ by lenders. In other words, they are getting tougher and reluctant to lend new money; a classic recipe for an inevitable credit crunch.
The second half is banks that are overweight in government bonds trading below their fair value are particularly vulnerable if there is a run on their money; that is, a very large number of depositors wanting to withdraw their money in a short time frame and the bank not having the cash available to satisfy this demand immediately. This is a major liquidity issue for the particular bank in question, as well as the entire banking system if the flow-on effect is of sufficient magnitude. The commonalities between the GFC and the current crises are confidence and liquidity. However, the difference is that the GFC was predominantly caused by banks holding bad loans.
The cause of this current crisis is that banks are holding too many good loans (government bonds) that have now turned bad due to their fixed rates during a time of rapidly rising rates.
Mary Poppins and the Collapse of SVB
Just as Mr Banks in the Mary Poppins film tries to teach his son the importance of saving and investing money wisely, banks also encourage customers to deposit their money and keep it safe in their accounts. However, if there is a sudden panic or loss of confidence in the banking system, customers may rush to withdraw their money all at once, similar to how Michael Banks ran to spend his tuppence feeding the birds.
The lesson here is that just as individuals need to save and invest wisely, it is also essential for banks and regulators to maintain a stable and trustworthy financial system that can withstand sudden shocks and crises. Due to the sudden increase in interest rates, many banks have become vulnerable and illiquid. The very purpose of government bonds held on their balance sheet is to provide liquidity. However, as has been made evident in the past few weeks, this basic contingency plan has failed.
In the case of Silicon Valley Bank (SVB) in the US, the bank announced that it had lost $1.8b in the fire sale of assets to meet withdrawal demands. The bank then looked to raise $2.25b to shore up its balance sheet and restore investor confidence in the bank’s liquidity and operations. Within 48 hours, an astounding sum of $48b had been withdrawn from the bank out of fear and panic. This placed the financial institution on a pathway to collapse as further sales of government bonds could not be sustained.1
This led to other regional banks looking vulnerable. A central bank would only dare pause increasing interest rates if the act upholds confidence. However, this economic environment certainly supplies ample justification. The fragility of the banking system relies on deposit holders maintaining sufficient confidence in the banking system and wider economy. Raising interest rates leads to devaluing bond portfolios, only making banks more vulnerable and placing additional pressure on them to withstand a run on their capital, placing the entire banking system in jeopardy. Importantly the US Treasury has guaranteed all deposits in these banks to restore confidence in not only the national banking system, but the expansive regional banking system in the US.
Contagion and Credit Suisse
Although the ultimate demise of Credit Suisse was well on its way before the more recent events, the collapse of SVB put the final nail in in the Swiss bank’s coffin by escalating a run on depositor funds. Despite its share price having slumped for quite some time due to multiple scandals, including losses on highly leveraged loans to drug dealers to launder money in Bulgaria, entanglement in a Mozambique corruption case, the collapse of Greensill Capital and the failure of New York-based investment firm Archegos Capital Management.
All of these problems led to billions being lost by the bank. Despite disastrous past performance, if there had been no run on capital, the bank would have survived as it was still adequately capitalised. The Swiss government intervened in the Credit Suisse matter by placing UBS into a forced marriage with them through the provision of a handsome dowry (providing a $162b line of credit) paid by taxpayers, whilst wiping out $25b in bondholders (debt investors) and paying $4.9b (a steal) to shareholders in priority to the bondholders.
This breaks so many rules. Firstly, how can shareholders be paid in priority to bondholders whilst using the Swiss government’s money for the commercial benefit of UBS? Secondly, how is it paid for via QE?
The issuance of government bonds is only more inflationary. The unintended consequences of this action can be quite significant. Firstly, the Swiss government’s intervention undermines trust in the system; investors are less likely to invest in banks and this compounds fear for the next bank that misses expectations, with a potential run on capital to follow.
We have already been seeing some concern with Deutsche Bank following the controversy around bondholders being given priority in the aforementioned Credit Suisse saga. This is despite Deutsche Bank’s business fundamentals being in much better shape than that of Credit Suisse.
Australian Banks and the Future
Unsurprisingly, Jim Chalmers, Philip Lowe and John Lonsdale (chairman of APRA), have all come out in unison, stating that Australian banks are the strongest globally. Indeed, Australian banks are operating in an oligopolistic environment which is well regulated and funded, backed by an economy based on vast resources and immigration. The oligopoly feature of our banking environment works in our favour as it means lower competition, hence less of a necessity to lower rates and sacrifice margin in conjunction being highly regulated with capital. On the other hand, the US has over 4,200 banks and Europe has 5,171 banks.17 The small ecosystem in which Australian banks operate are the reason they are both highly profitable and there is need to take higher risk, with the regulators being able to keep close eye over the banking system.
Our banks will continue to attract depositor funds and have sufficient capital to meet withdrawals. In other words – WE ARE SAFE.
However, the world’s central banks are now fighting two separate battles on two separate fronts: inflation on the one side and fragility in the banking system on the other, which is weakened by higher interest rates and diminished confidence. It is our view that we have reached the top of the interest rate cycle. The importance of the May budget has not been this critical for decades. The government needs to be fiscally responsible in their coming budget to ensure they do not add to inflation, and the RBA may need to accept slightly higher inflation even if it is persistently above 3% for the next 2-3 years so as to not trouble the government bonds held by our banks.
In short, I expect the cash rate to remain unchanged at 3.60% for at least 4-6 months.
Final Thoughts
In the past month, we have seen a change in tone. The government is cooperating in its obligation to create a policy that helps not inflame inflation. In contrast, Philip Lowe has raised concerns regarding housing and rental inflation directly caused by a lack of property supply and increased migration. This is the government’s responsibility, which paves the way to accept higher inflation as long as wage inflation is anchored.
Ultimately, disciplined fiscal and monetary policy is required on the Australian front to ensure our banks are healthy, inflation is kept at bay, and that banking troubles in the rest of the world do not reach our shores. There is no doubt that that recent new bank collapses have completely changed the scope in which the central banks are operating within, ultimately this will lead to a credit crunch, increasing the cost of capital as banks will need and want to increase margins for risk, this will slow down the economy. Rather than worrying about higher interest rates we might have official cash rates drop quicker than anticipated.
Msquared Capital is a private credit provider with investment opportunities backed by quality property along the Eastern Seaboard; we ensure that all investment opportunities are based on risk-to-reward as our core offering and performance. Mortgage funds perform well during volatile times, and the preservation of capital is regular, with reliable monthly income that gives our investors peace of mind.
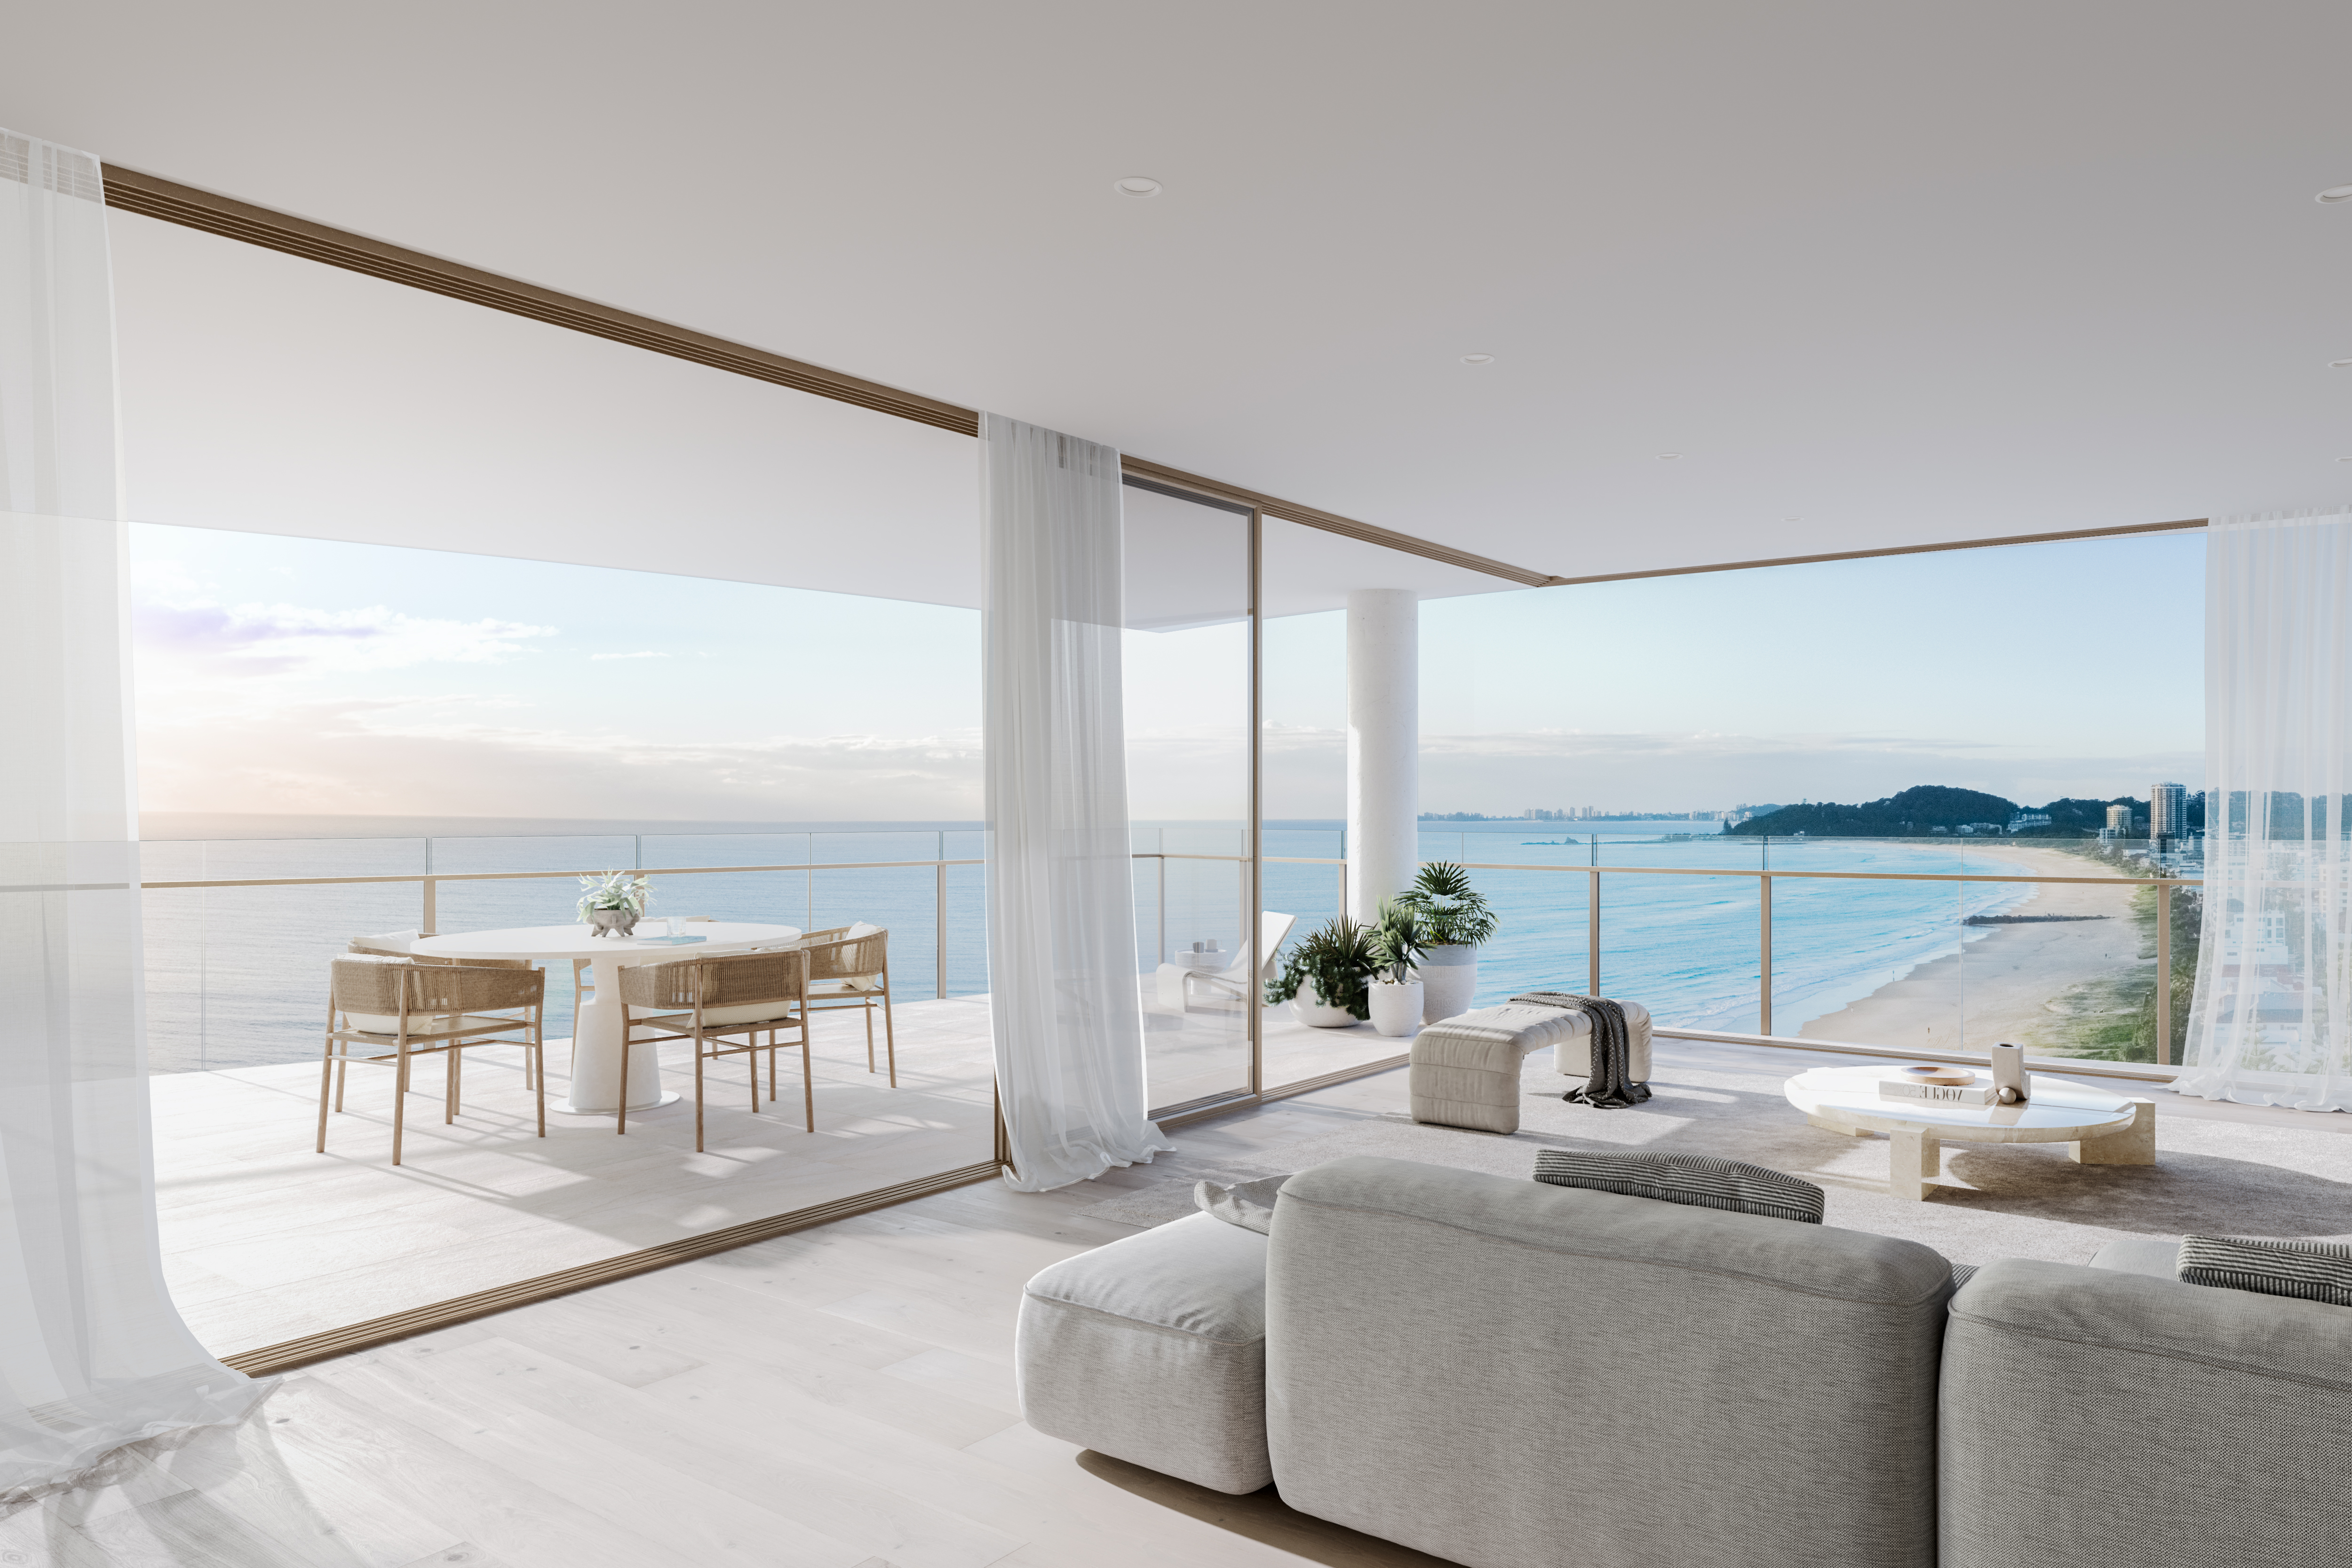
A Sydney couple has paid $15.5 million for the Grand Penthouse at Marquee’s $285 million La Belle Residences beachfront development which is nearing completion at Palm Beach, eclipsing the record for an off-the-plan apartment sale on the southern Gold Coast. The sprawling single level 640 sqm beachfront residence, with sweeping views of the Gold Coast …
Continue reading “$15.5m La Belle Penthouse eclipses southern Gold Coast record”
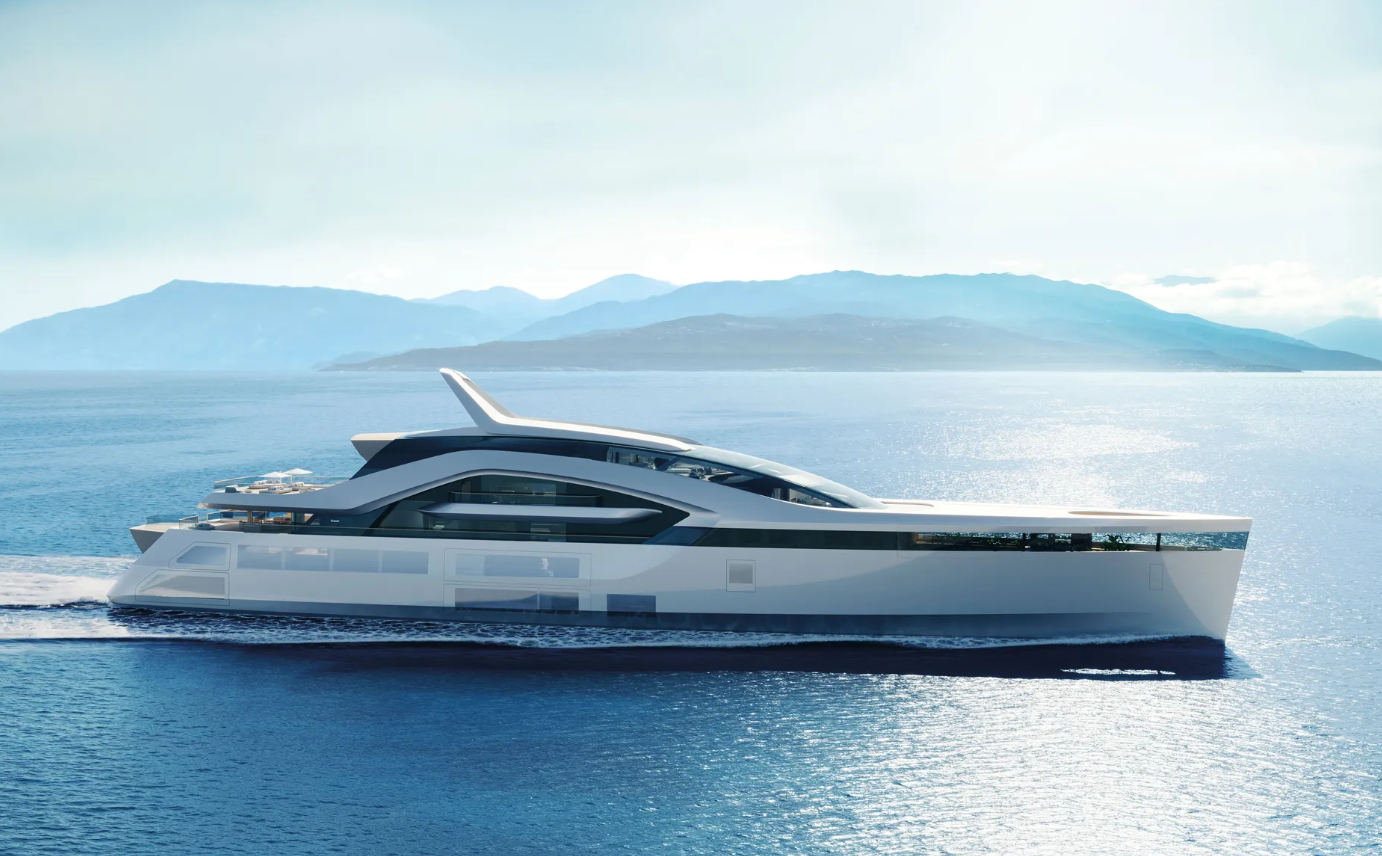
On the owner’s deck, a 20-metre swimming pool incorporates Feadship’s patented ContraWave technology and extends indoors as a suspended, glass-bottomed infinity pool.
A new study models a potential $80.6 billion lift in Australian GDP after a decade, as national testing shows a decline in Year 10 digital literacy.
2 min
Australia trails Singapore and Malta in a new Commonwealth index, while national testing shows fewer than four in 10 Year 10 students meet the standard for digital literacy.
Australia has ranked third among 56 Commonwealth countries for youth AI readiness, with researchers estimating that artificial intelligence could lift the level of Australian GDP by $80.6 billion after a decade under their middle scenario.
The Ayre Think Tank released the index at the Commonwealth Heads of Government Meeting in Antigua and Barbuda. Australia scored 71 out of 100, behind Singapore on 77.6 and Malta on 75. The United Kingdom followed closely on 70.8, with Canada fifth on 70.2. Only 15 countries reached the study’s benchmark of 53.
What the $80.6 billion figure measures
The researchers applied International Monetary Fund estimates for broad groups of economies to Australia’s 2025 GDP. The resulting scenarios put the potential lift in Australian GDP after 10 years at between $40.9 billion and $120.3 billion, with $80.6 billion representing the midpoint.
The figures describe how much larger the economy could be at the end of the period under each scenario. They represent a change in the level of GDP in year 10.
Digital literacy falls as schools roll out AI tools
Australia scored 8.7 out of 10 for access to technology and 7.5 for digital, data, media and AI capability. Separate national testing found that 37 per cent of Year 10 students met the proficient standard for information and communications technology literacy in 2025, down from 46 per cent in 2022. About one in 10 students reported receiving substantial teaching on AI-related tasks. National assessment results
The report points to two state initiatives aimed at building those skills. Queensland began rolling out an AI education platform in state schools in 2026, while Victoria introduced free specialist training for workers looking to develop AI skills or move into related roles.
The index draws on 1,128 sources and examines the conditions facing people aged 15 to 29, including access to technology, education and pathways into work. Australia had usable data for 76 of the 102 indicators used in the rankings. The researchers found too little comparable evidence to score an eighth area covering critical judgement and people’s ability to exercise control over AI systems.
Professor C. Justin Robinson, campus principal of the University of the West Indies’ Five Islands Campus, said young people should be equipped to question and improve AI tools and supported in building alternatives suited to their needs.
The report calls for affordable access to technology, more practical education and stronger links between training, employment and entrepreneurship. It also urges governments and educators to support AI tools suited to local languages and give young people ways to challenge automated decisions.
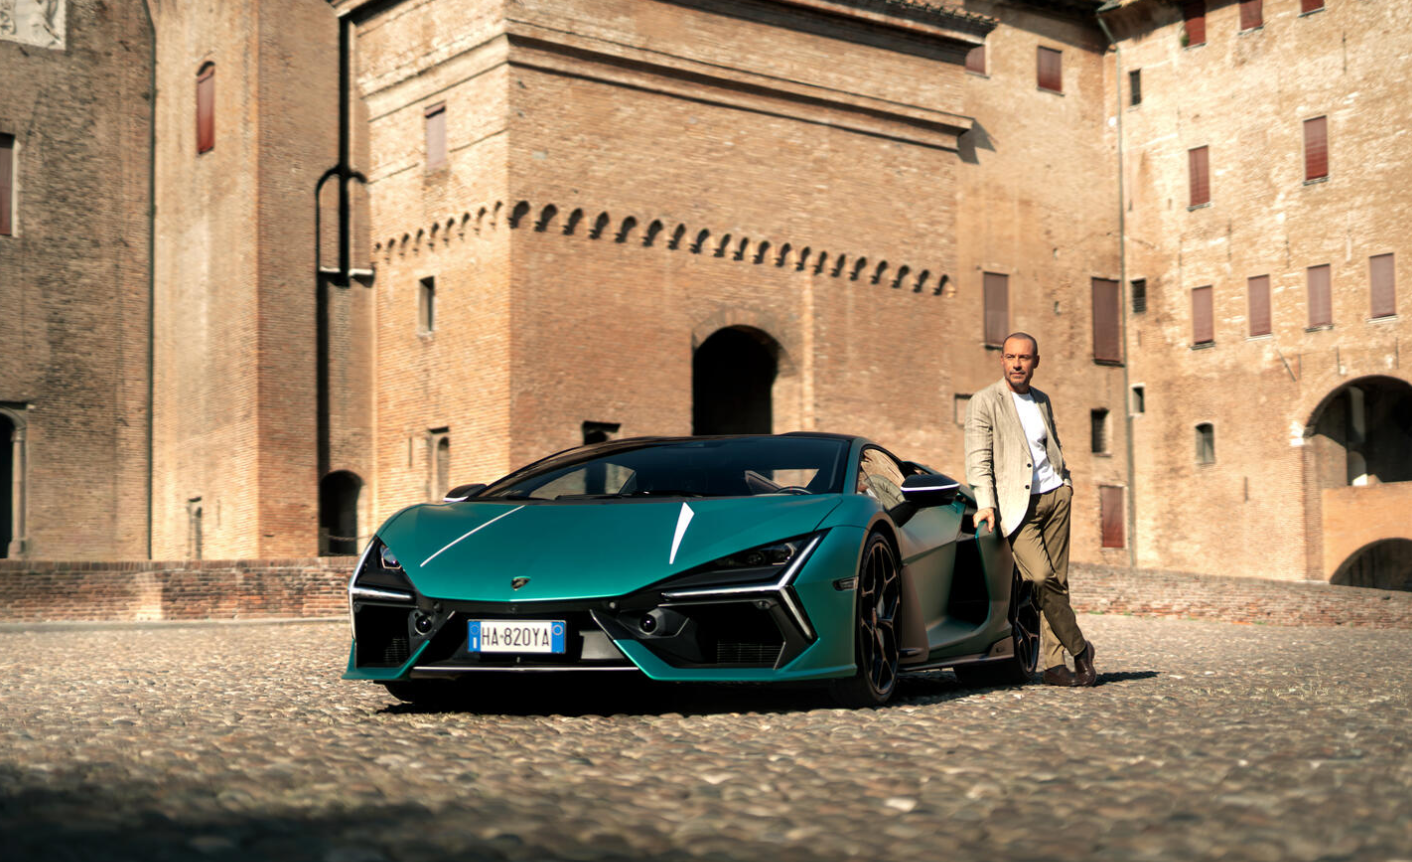
Automobili Lamborghini is turning its attention to something considerably more difficult to define: what makes Italian excellence uniquely Italian?
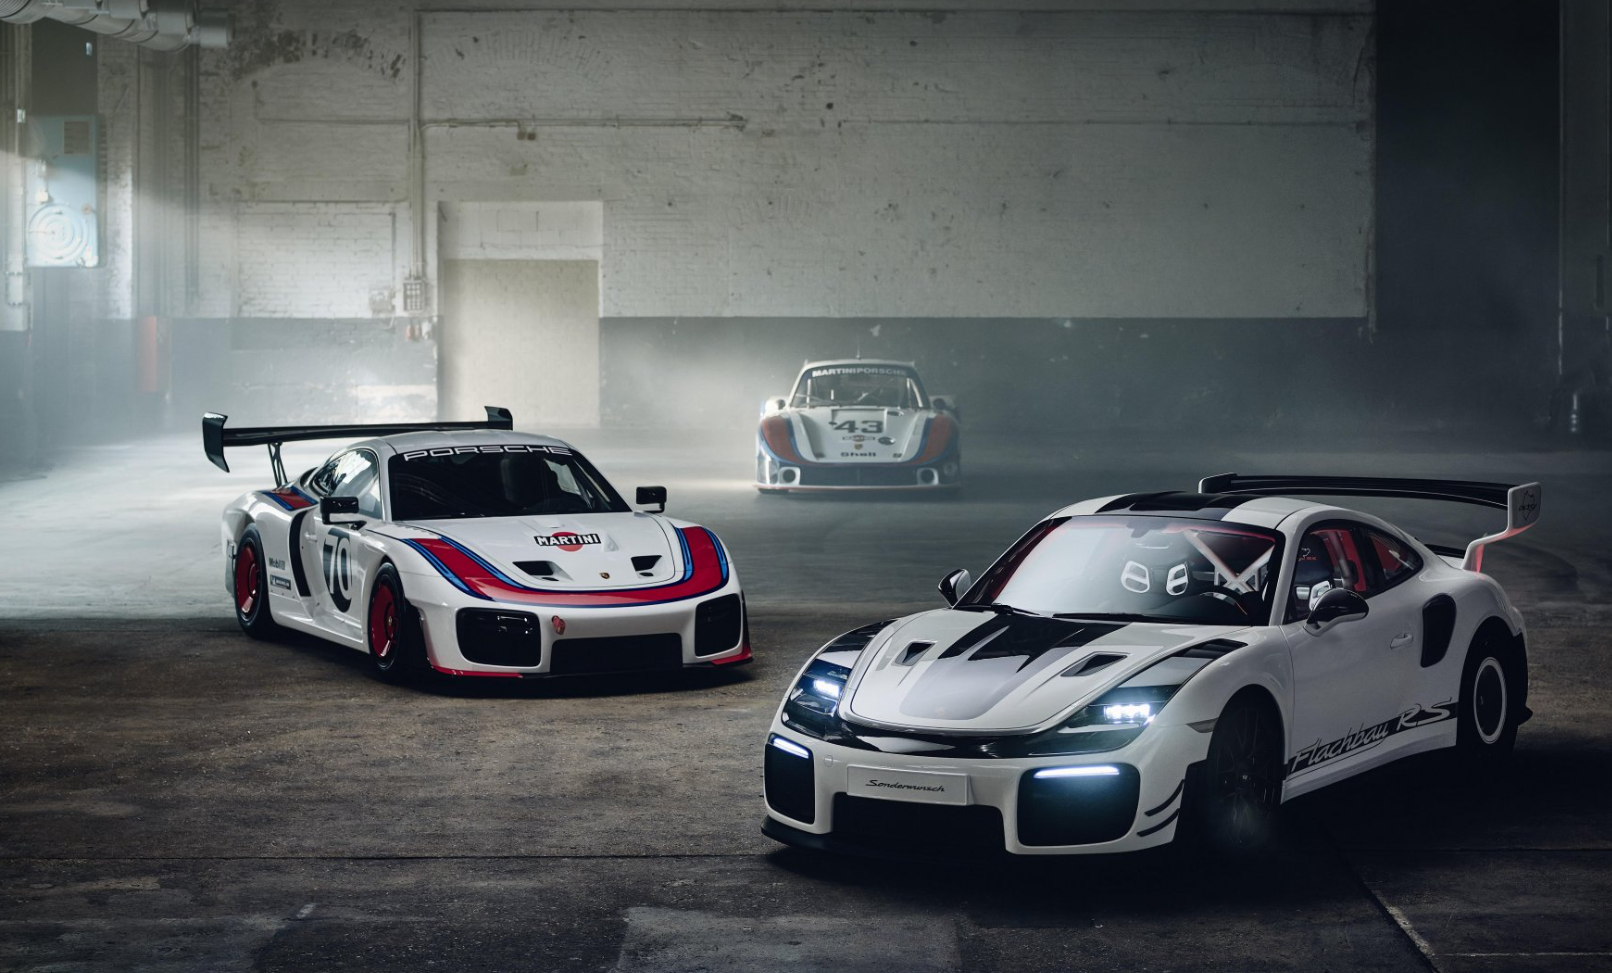
Porsche has revealed a one-off 911 GT2 RS that brings the extraordinary silhouette of its 935/78 “Moby Dick” racing car onto the road. Created by Porsche Sonderwunsch with Manthey, the commission began with a near-new GT2 RS. The owner requested greater performance, a Slantnose profile and a rear wing influenced by the limited 911 GT3 …
Continue reading “Porsche Builds a Road-Going “Moby Dick” From a 911 GT2 RS”