Where Are Stocks, Bonds and Crypto Headed Next? Five Investors Look Into Crystal Ball
Equities are often seen as expensive after promising start to 2023

 7 min
A new trading year kicked off just weeks ago. Already it bears little resemblance to the carnage of 2022.
After languishing throughout last year, growth stocks have zoomed higher. Tesla Inc. and Nvidia Corp., for example, have jumped more than 30%. The outlook for bonds is brightening after a historic rout. Even bitcoin has rallied, despite ongoing effects from the collapse of the crypto exchange FTX.
The rebound has been driven by renewed optimism about the global economic outlook. Investors have embraced signs that inflation has peaked in the U.S. and abroad. Many are hoping that next week the Federal Reserve will slow its pace of interest-rate increases yet again. China’s lifting of Covid-19 restrictions pleasantly surprised many traders who have welcomed the move as a sign that more growth is ahead.
Still, risks loom large. Many investors aren’t convinced that the rebound is sustainable. Some are worried about stretched stock valuations, or whether corporate earnings will face more pain down the road. Others are fretting that markets aren’t fully pricing in the possibility of a recession, or what might happen if the Fed continues to fight inflation longer than currently anticipated.
We asked five investors to share how they are positioning for that uncertainty and where they think markets could be headed next. Here is what they said:
‘Animal spirits’ could return
Cliff Asness, founder of AQR Capital Management, acknowledges that he wasn’t expecting the run in speculative stocks and digital currencies that has swept markets to kick off 2023.
Bitcoin prices have jumped around 40%. Some of the stocks that are the most heavily bet against on Wall Street are sitting on double-digit gains. Carvana Co. has soared nearly 64%, while MicroStrategy Inc. has surged more than 80%. Cathie Wood‘s ARK Innovation ETF has gained about 29%.
If the past few years have taught Mr. Asness anything, it is to be prepared for such run-ups to last much longer than expected. His lesson from the euphoria regarding risky trades in 2020 and 2021? Don’t count out the chance that the frenzy will return again, he said.
“It could be that there are still these crazy animal spirits out there,” Mr. Asness said.
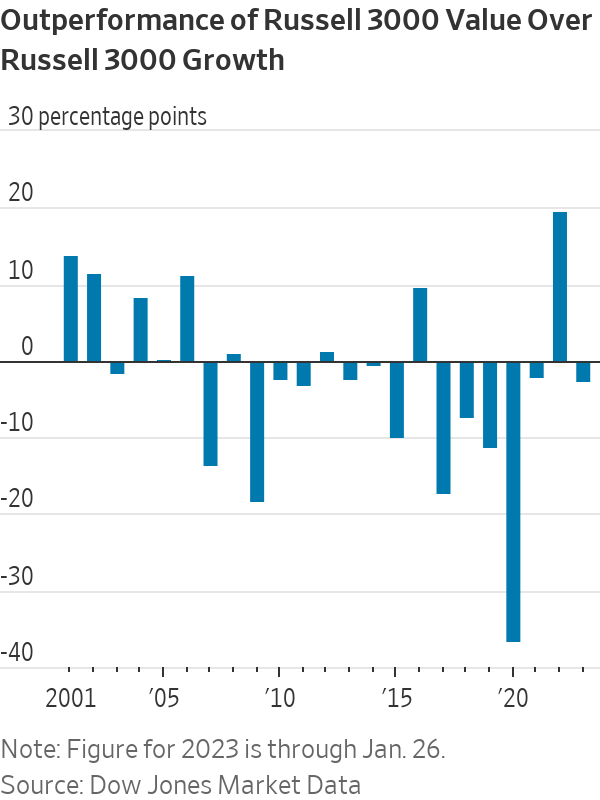
Still, he said that hasn’t changed his conviction that cheaper stocks in the market, known as value stocks, are bound to keep soaring past their peers. There might be short spurts of outperformance for more-expensive slices of the market, as seen in January. But over the long term, he is sticking to his bet that value stocks will beat growth stocks. He is expecting a volatile, but profitable, stretch for the trade.
“I love the value trade,” Mr. Asness said. “We sing about it to our clients.”
—Gunjan Banerji
Keeping dollar’s moves in focus
For Richard Benson, co-chief investment officer of Millennium Global Investments Ltd., no single trade was more important last year than the blistering rise of the U.S. dollar.
Once a relatively placid area of markets following the 2008 financial crisis, currencies have found renewed focus from Wall Street and Main Street. Last year the dollar’s unrelenting rise dented multinational companies’ profits, exacerbated inflation for countries that import American goods and repeatedly surprised some traders who believed the greenback couldn’t keep rallying so fast.
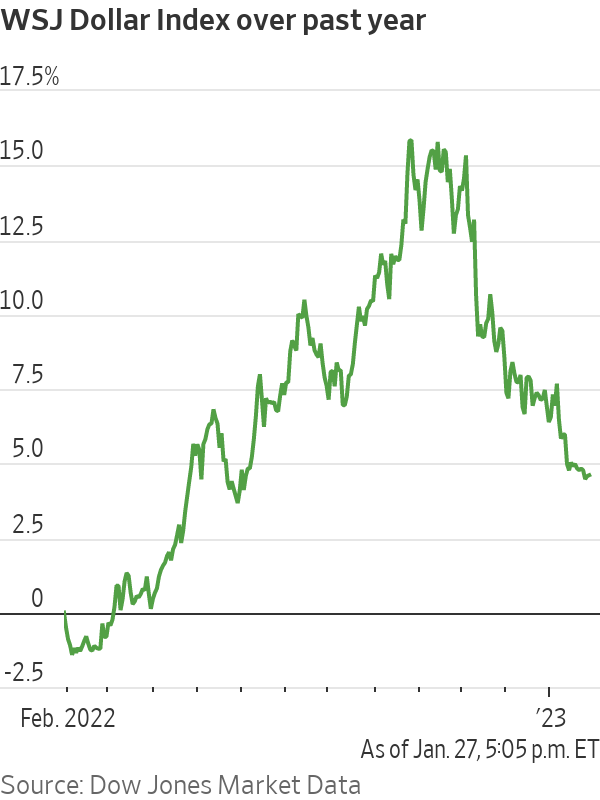
The factors that spurred the dollar’s rise are now contributing to its fall. Ebbing inflation and expectations of slower interest-rate increases from the Fed have sent the dollar down 1.7% this year, as measured by the WSJ Dollar Index.
Mr. Benson is betting more pain for the dollar is ahead and sees the greenback weakening between 3% and 5% over the next three to six months.
“When the biggest central bank in the world is on the move, look at everything through their lens and don’t get distracted,” said Mr. Benson of the London-based currency fund manager, regarding the Fed.
This year Mr. Benson expects the dollar’s fall to ripple similarly far and wide across global economies and markets.
“I don’t see many people complaining about a weaker dollar” over the next few months, he said. “If the dollar is falling, that economic setup should also mean that tech stocks should do quite well.”
Mr. Benson said he expects the dollar’s fall to brighten the outlook for some emerging- market assets, and he is betting on China’s offshore yuan as the country’s economy reopens. He sees the euro strengthening versus the dollar if the eurozone’s economy continues to fare better than expected.
—Caitlin McCabe
Stocks still appear overvalued
Even after the S&P 500 fell 15% from its record high reached in January 2022, U.S. stocks still look expensive, said Rupal Bhansali, chief investment officer of Ariel Investments, who oversees $6.7 billion in assets.
Of course, the market doesn’t appear as frothy as it did for much of 2020 and 2021, but she said she expects a steeper correction in prices ahead.
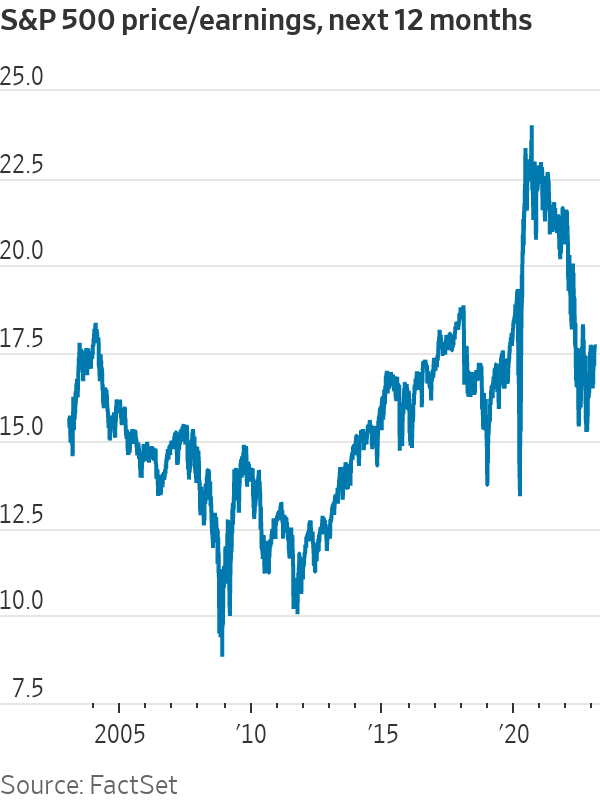
The broad stock-market gauge recently traded at 17.9 times its projected earnings over the next 12 months, according to FactSet. That is below the high of around 24 hit in late 2020, but above the historical average over the past 20 years of 15.7, FactSet data show.
“The old habit was buy the dip,” Ms. Bhansali said. “The new habit should be sell the rip.”
One reason Ms. Bhansali said the selloff might not be over yet? The market is still underestimating the Fed.
Investors repeatedly mispriced how fast the Fed would move in 2022, wrongly expecting the central bank to ease up on its rate increases. They were caught off guard by Fed Chair Jerome Powell‘s aggressive messages on interest rates. It stoked steep selloffs in the stock market, leading to the most turbulent year since the 2008 financial crisis. Now investors are making the same mistake again, Ms. Bhansali said.
Current stock valuations don’t reflect the big shift coming in central-bank policy, which she thinks will have to be more aggressive than many expect. Though broader measures of inflation have been falling, some slices, such as services inflation, have proved stickier. Ms. Bhansali is positioning for such areas as healthcare, which she thinks would be more insulated from a recession than the rest of the market, to outperform.
“The Fed is determined to win the war since they lost the battle,” Ms. Bhansali said.
—Gunjan Banerji
A better year for bonds seen
Gone are the days when tumbling bond yields left investors with few alternatives to stocks. Finally, bonds are back, according to Niall O’Sullivan of Neuberger Berman, an investment manager overseeing about $427 billion in client assets at the end of 2022.
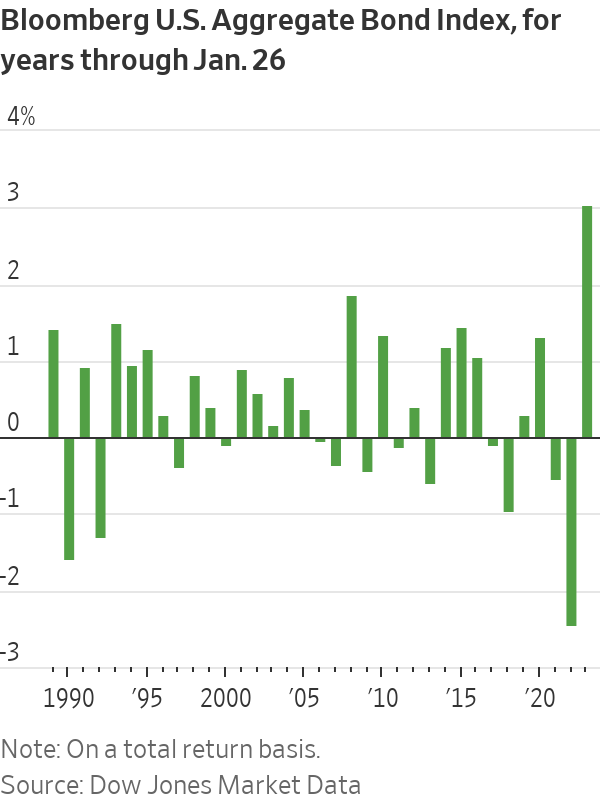
After a turbulent year for the fixed-income market in 2022, bonds have kicked off the new year on a more promising note. The Bloomberg U.S. Aggregate Bond Index—composed largely of U.S. Treasurys, highly rated corporate bonds and mortgage-backed securities—climbed 3% so far this year on a total return basis through Thursday’s close. That is the index’s best start to a year since it began in 1989, according to Dow Jones Market Data.
Mr. O’Sullivan, the chief investment officer of multi asset strategies for Europe, the Middle East and Africa at Neuberger Berman, said the single biggest conversation he is currently having with clients is how to increase fixed-income exposure.
“Strategically, the facts have changed. When you look at fixed income as an asset class…they’re now all providing yield, and possibly even more importantly, actual cash coupons of a meaningful size,” he said. “That is a very different world to the one we’ve been in for quite a long time.”
Mr. O’Sullivan said it is important to reconsider how much of an advantage stocks now hold over bonds, given what he believes are looming risks for the stock market. He predicts that inflation will be harder to wrangle than investors currently anticipate and that the Fed will hold its peak interest rate steady for longer than is currently expected. Even more worrying, he said, it will be harder for companies to continue passing on price increases to consumers, which means earnings could see bigger hits in the future.
“That is why we are wary on the equity side,” he said.
Among the products that Mr. O’Sullivan said he favours in the fixed-income space are higher-quality and shorter-term bonds. Still, he added, it is important for investors to find portfolio diversity outside bonds this year. For that, he said he views commodities as attractive, specifically metals such as copper, which could continue to benefit from China’s reopening.
—Caitlin McCabe
Find the fear, and find the value
Ramona Persaud, a portfolio manager at Fidelity Investments, said she can still identify bargains in a pricey market by looking in less-sanguine places. Find the fear, and find the value, she said.
“When fear really rises, you can buy some very well-run businesses,” she said.
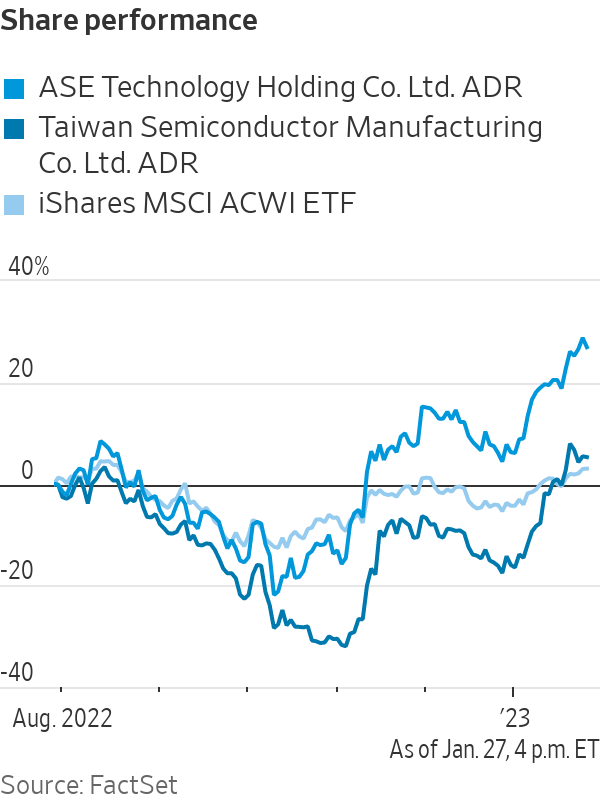
Take Taiwan’s semiconductor companies. Concern over global trade and tensions with China have weighed on the shares of chip makers based on the island. But those fears have led many investors to overlook the competitive advantages those companies hold over rivals, she said.
“That is a good setup,” said Ms. Persaud, who considers herself a conservative value investor and manages more than $20 billion across several U.S. and Canadian funds.
The S&P 500 is trading above fair value, she said, which means “there just isn’t widespread opportunity,” and investors might be underestimating some of the risks that lie in waiting.
“That tells me the market is optimistic,” said Ms. Persaud. “That would be OK if the risks were not exogenous.”
Those challenges, whether rising interest rates and Fed policy or Russia’s war in Ukraine and concern over energy-security concerns in Europe, are complicated, and in many cases, interrelated.
It isn’t all bad news, she said. China ended its zero-Covid restrictions. A milder winter in Europe has blunted the effects of the war in Ukraine on energy prices and helped the continent sidestep recession, and inflation is slowing.
“These are reasons the market is so happy,” she said.
—Justin Baer
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min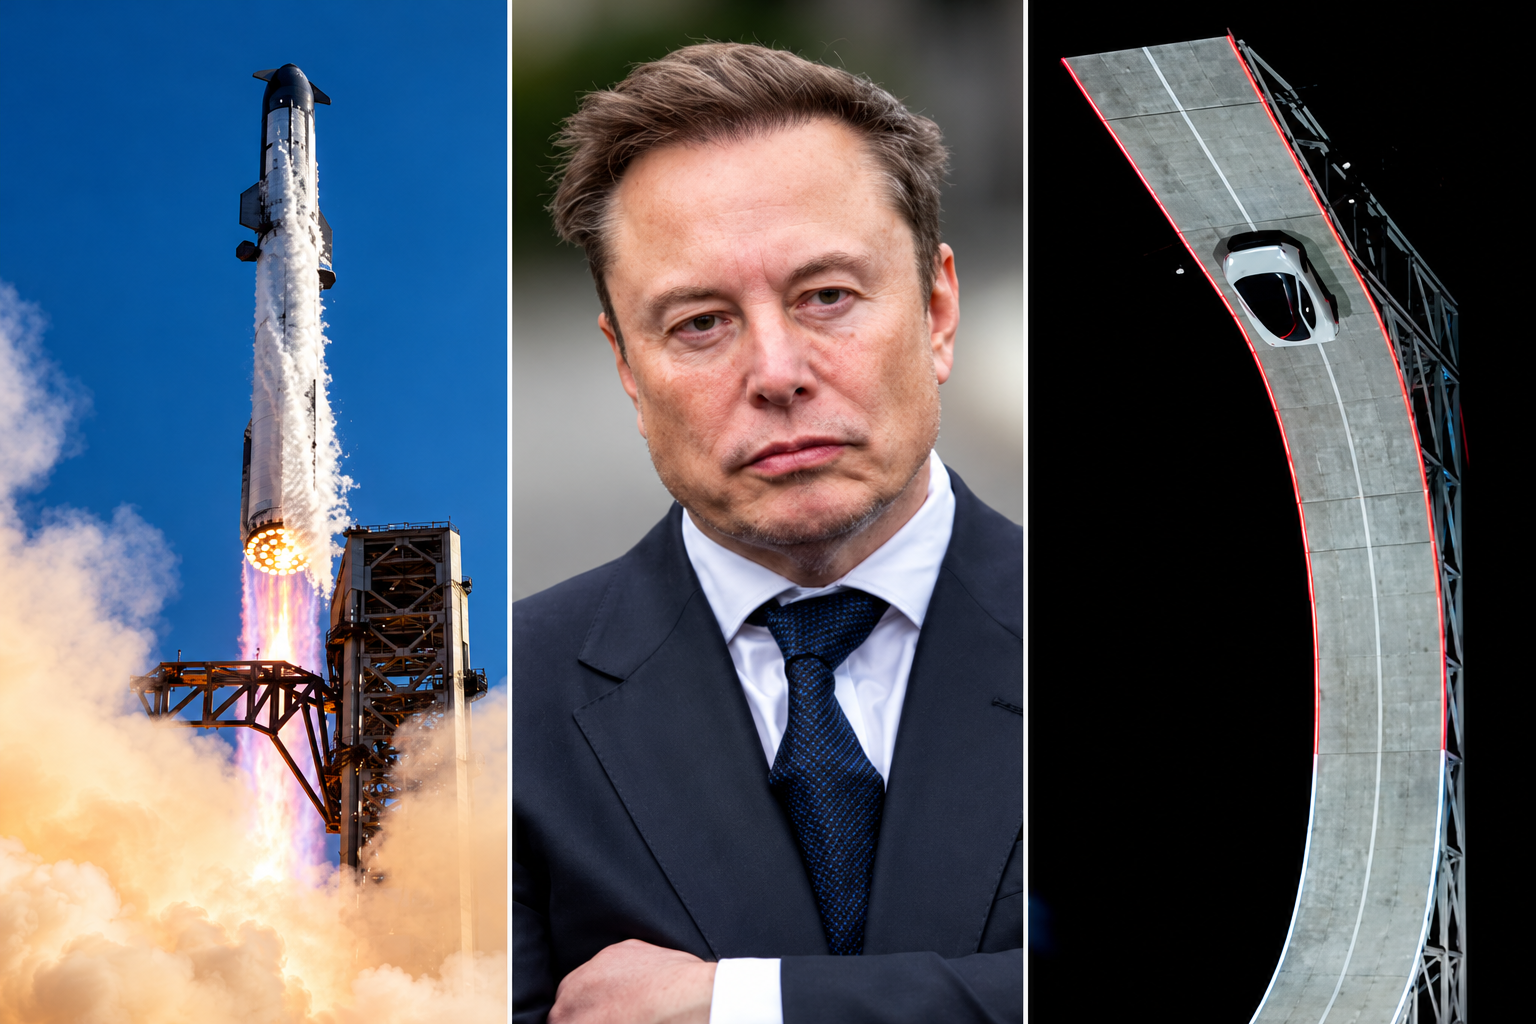
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.
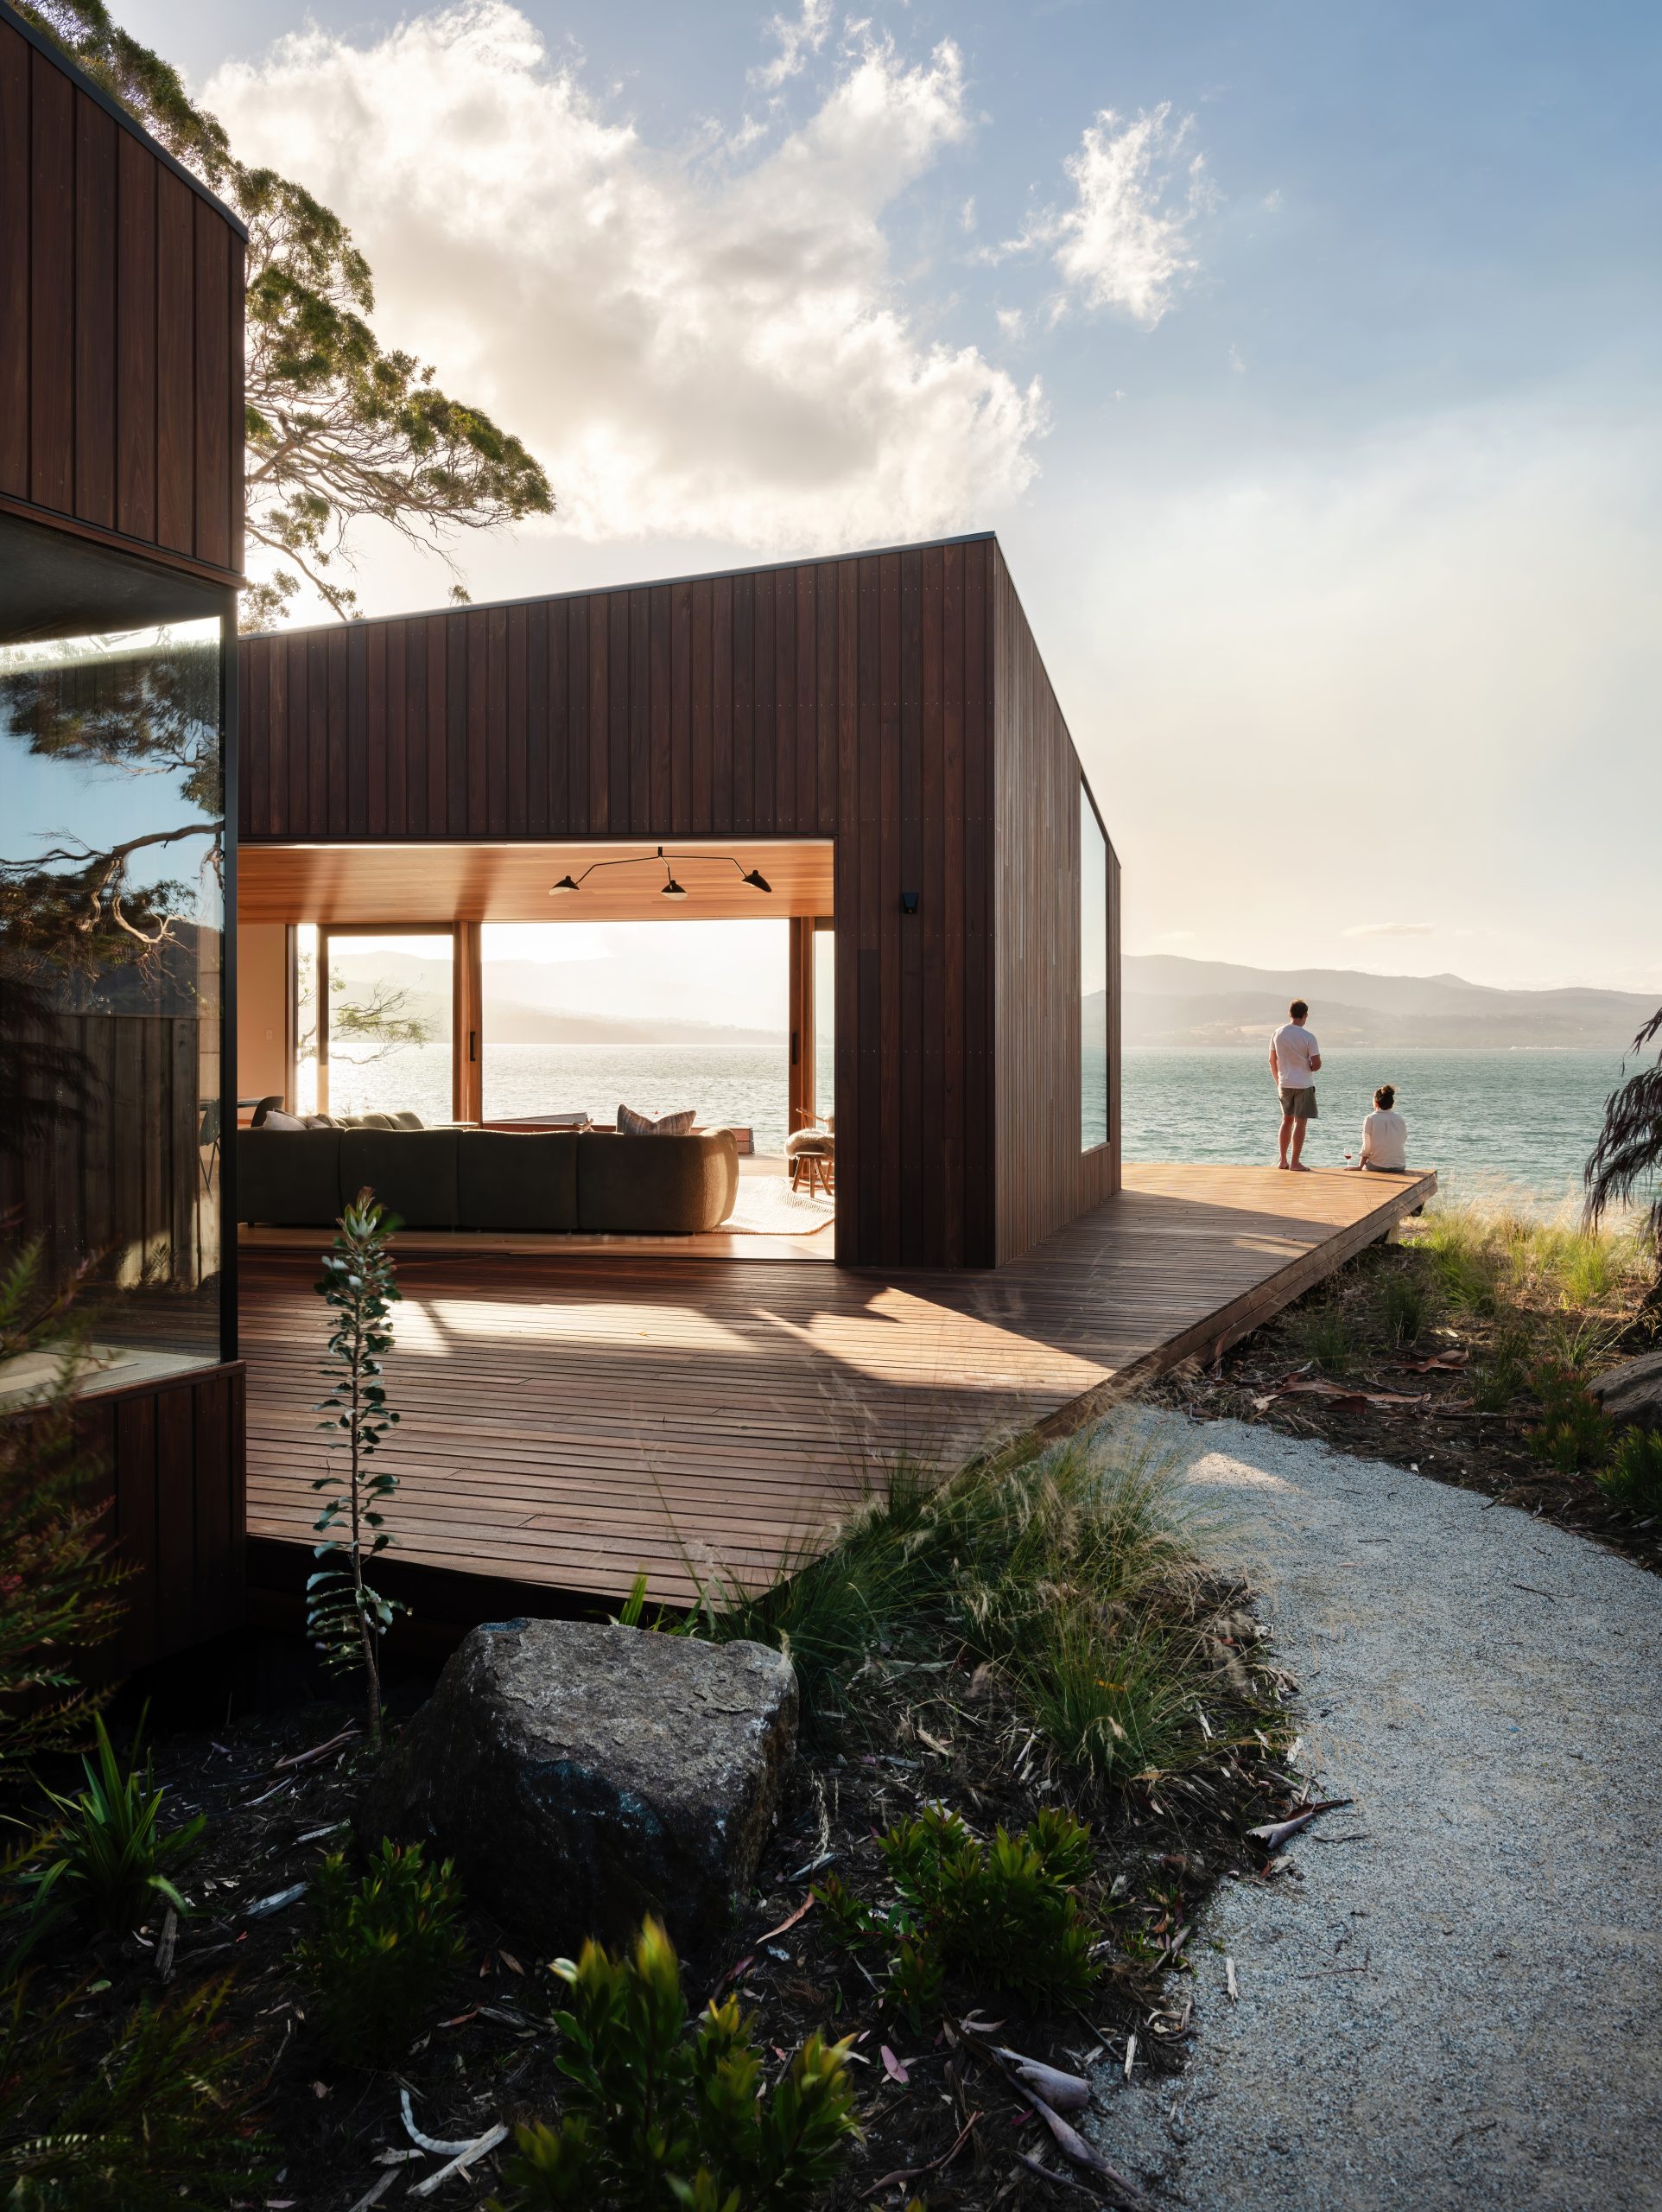
From the shacks of yesterday to the sculptural sanctuaries of today, Australia’s coastal architecture has matured into a global benchmark for design.

From Italy’s $93,000-a-night villas to a $20,000 Bowral château, a new global ranking showcases the priciest Airbnbs available in 2026.