Europe’s Gas-Guzzling Days Are Fading
In a reality check for natural-gas producers, volatile prices are prompting European homes and factories to go green faster than expected

 3 min

Last year’s hottest gas market has cooled, and some of the change will stick.
Demand for natural gas in Europe hasn’t bounced back despite lower prices. The region’s TTF benchmark price is down 85% compared with a year ago, when Europe was rushing to fill its gas-storage facilities for winter after Russia cut off supply.
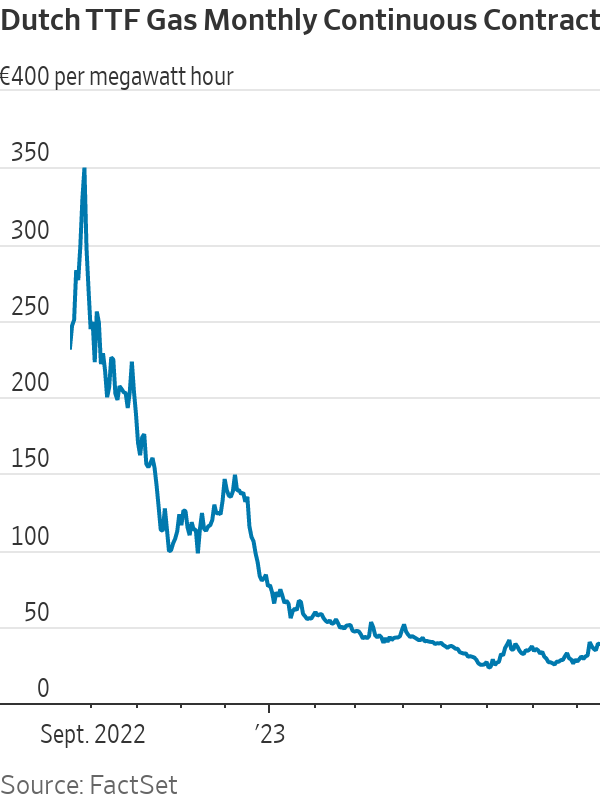
Prices have fallen partly because Europe’s gas storage is already full. It hit a 90% capacity target last week, more than two months ahead of a schedule set last year by the European Union.
But underlying demand is also weak. According to think tank Bruegel’s European natural gas demand tracker, use of gas in the first quarter of this year was 18% lower than the 2019-2021 average, and 19% below in the second quarter. The declines have accelerated from the 12% fall recorded last year.
Weaker economic growth is one reason why gas use hasn’t recovered. Another may be that lower wholesale prices haven’t been passed on to end users yet, according to Ben McWilliams, author of the Bruegel tracker.
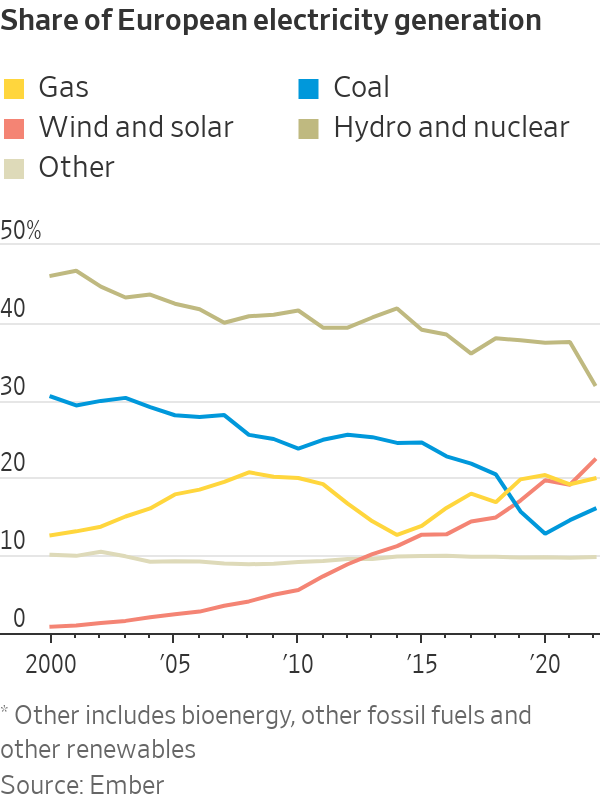
Other factors will be more permanent, notably new technologies. The European Heat Pump Association said sales of heat pumps rose 39% in 2022. They are now installed in 16% of Europe’s residential and commercial buildings, often replacing gas boilers. Heat pumps require electricity, which is often produced using gas, but this too is changing. Installations of new solar capacity rose a record 47% in 2022, and last year was the first time that renewable power generated more of Europe’s electricity than natural gas.
One uncertainty for future gas demand is whether European industries such as chemicals and fertiliser manufacturing will return to normal. The International Energy Agency thinks that up to half of the decline in Europe’s industrial gas demand last year was a result of production shutdowns. Certain companies whose business model traditionally relied on cheap Russian gas moved manufacturing to lower-cost regions such as the U.S., where gas costs roughly a quarter of the European spot price.
European gas prices will be volatile until more global liquefied natural gas supply arrives in 2025. The TTF jumped 5% on Monday because of worries about strikes at an Australian LNG terminal. Companies may be reluctant to restart their European factories until the region’s energy costs are more predictable.
Before the Ukraine war, global demand for natural gas was expected to increase 18% between 2021 and 2030, according to estimates from the Oxford Institute for Energy Studies. This forecast has since been cut to 10%. Lower growth expectations reflect the sharp cutbacks in Europe as well as the U.S. Inflation Reduction Act, which will supercharge America’s shift to renewable energy.
None of this is ideal for the U.S. LNG players who are currently pouring billions of dollars into new production. Based on projects that have already secured funding, and those in the pipeline, U.S. LNG export capacity could double by the end of this decade, according to Wood Mackenzie estimates.
True, Europe needs plenty of LNG over the next few years to replace the shortfall left by Russian pipeline gas. But the faster the region weans itself off gas, the sooner exporters will need to find a new home for at least some of their cargoes.
The expectation is that countries still using a lot of coal in power generation, such as India and Pakistan, will eventually switch to natural gas to cut their carbon emissions—assuming prices come down enough to make that transition affordable. “The window of opportunity for natural gas is tightening all around the world, although coal-reliant markets in Asia provide growth prospects over the medium-term,” says Gergely Molnar, energy analyst at IEA.
Buyers and sellers of natural gas took very different lessons from last year’s record prices, and the fuel’s reputation as a cheap, reliable form of energy took a hit. The pace of change in Europe’s gas market raises the risk of a glut.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE



From making unpopular decisions to learning when to listen, leaders from five businesses reveal what nobody prepared them for — and how running a company has challenged their expectations.

Technology and semiconductor shares fell sharply as investors questioned the debt financing the AI infrastructure boom and confronted higher rates and Chinese competition.

Elon Musk is exploring a potential merger between Tesla and SpaceX, a deal that could reshape the future of AI, robotics, autonomous vehicles and space technology. With a combined valuation potentially reaching $3.5 trillion, the move could bring Musk’s vision of an interconnected technology ecosystem closer to reality, although a deal remains uncertain.
5 min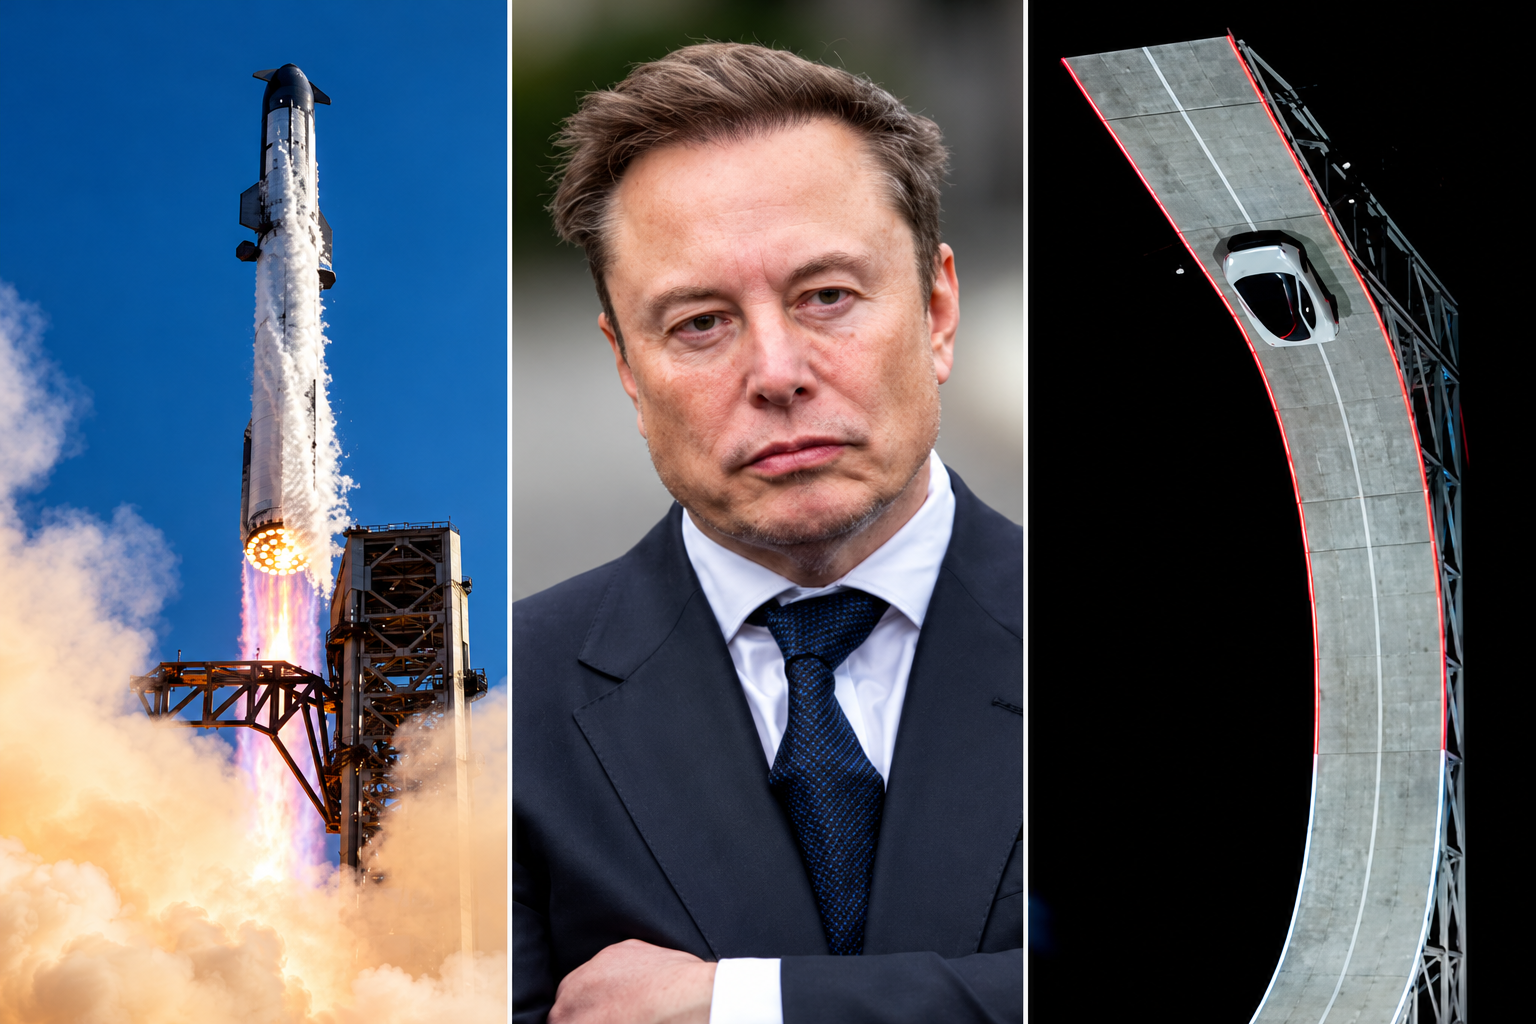
Elon Musk has engineered ties between Tesla TSLA 3.41%increase; up pointing triangle and SpaceX SPCX 7.79%increase; up pointing triangle that are hard to break, and now he wants to fuse them together permanently.
Musk has run both Tesla and SpaceX concurrently over the past two decades, using a schedule that dictated which days he spent focused on each business.
The companies have often shared resources and personnel, signaling their close ties. Last year, SpaceX looked into creating a spacesuit for Tesla’s humanoid robot Optimus, a person familiar with the matter said. Tesla last week showed off its new Roadster, a vehicle featuring SpaceX rocket thrusters that it hopes to soon bring to market.
And in recent months, Musk has repositioned both companies by expanding beyond their core operations toward a shared mission centered on artificial intelligence.
The world’s richest man on Tuesday signaled his interest in tying up SpaceX and Tesla, marking what would be the biggest corporate merger of all time. Because he serves as chief executive of SpaceX and Tesla, Musk said committees of independent directors at both companies are evaluating a possible deal, adding that a transaction might not come to fruition.
The committees will likely evaluate, with lawyers and bankers, how each company would fare in a potential deal and how a deal might best be structured. They then present their conclusions to their respective boards, who typically vote on whether to proceed.
“It’s an odd Kabuki dance where two groups of people are talking and I can’t be in the conversation,” Musk told SpaceX investors on Tuesday in response to an analyst’s question about a potential deal.
For Musk, the merger supports his vision of a world full of autonomous cars, humanoid robots and weekly rocket launches, as well as the data centers and satellites required to keep the whole thing running.
Some investors and analysts said they expect a transaction would be structured as an all-stock deal, with SpaceX potentially paying a modest premium for Tesla shares.
SpaceX, which has a market value of about $2 trillion, said it is seeing sharp growth in revenue across its businesses, which include operating data centers, launching rockets and operating satellite networks such as the internet service Starlink. Tesla is valued at about $1.5 trillion and is expanding its operations beyond its automotive and energy business. Shares in both companies traded higher following the news Tuesday.
Musk’s substantial ownership stakes in both companies, along with voting control at SpaceX, has enabled him to set the deal in motion. Analysts and investors said the deal will probably face regulatory scrutiny internationally, though some see Musk’s close relationship with the Trump administration as an asset to getting approval.
Blurred lines
The companies haven’t said which directors are on the special committees evaluating a potential deal. Several SpaceX and Tesla board members have either personal or business ties to Musk. And like Musk, venture capitalist Ira Ehrenpreis sits on both boards.
In a filing this week, Tesla outlined millions of dollars in business agreements with SpaceX and its subsidiaries last year, including $143 million in car sales to SpaceX, $3.3 million in advertising that it bought on the social-media platform X and $430 million in revenue from the sale of Megapack batteries for SpaceX’s data centers.
The companies also split the cost of resources including the use of Musk’s SpaceX jet and the bill for his personal security, which he runs through a private company.
Employees at both companies routinely move between companies to work on special projects, and some executives have dual roles, including Charles Kuehmann, vice president of materials engineering at both SpaceX and Tesla, and Ashok Elluswamy, the vice president of AI software at Tesla who runs a joint venture with SpaceX called Digital Optimus.
Over the years, Musk has launched new startups within his empire, including brain-implant company Neuralink, underground-tunnel developer the Boring Company and xAI, the AI startup that merged with SpaceX in February.
It is that AI business that Musk thinks can serve a market worth tens of trillions of dollars, justifying the need for a merger.
The business case goes like this: Tesla is developing robotaxis and robots, which it calls “physical AI.” SpaceX is working on the back end of physical AI: the data-center capacity and internet connection required for those robotaxis and robots to operate continuously.
“I don’t see what the value of Tesla is if it’s not merged with SpaceX,” said investment adviser Ross Gerber, a former Tesla bull turned critic invested in both companies. “If they don’t merge, the brains of everything that runs Tesla is owned by another company.”
On top of it all, both companies face constraints on the supply chains they need to make this world a reality, particularly when it comes to chips. To address this, Musk earlier this year announced a joint venture between Tesla, SpaceX and Intel to design and manufacture chips in Texas. “The most epic chip-building exercise by far,” he has said.
Musk at the wheel
For Musk, a merger would also solve two problems: demands on his attention and his lack of control at Tesla.
Tesla for years was Musk’s only public company, a status that came with greater scrutiny. There, Musk reports to a public board, as well as individual investors who make up around 30% of Tesla’s voting power, according to FactSet.
The question of Musk’s attention became a particular focus for investors and the board in recent years after he acquired Twitter in 2022 and launched xAI in 2023, and again in 2025 as he spent time in Washington, D.C., running the Department of Government Efficiency in the early months of President Trump’s second term.
As Tesla’s car business suffered in 2025, Musk threatened to take his AI ambitions outside the company if he wasn’t granted 25% voting control. Last November, Tesla shareholders approved a new pay package for Musk, which created a path for him to vastly expand his stake.
As of Sept. 30, Musk owned a roughly 20% stake in Tesla, according to the company’s proxy filing.
The SpaceX IPO gave Musk a different path. When SpaceX went public in June, the deal’s structure enabled him to have more than 80% voting power at the company—so much that he can’t be fired and decisions can’t be made without his support.
If SpaceX acquires Tesla, he will likely stay in control.
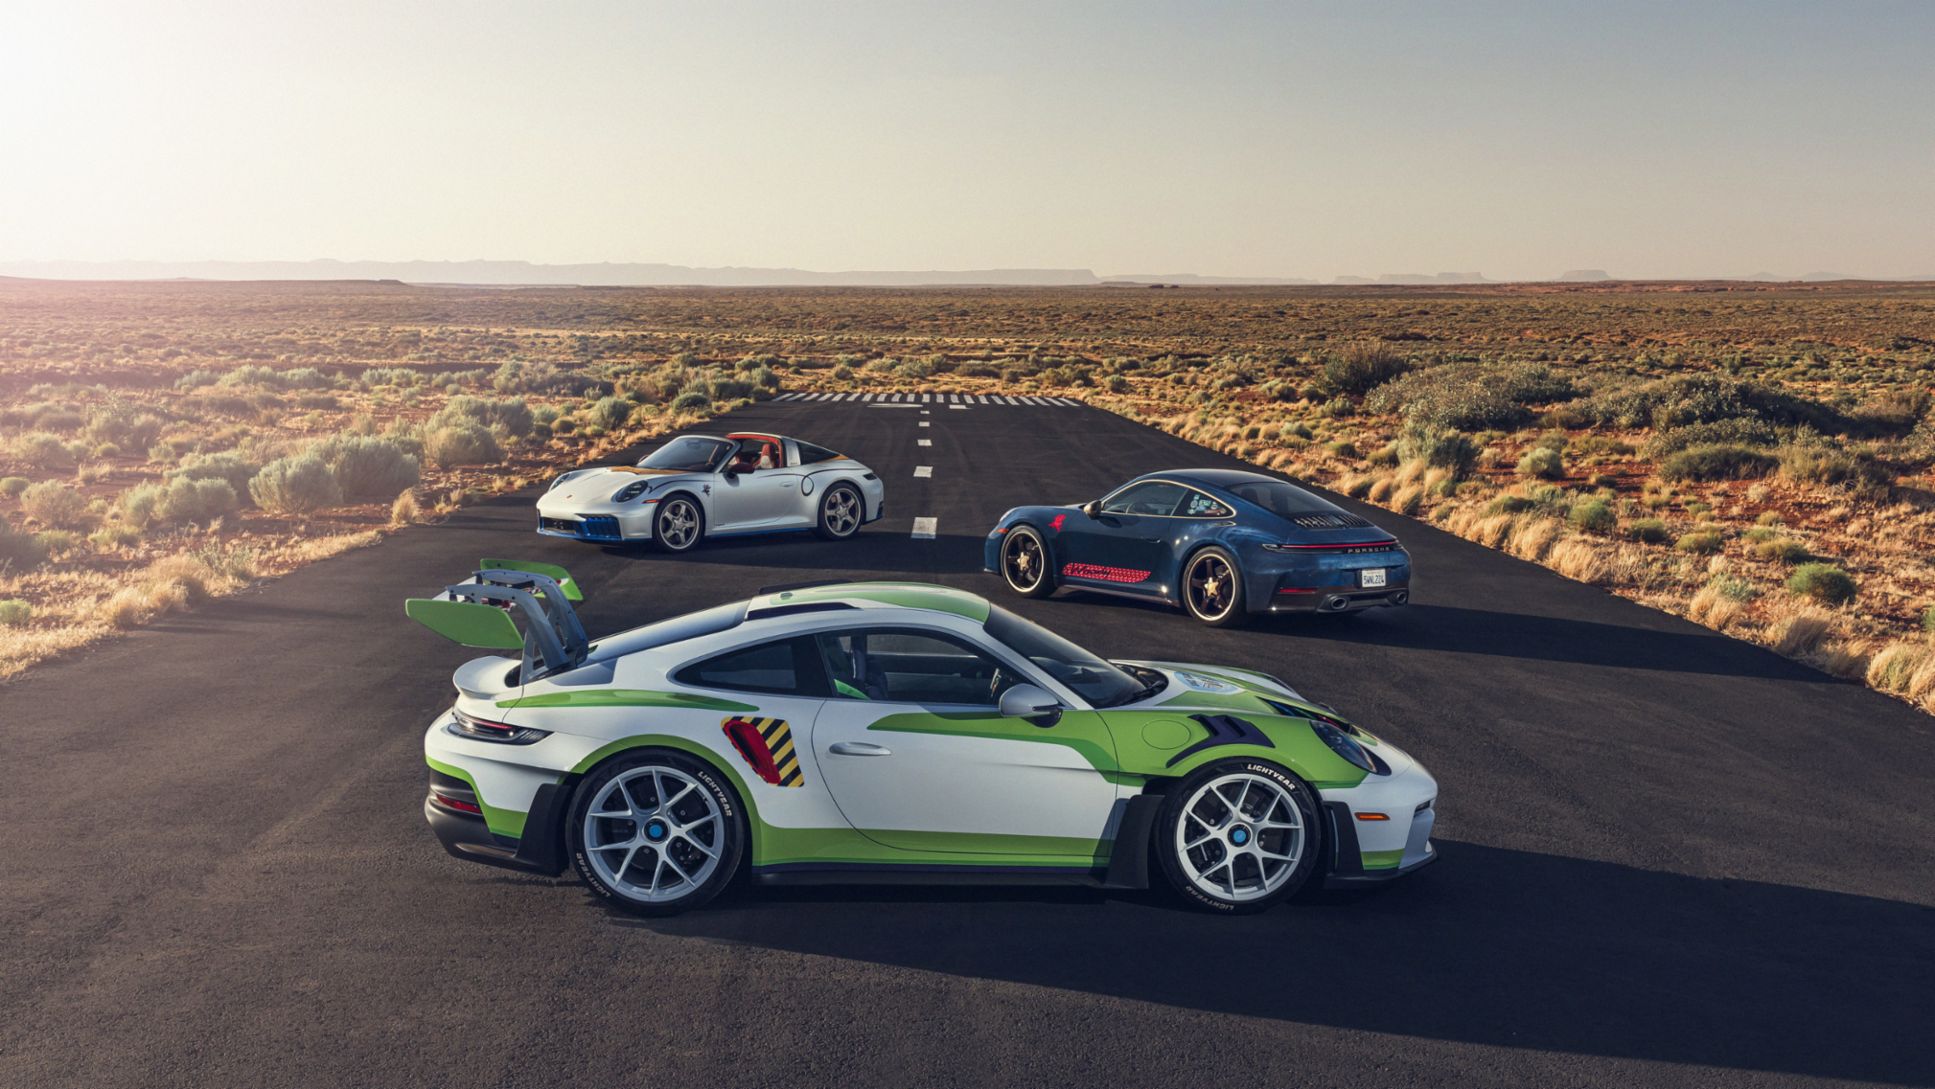
All three vehicles will form part of a broader charitable initiative benefiting Big Brothers Big Sisters of America, the American Red Cross and Starlight Children’s Foundation

Margot Robbie and Jacob Elordi star in an adaptation of the classic novel that respects the romance’s slow burn.