How Much Will You Spend on a Bottle of Wine? Americans Now Say $21.

 2 min

Americans may be feeling financially constrained these days. And they may also be drinking less, as exemplified by the booming Dry January movement.
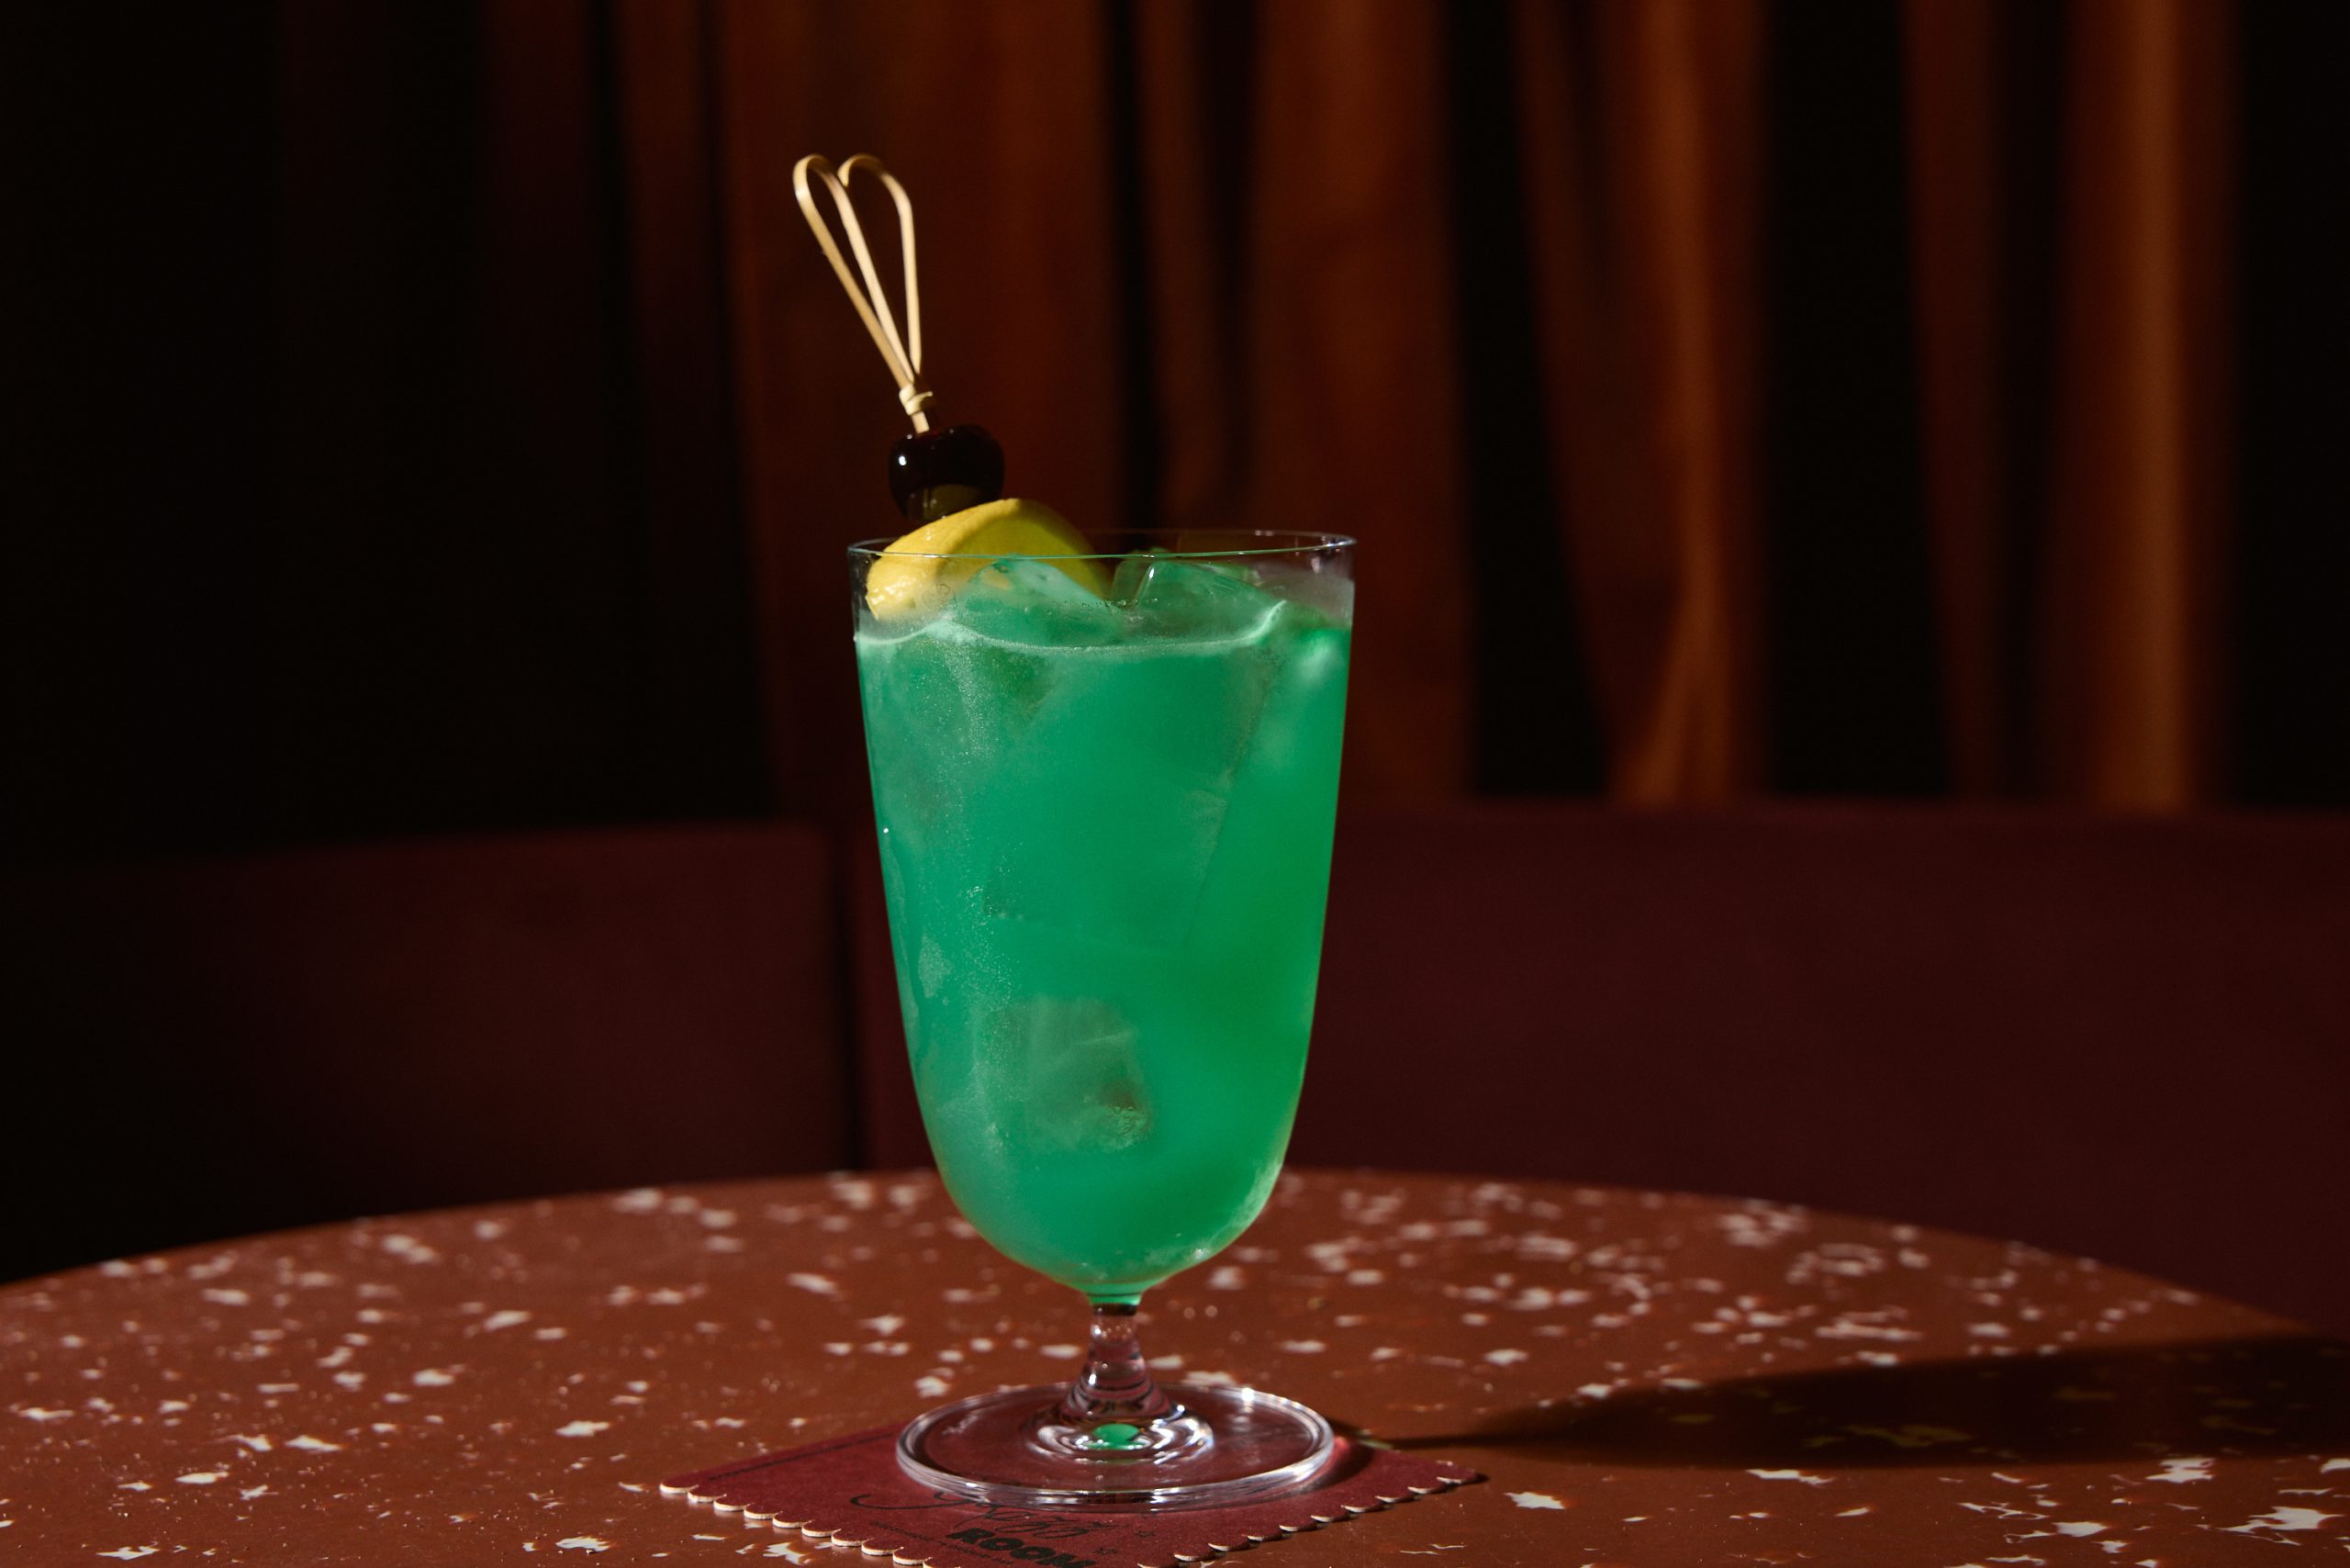
But that’s not stopping them from spending $21 on a bottle of wine.
That’s the price that has emerged as the consumer “sweet spot,” according to a new survey of more than 1,000 wine-industry professionals. And the figure is higher than a year ago, when the same survey, done by the wine-promotion company Colangelo & Partners and research firm Wine Opinions, found that $20 was the hot price tag.
To be clear, wines priced $10 and under—the so-called “jug” or “popular premium” categories—still account for the bulk of U.S. wine purchases. But a growing number of consumers are trading up—and that’s where the $21 “sweet spot” figure comes into play.
“It’s where the industry sees the most excitement and enthusiasm,” said Juliana Colangelo of Colangelo & Partners.
Wine professionals point to a variety of factors that explain why consumers are willing to spend $21 for a bottle.
For starters, many Americans have become more sophisticated about wine and can talk knowingly of a range of varietals and styles in a way that was unheard of a generation ago. And with that level of sophistication comes that desire to trade up, wine pros say.
“They want to expand their horizons,” said Leo Le, beverage director of Momoya Soho, a New York City restaurant.
Adam Levy, who organises wine competitions in cities across the world and heads up the Alcohol Professor website, said that he believes people are entertaining more at home, given the Covid-era hesitancy about eating at restaurants. And when they entertain, they’re willing to spend a little more, he explained, especially given that prices for bottles are still much lower at retailers versus restaurants.
Levy also said that wine prices have generally been increasing, due to supply-chain issues and other factors, so consumers who want to drink better will have to pay more by extension. “There’s so much pressure on wine producers,” he said.
Finally, Colangelo makes the point that natural wines have become very popular, especially with younger consumers. These wines are typically more expensive, so it stands to reason that the pricing “sweet spot” will go higher over time.
“You don’t really get a naturally produced wine for less than $20,” she said.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


Australian shares fell on Thursday as Wall Street weakness, rising oil and persistent rate concerns weighed on most of the market. The S&P/ASX 200 declined 0.72 per cent to 8,702. The All Ordinaries lost 0.66 per cent to finish at 8,897. Mining stocks were hit particularly hard, while real estate also dragged on the index. …
Continue reading “ASX falls 0.7 per cent as miners and property stocks retreat”

Borrowers cannot control the Reserve Bank, but they can control how exposed their household budget is to its next decision. The RBA meets on 29 September with inflation concerns still elevated and major-bank economists increasingly bringing forward their rate-rise calls. Fixed mortgage rates have also been moving, reducing the value of waiting for perfect certainty. …
Continue reading “What mortgage holders should do before the next RBA decision”
2 min
A property portfolio can look comfortable until several small pressures arrive together: a rate increase, a vacancy, higher insurance and an unexpected repair. The correct time to model that combination is before it occurs.
Start by recalculating every loan at 0.25, 0.50 and one percentage point above its current rate. Include principal-and-interest repayments even where a loan is temporarily interest-only, because the eventual step-up may be larger than the next RBA move.
Then calculate true net rent. Deduct management, council and water charges, strata, insurance, maintenance, land tax where applicable and a vacancy allowance. A property advertised with an attractive gross yield can produce a very different result after these costs.
Third, review the portfolio’s liquidity. An offset account can reduce interest while keeping cash accessible, but investors should obtain tax advice before moving funds between loans. The distinction between investment and private debt affects deductibility, and poorly structured redraws can create lasting complexity.
Fourth, examine refinancing risk rather than just today’s rate. A highly leveraged investor may be unable to refinance on the same terms because the new lender tests total debt at a higher assessment rate. Credit-card limits, owner-occupied debt and shaded rental income can all reduce capacity.
Fifth, rank properties by resilience. Consider net yield, vacancy risk, near-term capital expenditure, tenant demand, debt attached and the cost of selling. This is not an instruction to sell the weakest performer automatically; transaction costs and tax consequences matter. It is a way to identify where pressure would emerge first.
Investors should also review fixed-rate and interest-only expiry dates. A portfolio with several facilities resetting in the same quarter carries concentration risk even when each loan appears manageable individually.
The goal is not to predict the RBA perfectly. It is to ensure that one policy decision does not force a rushed refinancing, sale or reduction in essential maintenance. A portfolio that can absorb higher rates and temporary income interruptions gives its owner time to make deliberate decisions.
Read more: What mortgage holders should do before the next RBA decision
Portfolio checklist
Stress test: Current rate plus 0.25, 0.50 and one percentage point.
Model: Net rent after every recurring cost and vacancy.
Check: Fixed-rate expiries, interest-only expiries and loan maturity.
Preserve: An accessible emergency buffer.
Review: Insurance, land tax, strata works and major maintenance.
Seek advice: Licensed credit, financial and tax advice before restructuring.
From mud baths to herbal massages, Fiji’s heat rituals turned one winter escape into a soul-deep reset.
Australia’s housing market defies forecasts as prices surge past pandemic-era benchmarks.